Promomed: revenue up 75.7%, but profit barely reached the cash
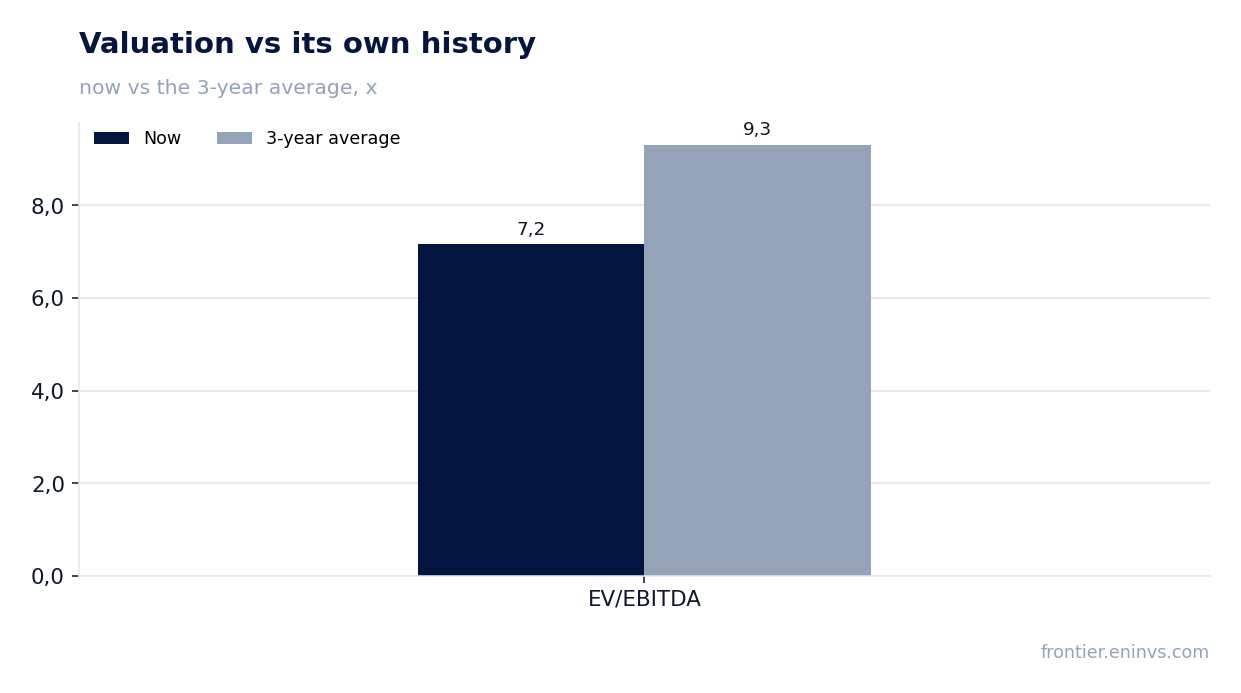
On 31 August Promomed released its Q2 2026 results. Revenue rose 75.7% year on year, EBITDA by 88.7%, net profit by 82.6%, and the EBITDA margin reached 34.2% against 31.8% a year earlier. Yet operating cash flow for the quarter was negative at RUB -899.9 mln, and net debt stood at RUB 46.8 bn on 30 June 2026. At an EV/EBITDA of 7.2 against its own three-year average of 9.3 the share looks cheaper than its own history, and the verdict is 'rather attractive'.
Key takeaways
— Revenue added 75.7% on innovative drugs and business scaling
— EBITDA rose 88.7%, and the 34.2% margin is above last year's 31.8%
— Net profit rose 82.6%, but a RUB 859.6 mln reserve recovery supported it
— Operating cash flow for the quarter was negative at RUB -899.9 mln against RUB 1,354.0 mln of capex
— Net debt rose from RUB 22.3 bn at end-2025 to RUB 46.8 bn on 30 June 2026
— The RUB 8.0 per share dividend yields 1.9% – modest against the key rate
— EV/EBITDA of 7.2 is below its own three-year average of 9.3, and the portal model implies +41% upside
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 6.49 | 11.4 | +75.7% |
| EBITDA | 2.07 | 3.90 | +88.7% |
| Operating profit | 1.74 | 3.47 | +99.6% |
| Net profit | 0.71 | 1.29 | +82.6% |
| Operating cash flow | -0.37 | -0.90 | — |
| Capex | — | 1.35 | — |
| EBITDA margin | 31.8% | 34.2% | +2.4 pp |
| Net margin | 10.9% | 11.4% | +0.5 pp |
Revenue added 75.7% on innovative drugs and business scaling
Q2 2026 revenue came to RUB 11,398.8 mln, 75.7% more than a year earlier. In the report management attributes the growth to sales of innovative drugs and the scaling of the group's business. For the first half revenue reached RUB 22,796.8 mln against RUB 12,974.7 mln a year earlier.
The company explicitly warns about seasonality: most of its revenue falls in the second half because of the tender procurement period. The quarterly result therefore cannot be mechanically carried over to the full year, but the growth rate itself shows that demand for the group's products remains high.
For comparison, Q4 2025 revenue was RUB 12,299.0 mln, so Q2 2026 came close to the peak level of the end of last year. This suggests the growth is not merely a seasonal spike.
EBITDA rose 88.7%, and the 34.2% margin is above last year's 31.8%
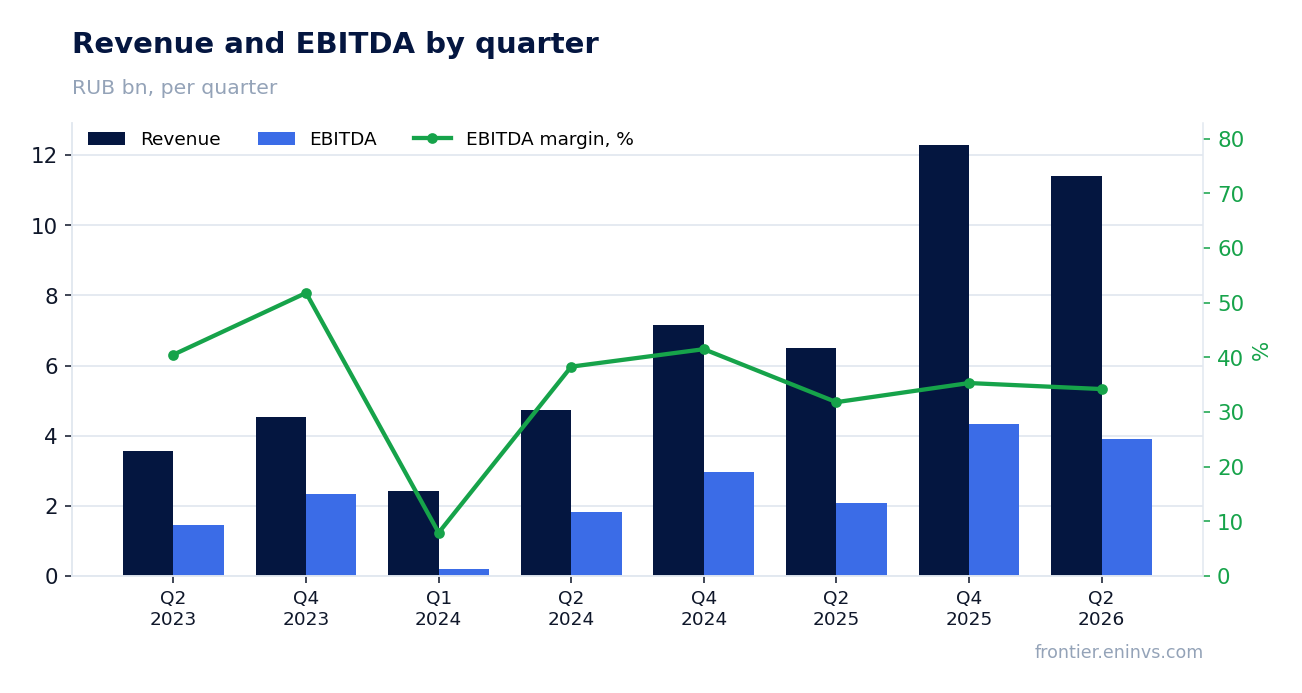
Q2 2026 EBITDA came to RUB 3,897.7 mln, 88.7% more than a year earlier. The EBITDA margin rose to 34.2% from 31.8% a year earlier – revenue growth is outpacing cost growth.
Operating profit for the quarter was RUB 3,473.2 mln. For the half-year operating profit reached RUB 6,946.4 mln against RUB 3,479.4 mln a year earlier. Gross profit for the half-year rose to RUB 15,235.0 mln from RUB 7,967.9 mln, meaning cost of sales grew slower than revenue.
Selling expenses for the half-year, however, rose to RUB 5,682.4 mln from RUB 2,542.5 mln, and general and administrative expenses to RUB 2,986.1 mln from RUB 1,768.9 mln. Part of the margin gain therefore comes from gross profitability rather than from savings on sales and administration.
Net profit rose 82.6%, but a RUB 859.6 mln reserve recovery supported it
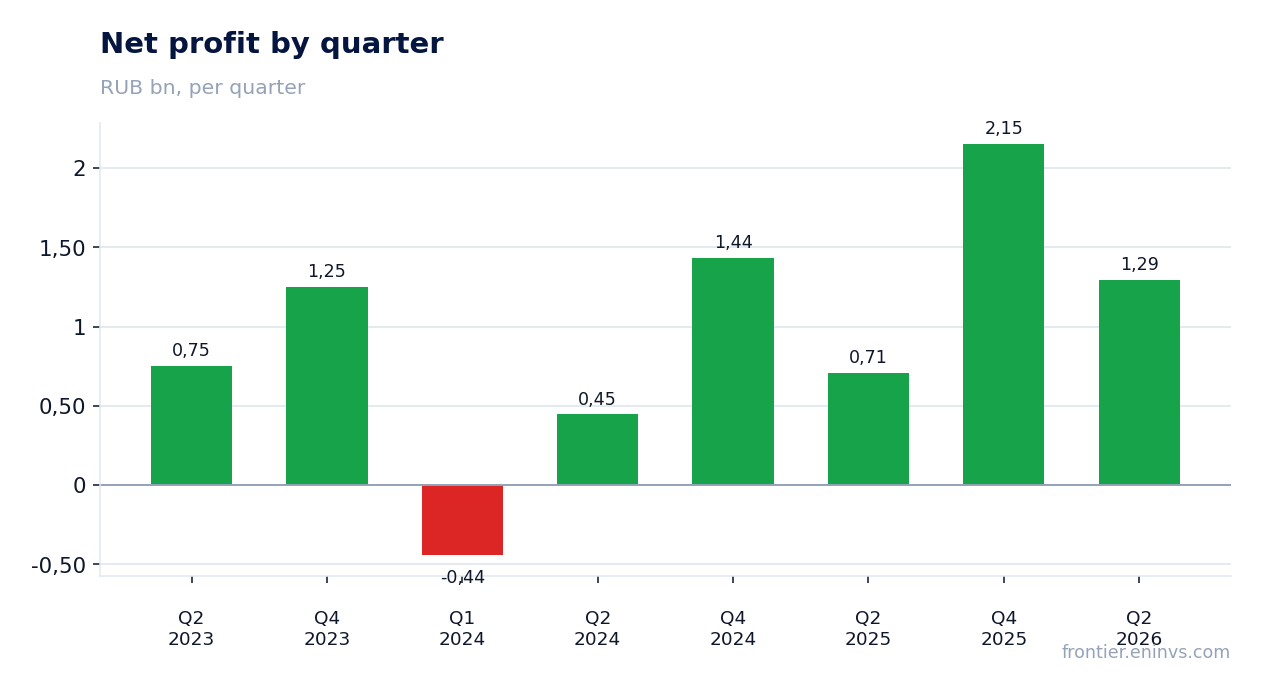
Q2 2026 net profit came to RUB 1,294.3 mln, 82.6% more than a year earlier. The net margin rose to 11.4% from 10.9%. For the half-year profit attributable to the parent's shareholders was RUB 2,498.7 mln against RUB 1,395.4 mln a year earlier.
The half-year income statement contains a line that materially affects the result: a recovery of impairment loss on financial assets and contract assets of RUB 859.6 mln against a loss of RUB 46.8 mln a year earlier. Without this one-off effect profit would have been lower.
Finance costs for the half-year rose to RUB 3,729.5 mln from RUB 2,156.5 mln – debt servicing is becoming an increasingly visible item. Profit before tax for the half-year was RUB 3,520.6 mln against RUB 1,974.6 mln a year earlier.
Operating cash flow for the quarter was negative at RUB -899.9 mln against RUB 1,354.0 mln of capex
Q2 2026 operating cash flow was negative at RUB -899.9 mln. For the half-year net cash used in operating activities was RUB 1,799.8 mln against RUB 742.8 mln a year earlier. The company attributes this to purchases of raw materials and higher production for future sales, as well as a large income tax payment.
Inventories for the half-year rose to RUB 16,302.2 mln from RUB 11,636.8 mln at end-2025, including finished goods to RUB 7,428.2 mln from RUB 4,500.6 mln. The group plans to sell this output in the second half of 2026.
Capex for the quarter was RUB 1,354.0 mln. For the half-year payments for the acquisition and creation of fixed assets reached RUB 1,536.4 mln and of intangible assets RUB 1,171.6 mln. Together with negative operating cash flow this means investment is being financed with debt.
Net debt rose from RUB 22.3 bn at end-2025 to RUB 46.8 bn on 30 June 2026
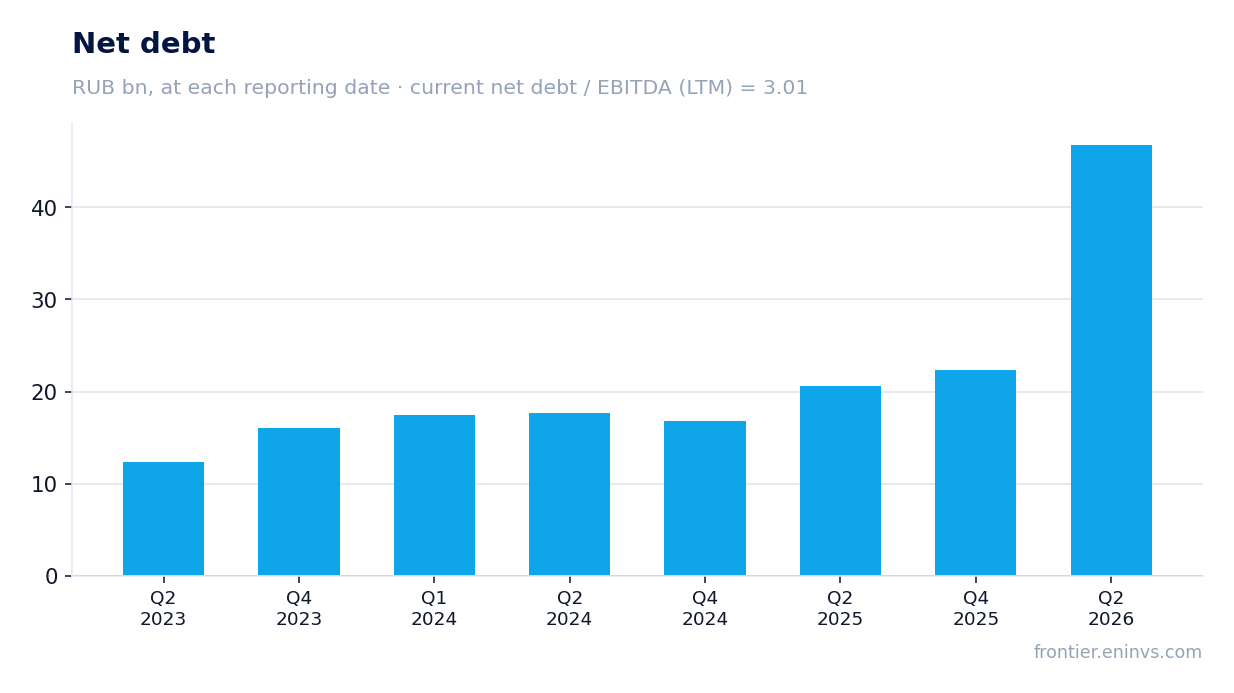
Net debt on 30 June 2026 was RUB 46.8 bn against RUB 22.3 bn on 31 December 2025 – an increase of RUB 24.5 bn. Over the year, from 30 June 2025, net debt rose from RUB 20.6 bn to RUB 46.8 bn, i.e. by RUB 26.2 bn.
The net debt to EBITDA ratio for the last twelve months is 3.01. That is a level at which debt servicing requires a sustained cash flow. Finance costs for the half-year rose to RUB 3,729.5 mln from RUB 2,156.5 mln, and with negative operating cash flow debt keeps growing.
In the debt structure on 30 June 2026 short-term loans and borrowings were RUB 13,215.0 mln, long-term RUB 18,964.8 mln, plus convertible bond liabilities of RUB 1,268.2 mln and other financial liabilities of RUB 2,564.2 mln for deferred payments on fixed assets.
The RUB 8.0 per share dividend yields 1.9% – modest against the key rate
Over the last 12 months Promomed paid RUB 8.0 per share, which at the current price gives a yield of 1.9%. In 2026 the dividend was paid at RUB 8.0 per share at an ex-date price of RUB 383.7, i.e. 2.1% on the payment date.
For the first half of 2026 dividends paid amounted to RUB 1,423.6 mln and dividends declared to RUB 1,633.9 mln. With net profit of RUB 8,338.5 mln over the last twelve months this corresponds to a payout of about 20%. Our estimate: if this practice and current profit persist, the dividend for the year may stay around RUB 8–10 per share, but much depends on how much cash the investment programme requires.
A yield of 1.9% is well below the key rate, so the dividend is not the main argument for the share. It is more a signal of willingness to share profit than a source of income. The payout could be reduced by rising capex and debt servicing, which are already visible in the report.
EV/EBITDA of 7.2 is below its own three-year average of 9.3, and the portal model implies +41% upside
At an EV/EBITDA of 7.2 the share trades below its own three-year average of 9.3 – 23% cheaper than its own history. The trailing twelve-month P/E is 10.7 and market capitalisation RUB 89.0 bn. EV/EBITDA also captures the debt, which has risen to RUB 46.8 bn.
On the portal's model the upside of the share to fair value is estimated at +41%. This is our own estimate, not a market consensus. It rests on EBITDA growth and a target multiple, so it is sensitive to whether the high margin persists.
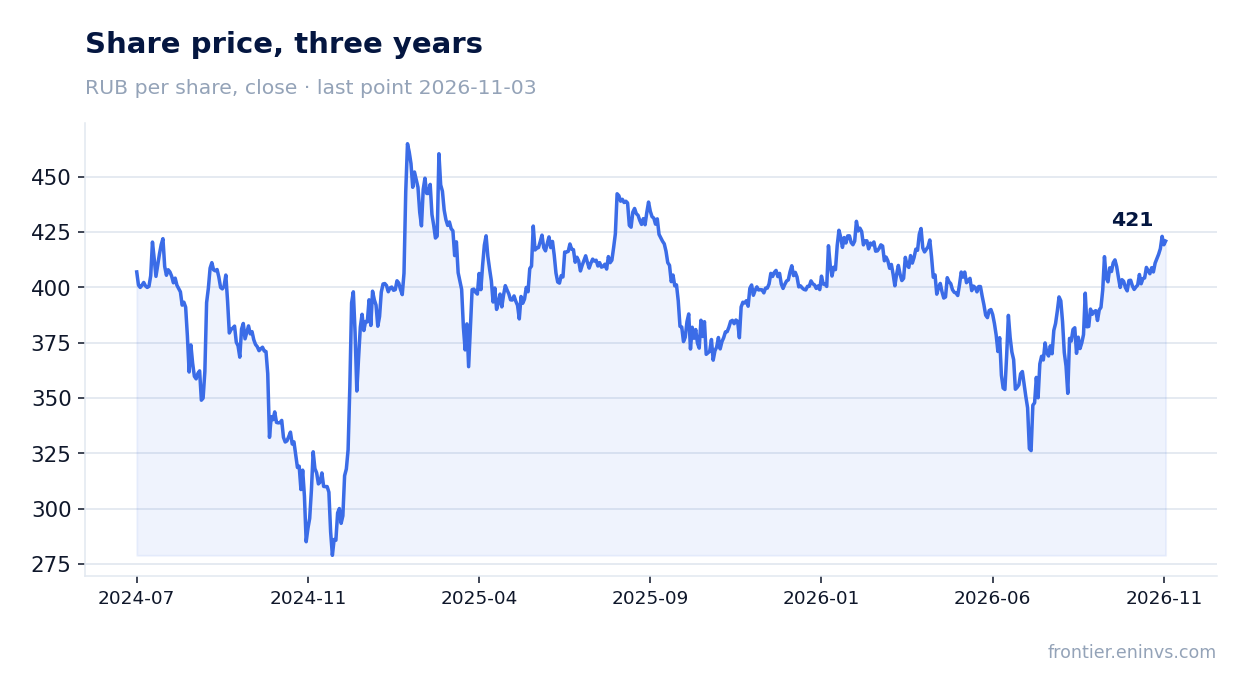
Since the report was published the share has added 11.2%, and 5.0% on the release day. The price before publication was RUB 378.65. The market reacted to the strong operating figures, but debt and negative cash flow have not yet prompted a re-rating.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 89.0 bn ₽ |
| P/E (LTM) | 10.7 |
| EV/EBITDA (LTM) | 7.2 |
| P/B | 3.34 |
| Net debt / EBITDA (LTM) | 3.01 |
| Operating cash flow (LTM) | -0.79 bn |
| ROE | 17.9% |
| Dividend yield (12m) | 1.9% |
| EV/EBITDA, 3-year average | 9.3 |
Tracked metrics of the idea
The metrics we track our idea "Promomed" of 2026-08-11 by - at the idea date and now. The share price moved +6% over the period. Original write-up: https://telegra.ph/Promomed-PRMD-Review-08-2026-08-10
Idea: at publication and now
| Metric | 2026-08-11, price 394 | Now, price 419 |
|---|---|---|
| Fundamental value created, share of market cap | +54% | +41% |
Bottom line
The strong side of the report is operational: revenue rose 75.7%, EBITDA by 88.7%, and the margin reached 34.2%. But profit is partly owed to a one-off reserve recovery of RUB 859.6 mln, and cash does not stay in the business: operating cash flow for the quarter was negative, inventories rose to RUB 16,302.2 mln, and net debt to RUB 46.8 bn at 3.01 times EBITDA. A dividend yielding 1.9% does not offset these risks. The key question for a holder is whether the company can turn revenue growth into sustained cash flow and stop debt growth. At an EV/EBITDA of 7.2 against its own average of 9.3 the share looks cheaper than its own history, and the verdict is 'rather attractive'.
Open the company's financial profile PRMD →
See also: market overview · valuation map · stock screeners