Rostelecom: double-digit revenue growth, yet free cash flow remains under pressure
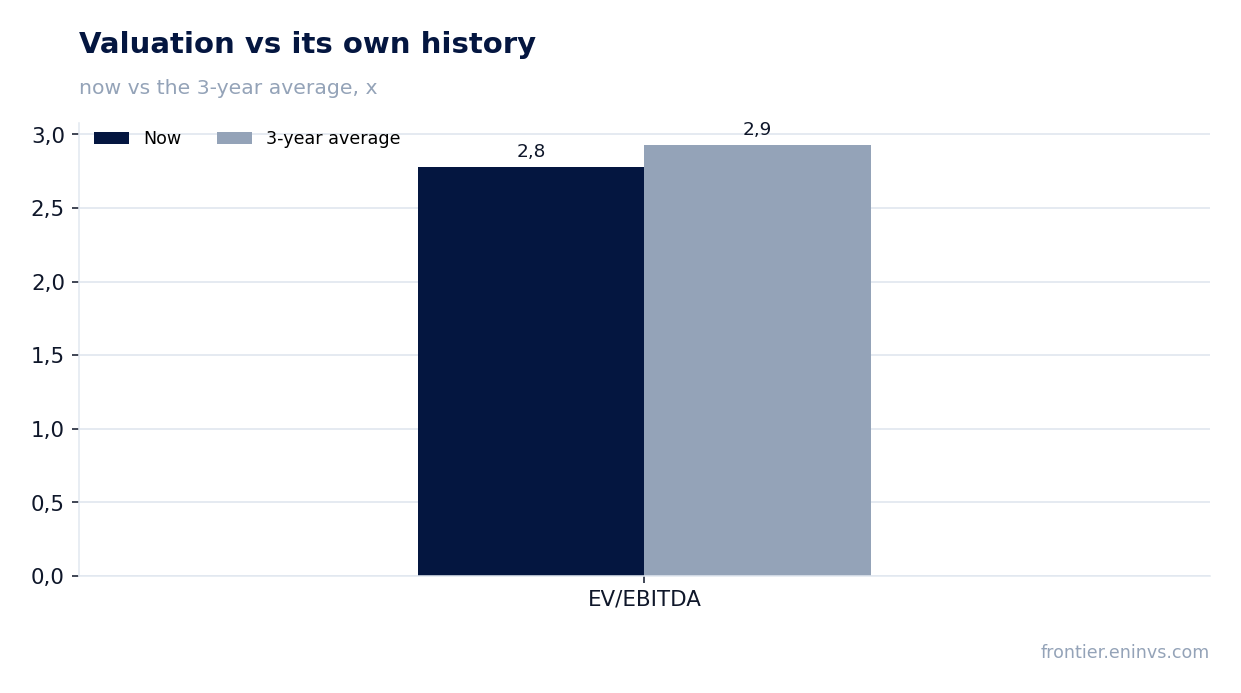
On August 12, Rostelecom reported Q2 2026 results: revenue grew 11.4% YoY to RUB 226.8 bn, EBITDA rose 8.4% to RUB 86.4 bn, and net profit increased 8.8% to RUB 6.6 bn. However, operating cash flow for the half-year remained negative, and capex plus dividends continue to exceed cash generation. At the current price, the share looks attractive: EV/EBITDA of 2.76 is below its own three-year average of 2.93, and the dividend yield of 6.45% is close to fair, but free cash flow and rising debt warrant caution.
Key takeaways
— Q2 revenue grew 11.4% to RUB 226.8 bn, accelerating from the previous quarter
— EBITDA rose 8.4%, but margin declined from 39.2% to 38.1% due to higher cost of sales
— Net profit increased 8.8%, yet margin remains thin at 2.9%
— Operating cash flow for the half-year is negative at minus RUB 32.8 bn, with capex exceeding OCF
— Debt rose RUB 19.0 bn in the quarter and RUB 34.8 bn over 12 months; debt/EBITDA stands at 2.26
— Dividends for 2025 were RUB 2.71 per share, yield 6.45%, but payouts exceed free cash flow
— EV/EBITDA multiple is 2.76, below the three-year average of 2.93; upside per the portal's model is 37%
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 203 | 227 | +11.4% |
| EBITDA | 79.8 | 86.4 | +8.4% |
| Operating profit | 37.1 | 38.4 | +3.5% |
| Net profit | 6.05 | 6.58 | +8.8% |
| Operating cash flow | 22.5 | 22.7 | +1.3% |
| Capex | 30.7 | 32.3 | +5.0% |
| EBITDA margin | 39.2% | 38.1% | -1.1 pp |
| Net margin | 3.0% | 2.9% | -0.1 pp |
Q2 revenue grew 11.4% to RUB 226.8 bn, accelerating from the previous quarter
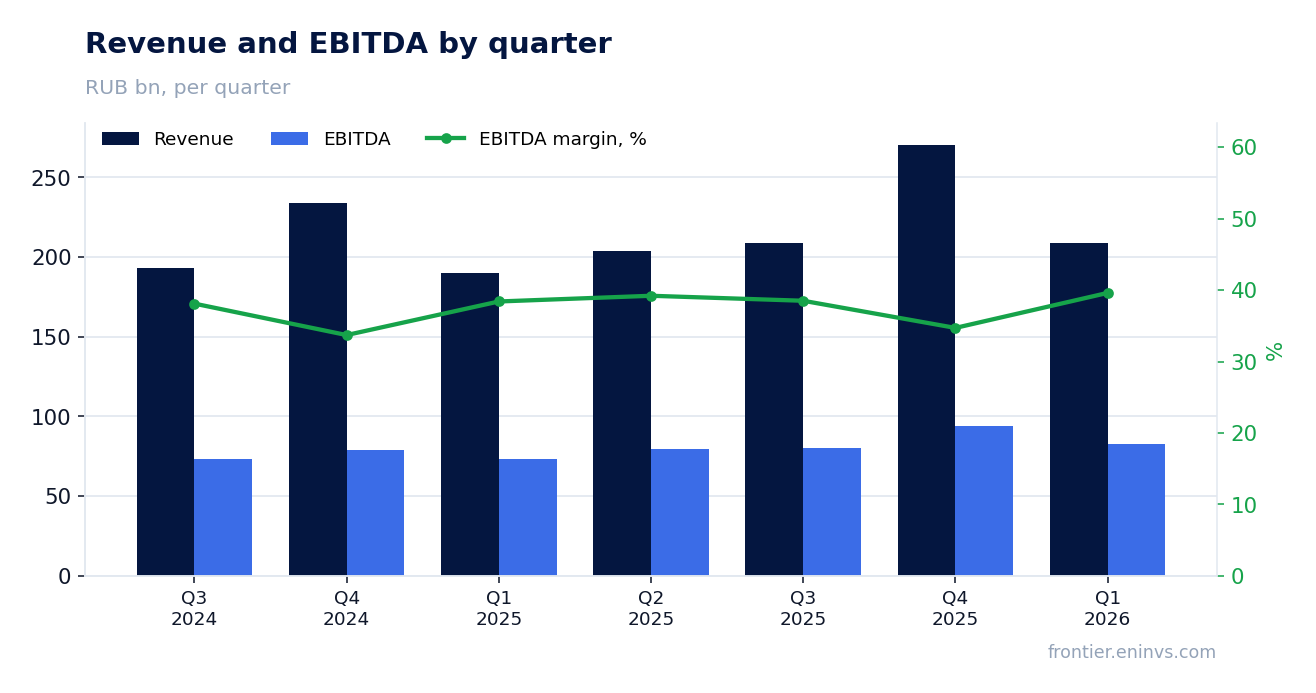
In Q2 2026, Rostelecom's revenue reached RUB 226.8 bn, up 11.4% year-on-year. This is an acceleration from Q1, when growth was 9.9%. Sequential dynamics are also positive: revenue rose from RUB 208.9 bn in Q1 to RUB 226.8 bn in Q2.
For H1 2026, revenue amounted to RUB 238.7 bn per the financial statements (income statement for 6 months), up 6.8% from the same period last year. The main driver remains growth in telecom and IT services, though segment details are not provided in the press release.
EBITDA rose 8.4%, but margin declined from 39.2% to 38.1% due to higher cost of sales
EBITDA in Q2 2026 grew 8.4% YoY to RUB 86.4 bn, yet the margin declined from 39.2% to 38.1%. This implies cost of sales is growing faster than revenue: in the half-year report, cost of sales rose 6.9% to RUB 237.7 bn, while revenue grew 6.8%.
The margin contraction signals pressure on operational efficiency. The company does not disclose cost structure in the press release, but one might assume growth is tied to personnel and energy costs, typical for telecom operators in the current environment.
Net profit increased 8.8%, yet margin remains thin at 2.9%
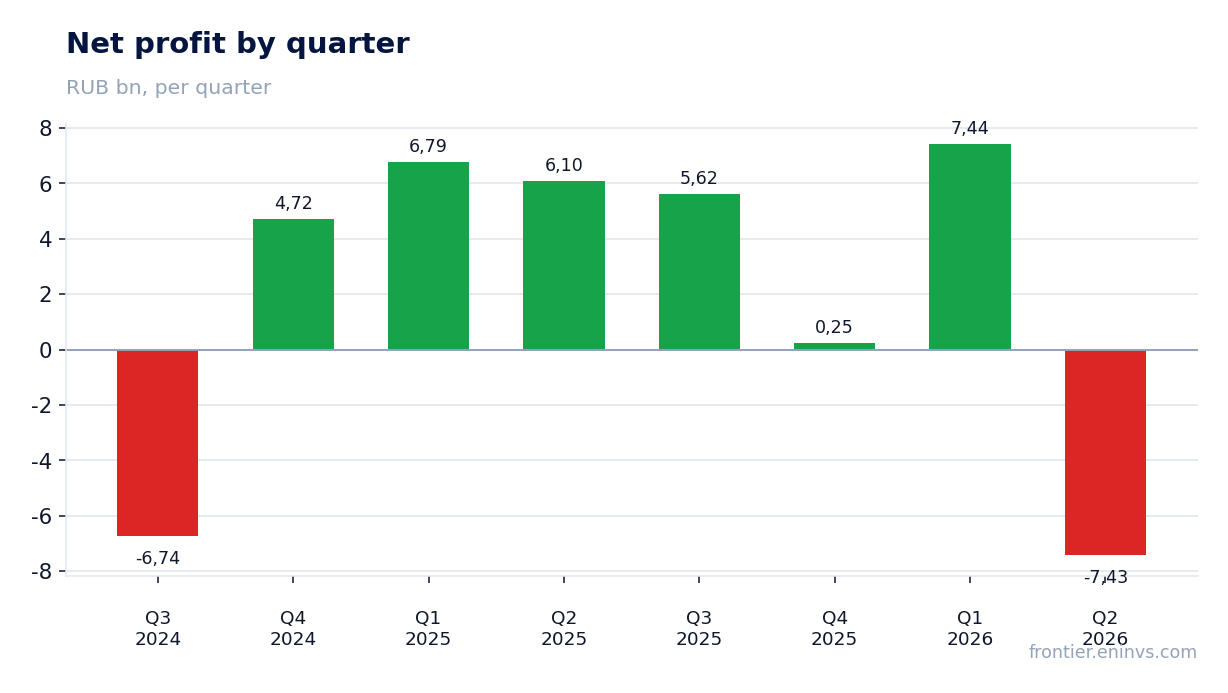
Net profit in Q2 2026 was RUB 6.6 bn, up 8.8% YoY. However, net margin remains thin at 2.9% versus 3.0% a year earlier. For the half-year, the company actually posted a net loss of RUB 9.6 bn per the income statement, driven by high interest expenses and other items.
The low net profit is explained by significant financial costs: interest payable for the half-year reached RUB 52.0 bn, up 3.8% from a year earlier. Other income partially offsets but does not cover the interest burden.
Operating cash flow for the half-year is negative at minus RUB 32.8 bn, with capex exceeding OCF
Per the cash flow statement, operating cash flow for H1 2026 was minus RUB 32.8 bn versus minus RUB 17.1 bn in the same period last year. This means operating activities do not generate enough cash to cover current liabilities, let alone capital expenditures.
Capital expenditures for the half-year were RUB 24.2 bn (payments for acquisition of non-current assets), lower than in H1 2025 (RUB 25.0 bn). Nevertheless, even with lower capex, free cash flow remains deeply negative. In Q2, OCF was positive at RUB 22.7 bn, but insufficient to offset Q1.
Debt rose RUB 19.0 bn in the quarter and RUB 34.8 bn over 12 months; debt/EBITDA stands at 2.26
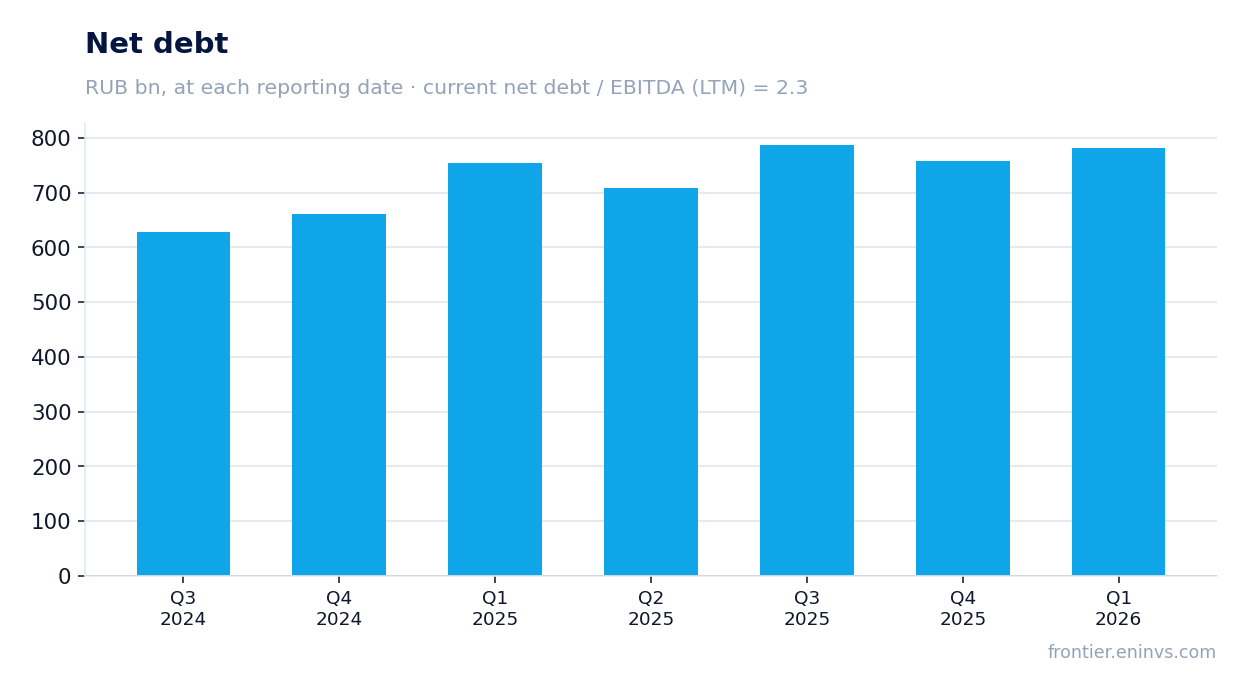
Rostelecom's net debt at the end of Q2 2026 was RUB 801.1 bn, up RUB 19.0 bn from the previous reporting date and RUB 34.8 bn over the trailing 12 months. The net debt/EBITDA ratio for the LTM stands at 2.26.
The debt increase finances the cash flow deficit and dividend payments. The cash flow statement shows active borrowing: proceeds from loans and borrowings for the half-year were RUB 28.8 bn, from bond issuance RUB 120.1 bn, while repayments were RUB 119.9 bn.
Dividends for 2025 were RUB 2.71 per share, yield 6.45%, but payouts exceed free cash flow
In June 2026, shareholders approved dividends for 2025 of RUB 2.71 per ordinary and preferred share. Total payouts were RUB 9.5 bn, as reflected in the statement of changes in equity. The trailing dividend yield is 6.45%.
However, these payouts exceed the company's free cash flow: over the LTM, operating cash flow was RUB 162.5 bn, but after capital expenditures (totaling about RUB 144.9 bn over four quarters), free flow is thin, and after interest payments it turns negative. Our model estimates the next dividend at RUB 3.46 per share, implying a forward yield of 8.5% versus our fair yield of 7.0%.
EV/EBITDA multiple is 2.76, below the three-year average of 2.93; upside per the portal's model is 37%
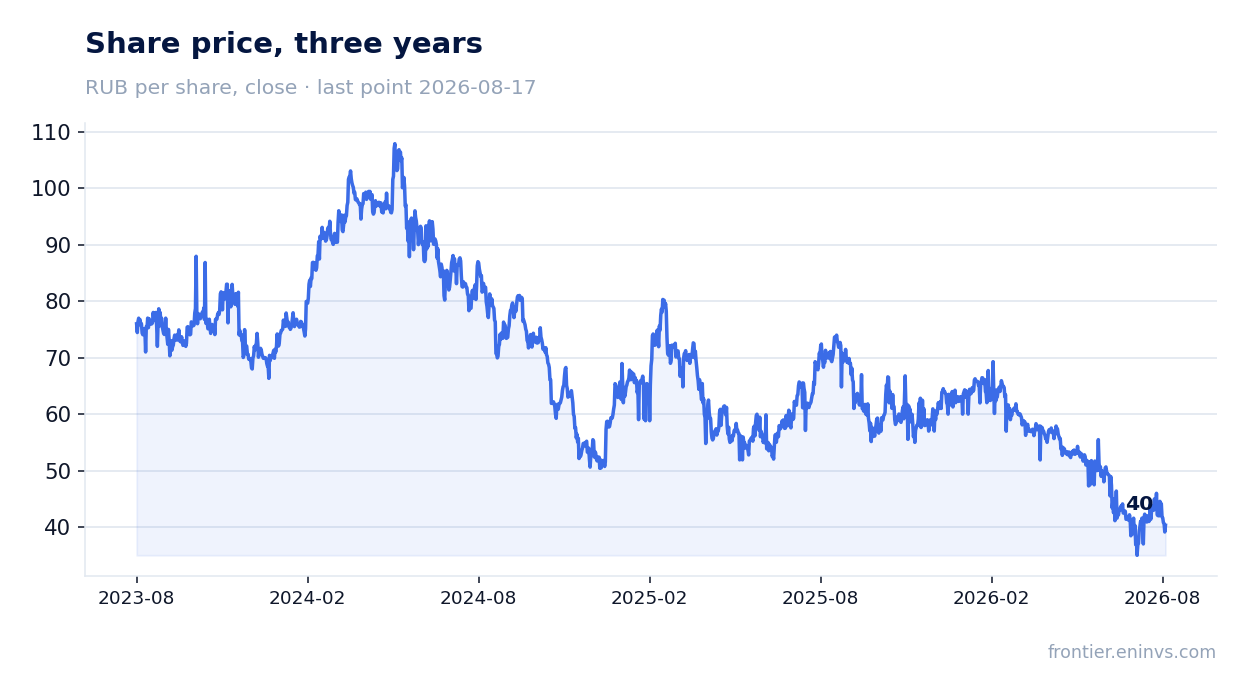
At the current share price of RUB 44.57 (before the release) and after a 9.5% decline since the announcement, the market capitalization is RUB 145.5 bn. The EV/EBITDA multiple for the LTM is 2.76, below its own three-year average of 2.93. P/E LTM is 7.31, ROE is 9.3%.
According to the portal's model, the upside to fair value is +37%. The share is held in our live model strategies on the portal, 'Growth-potential (quality)', reflecting its fit with investment criteria, but this is not an argument for the verdict.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 146 bn ₽ |
| P/E (LTM) | 7.3 |
| EV/EBITDA (LTM) | 2.8 |
| P/B | 0.53 |
| Net debt / EBITDA (LTM) | 2.26 |
| Operating cash flow (LTM) | 162 bn |
| ROE | 9.3% |
| Dividend yield (12m) | 6.5% |
| EV/EBITDA, 3-year average | 2.9 |
Bottom line
Rostelecom demonstrates solid revenue growth of 11.4% in Q2, confirming sustained demand for telecom services. However, operational efficiency is deteriorating: EBITDA margin declined, and operating cash flow for the half-year remains negative. The company finances capex and dividends through debt, which rose to RUB 801.1 bn, but the debt/EBITDA ratio of 2.26 remains moderate. At the current price, the share trades at a discount to its own history (EV/EBITDA 2.76 vs. average 2.93), and the dividend yield of 6.45% is close to fair. The key question for holders is whether the company can restore positive free cash flow without harming its investment program. Verdict: the share is attractive, but with caveats related to cash flow.
Open the company's financial profile RTKM →
See also: market overview · valuation map · stock screeners