Gazprom Neft: profit tripled, but half the quarter came from a weak rouble
28 августа «Газпром нефть» раскрыла результаты за второй квартал 2026 года. Выручка выросла на 15,6% год к году, до 1 022,2 млрд руб., EBITDA – на 75,3%, до 357,7 млрд руб., чистая прибыль – на 182,5%, до 195,1 млрд руб. Рентабельность по EBITDA поднялась до 35,0% против 23,1% годом ранее, но заметная часть этого роста – курсовые разницы и низкая база прошлого года, а не устойчивое улучшение. При цене 481,1 руб. бумага торгуется ниже своей истории по мультипликаторам и даёт 8,1% дивидендной доходности, поэтому при всей разовости квартала акция выглядит скорее привлекательной.
Key takeaways
— Revenue accelerated to +15.6% after −3.7% a quarter earlier, the first growth in five quarters
— EBITDA margin of 35.0% versus 23.1% a year earlier – the gain came from both the rouble and a low base
— Net profit of RUB 195.1 bn includes RUB 7.7 bn of FX gains and RUB 14.8 bn from associates
— Debt rose to RUB 1,889.0 bn at 2.63x LTM EBITDA
— Operating cash flow of RUB 170.2 bn against capex of RUB 109.8 bn – free cash is positive but modest
— H1 2026 dividend recommended at RUB 42.51 per share, while our full-year estimate is RUB 66.75
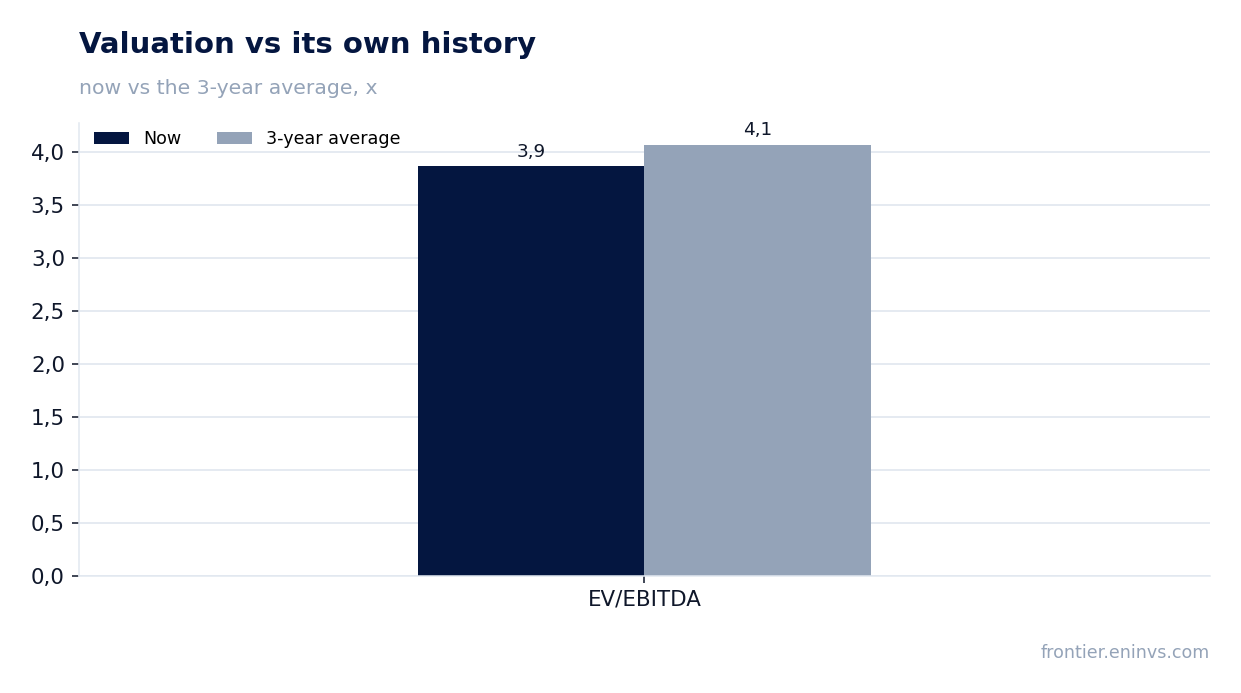
— EV/EBITDA of 4.12 versus the three-year average of 4.07 – the market values the company slightly above its own history
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 884 | 1 022 | +15.6% |
| EBITDA | 204 | 358 | +75.3% |
| Operating profit | 92.0 | 242 | +163.0% |
| Net profit | 69.1 | 195 | +182.5% |
| Operating cash flow | 149 | 170 | +14.0% |
| Capex | 93.9 | 110 | +16.9% |
| EBITDA margin | 23.1% | 35.0% | +11.9 pp |
| Net margin | 7.8% | 19.1% | +11.3 pp |
Revenue accelerated to +15.6% after −3.7% a quarter earlier, the first growth in five quarters
In Q2 2026 revenue reached RUB 1,022.2 bn, up 15.6% year on year. This is a reversal after four quarters of decline: in Q1 2026 the drop was 3.7%, in Q4 2025 – 13.1%. The acceleration relative to Q1 is the sharpest in two years.
The main contribution came from sales of oil, gas and petroleum products – RUB 974.0 bn of total revenue. Other revenue fell to RUB 48.2 bn from RUB 56.1 bn a year earlier, but its share is small. Growth in the oil segment was driven by both volumes and prices: the weak rouble (77.75 per dollar at end-June versus 78.23 at end-2025) supported rouble revenue.
Compared with Q1 2026 (RUB 857.9 bn), the sequential increase is 19.1%. This is a strong signal, but it is partly explained by seasonal recovery after a low first quarter. The sustainability of the trend will be visible in Q3, when the base effect becomes less favourable.
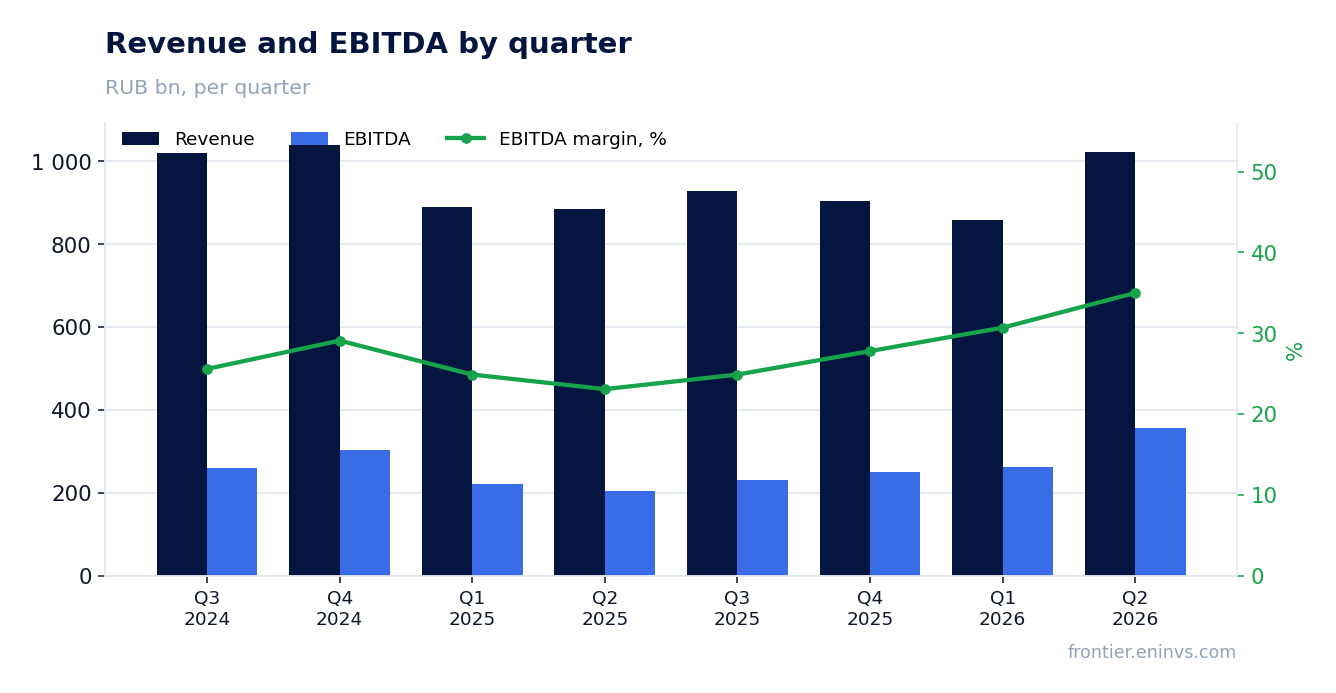
EBITDA margin of 35.0% versus 23.1% a year earlier – the gain came from both the rouble and a low base
EBITDA in Q2 2026 was RUB 357.7 bn, up 75.3% year on year. The EBITDA margin rose to 35.0% from 23.1% in Q2 2025. This is the highest margin growth in several years.
Part of the improvement is due to FX gains: within other income, FX profit was RUB 7.7 bn versus RUB 14.7 bn a year earlier, but a year ago a significant portion of FX profit (RUB 17.2 bn) was in financial activities, while this quarter it was RUB 11.6 bn. Financial income of RUB 12.8 bn and share of profit from associates of RUB 14.8 bn (versus a loss of RUB 0.8 bn a year earlier) also helped.
Operating profit rose to RUB 241.9 bn from RUB 92.0 bn a year earlier. The low-base effect is particularly visible here: in Q2 2025 the company incurred significant costs, including a rise in the cost of purchased oil and petroleum products (RUB 186.5 bn versus RUB 160.3 bn in the current quarter). The reduction in this expense line by RUB 26.1 bn directly supported the margin.
The sustainability of a 35% margin is questionable: excluding FX gains and one-offs, it would be closer to 30%. Another quarter with similar dynamics is needed to confirm the trend.
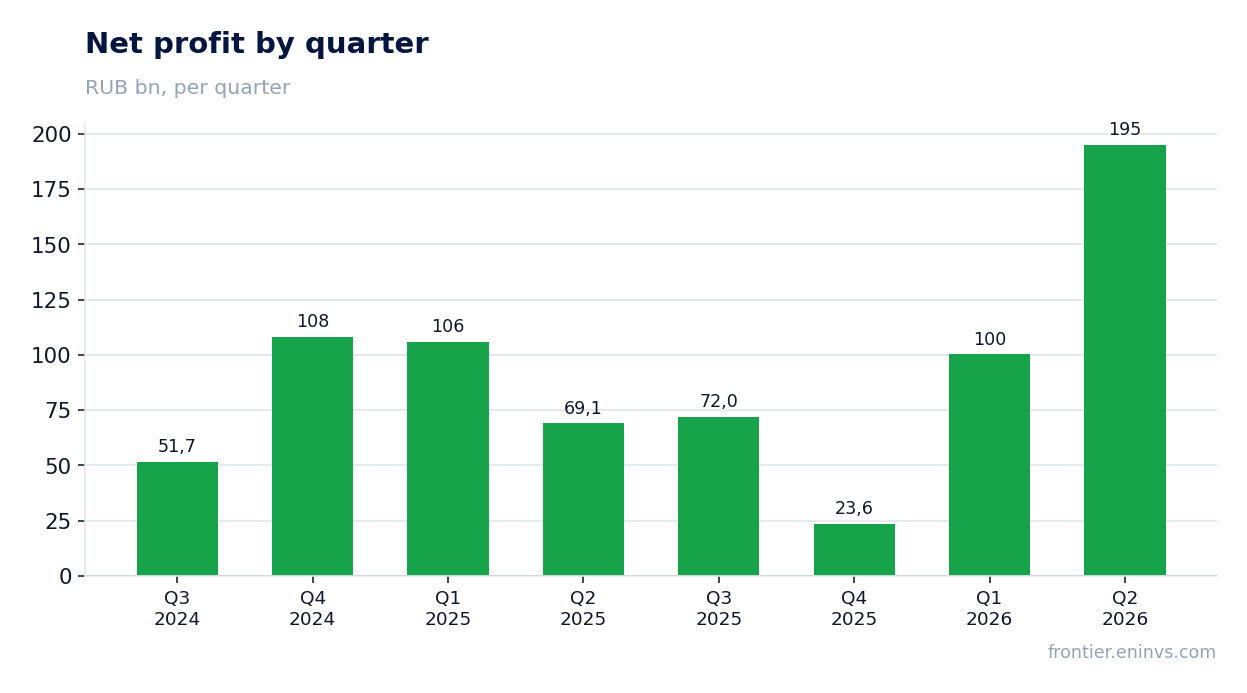
Net profit of RUB 195.1 bn includes RUB 7.7 bn of FX gains and RUB 14.8 bn from associates
Net profit in Q2 2026 was RUB 195.1 bn, up 182.5% year on year. This is the highest quarterly figure in recent years. However, the profit includes one-off and non-operating items.
FX differences contributed RUB 7.7 bn of profit, versus RUB 14.7 bn a year earlier. The share of profit from associates and joint ventures was RUB 14.8 bn versus a loss of RUB 0.8 bn a year earlier. Financial income exceeded expenses by RUB 2.4 bn (RUB 12.8 bn versus RUB 15.2 bn).
Without these items, profit would have been lower by about RUB 25 bn, but still significantly above last year's level. The main driver is operational efficiency and lower costs for purchased oil and petroleum products. Net margin rose to 19.1% from 7.8% a year earlier.
Earnings per share were RUB 40.34 versus RUB 13.88 a year earlier. This matters for the dividend base: the company traditionally pays out a significant portion of profit.
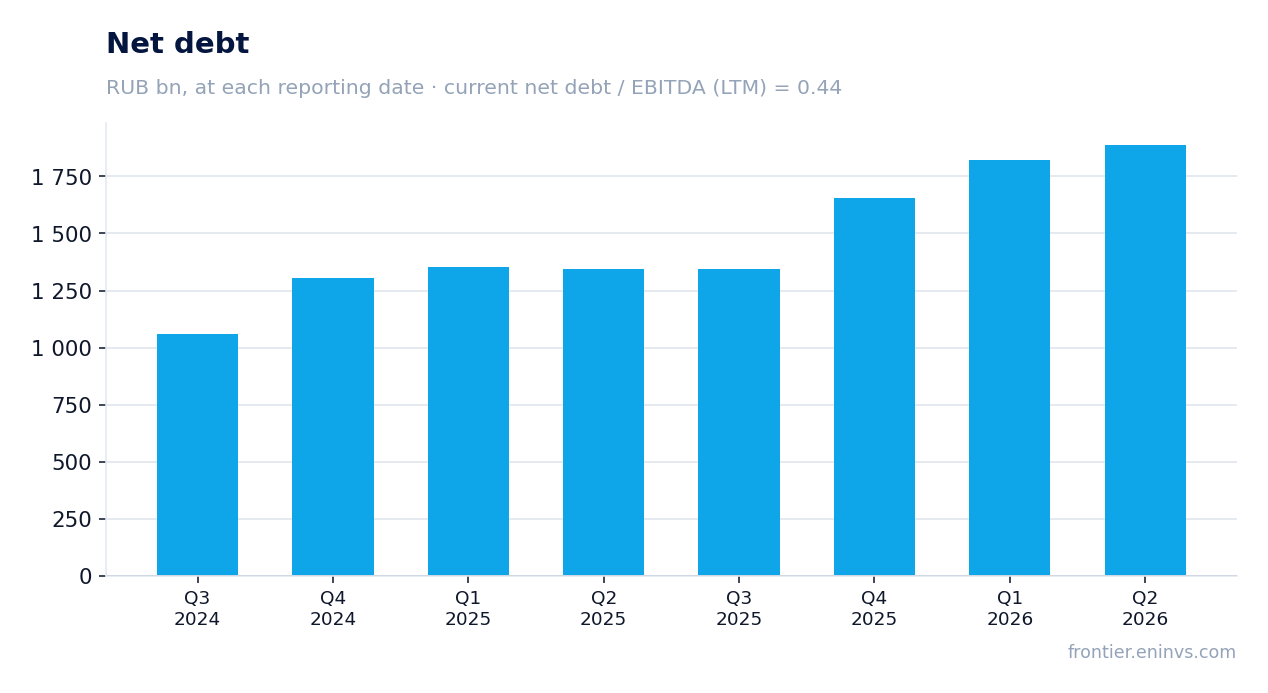
Debt rose to RUB 1,889.0 bn at 2.63x LTM EBITDA
Net debt as of 30 June 2026 was RUB 1,889.0 bn, up from RUB 1,820.9 bn on 31 March 2026 (+RUB 68.1 bn). Over 12 months debt increased significantly: from RUB 1,346.0 bn on 30 June 2025 (+RUB 543.0 bn).
The net debt to LTM EBITDA ratio is 2.63. This is a moderate level for an oil company, but higher than a year ago. The debt increase is linked to the investment programme and dividend payments. The company retains access to credit, as evidenced by cash growth to RUB 435.4 bn at end-June from RUB 182.9 bn at the start of the year.
Interest expenses remain under control: financial expenses in Q2 were RUB 15.2 bn versus RUB 20.6 bn a year earlier. With the key rate at 14.0%, debt servicing costs will remain significant, but the company generates sufficient operating cash flow to cover interest.
Further debt growth is limited: if current oil prices and the rouble exchange rate hold, the company can finance capex and dividends without a sharp increase in borrowing.
Operating cash flow of RUB 170.2 bn against capex of RUB 109.8 bn – free cash is positive but modest
Operating cash flow in Q2 2026 was RUB 170.2 bn, up 14.0% from RUB 149.3 bn a year earlier. However, compared with Q1 2026 (RUB 123.0 bn), the increase is noticeable. For H1 2026 operating cash flow reached RUB 293.2 bn versus RUB 249.4 bn a year earlier.
Capital expenditures in Q2 were RUB 109.8 bn, down from RUB 127.9 bn in Q1 2026 but above the Q2 2025 level of RUB 93.9 bn. For H1 capex reached RUB 242.5 bn, up 9.2% year on year. The company continues to invest in projects, including refinery upgrades and field development.
Free cash flow (operating cash flow minus capex) in Q2 was RUB 60.4 bn. This is positive but does not fully cover dividend payments. For H1 free cash flow was RUB 50.7 bn, significantly below what is required for the declared dividends.
The company finances the shortfall through borrowing, which explains the debt increase. If current oil prices and the rouble exchange rate hold, free cash flow may rise in H2, but for now it remains modest.
H1 2026 dividend recommended at RUB 42.51 per share, while our full-year estimate is RUB 66.75
The board recommended a dividend for H1 2026 of RUB 42.51 per share. This is an interim payment subject to shareholder approval. Over the last 12 months the company paid RUB 45.41 per share, giving a current dividend yield of 8.1%.
Our estimate for the full-year dividend (to be paid next year) is RUB 66.75 per share. This is our own forecast, based on LTM profit of RUB 376.8 bn and a payout ratio of 84% of profit, as last year. At the current price this implies a 11.9% yield. The board decides.
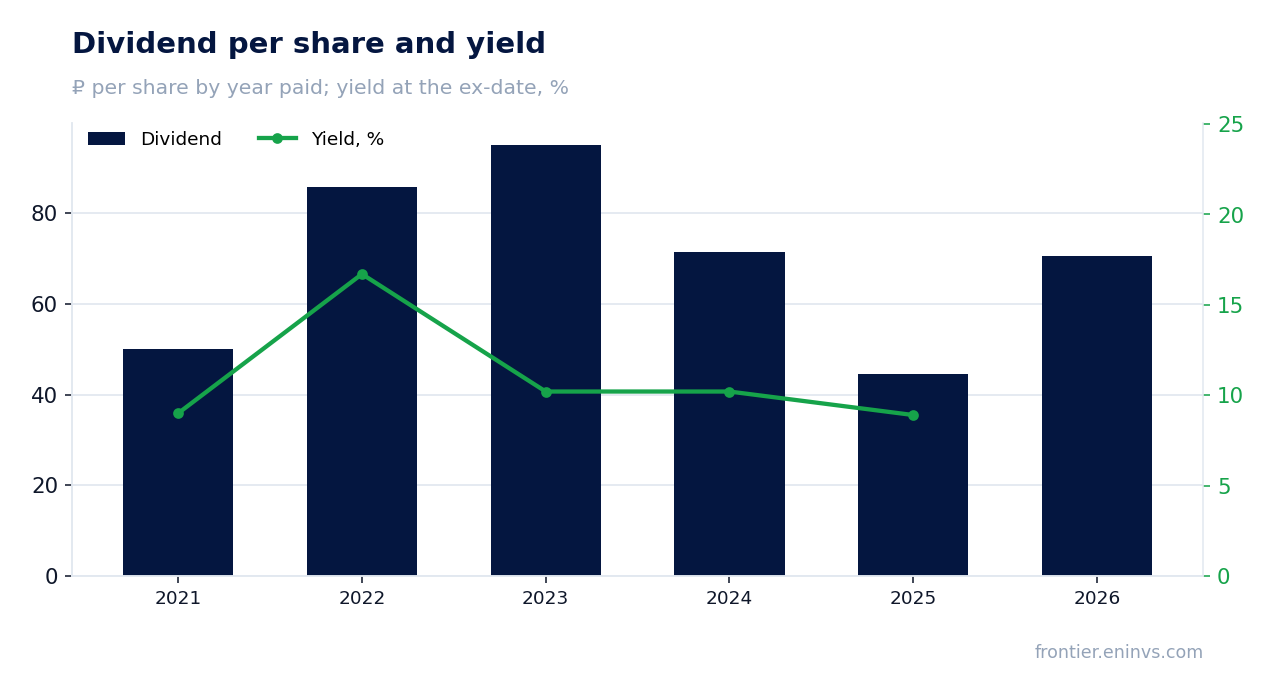
Dividend history shows volatility: RUB 50.0 per share in 2021, RUB 85.78 in 2022, RUB 95.1 in 2023, RUB 71.45 in 2024, RUB 44.51 in 2025, RUB 70.62 in 2026. The yield at the ex-date ranged from 8.9% to 16.7%. The current yield of 8.1% is below the average of recent years.
With the key rate at 14.0%, a dividend yield of 8.1% looks modest, but with our forecast of 11.9% the stock becomes attractive for income-oriented investors. The fair yield for this name, in our view, is 10.5%. The risk of a lower payout is linked to falling profits or rising capex, which already exceeds RUB 240 bn for the half-year.
EV/EBITDA of 4.12 versus the three-year average of 4.07 – the market values the company slightly above its own history
The current LTM EV/EBITDA is 4.12, slightly above the three-year average of 4.07. This means the market values the company a bit more expensive than its average over the last three years, but the difference is insignificant. LTM P/E is 7.05, which also does not look overvalued.
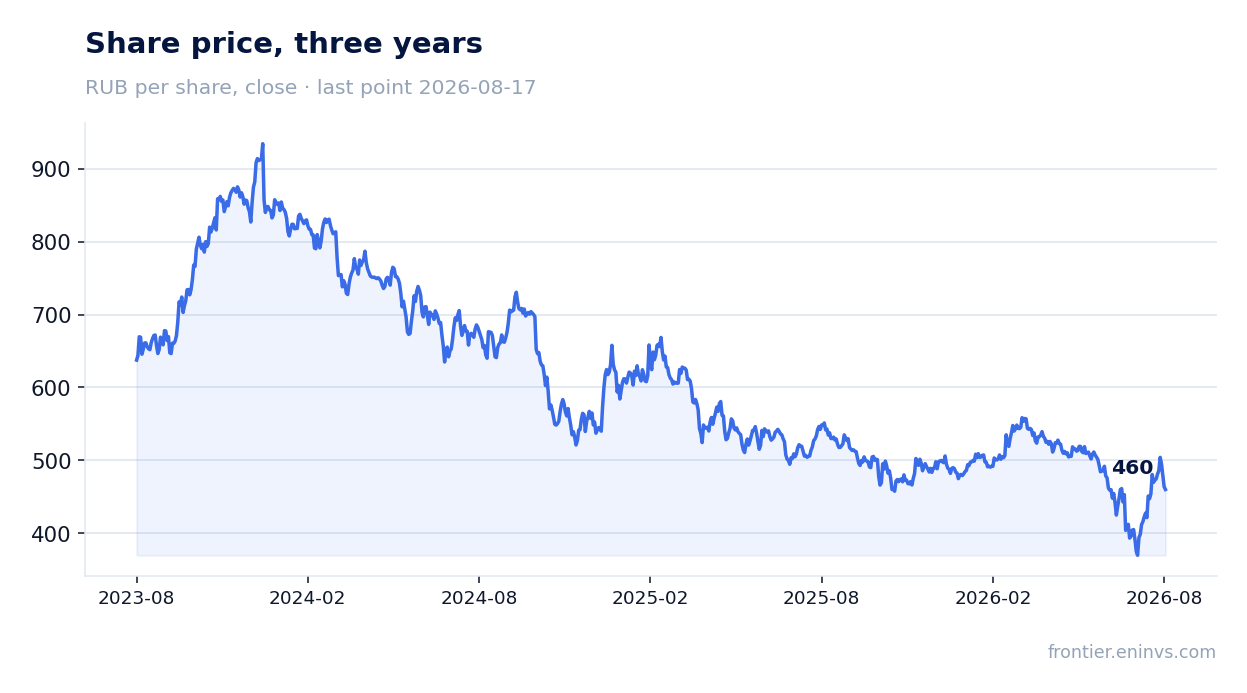
Return on equity (ROE) over the last 12 months is 23.9%, which supports the valuation. At a price of RUB 481.1, the market capitalisation is RUB 2,654.9 bn. After the report, the share rose 3.9% on the release day and 15.1% from the release to 28 September 2026.
Our model, which re-prices EBITDA at current commodity prices at the target EV/EBITDA, implies an upside to fair value of +68%. This is our own estimate, not a market consensus. It is based on the assumption that current oil and gas prices hold.
The stock is held in our live model strategies on the portal (RU Commodity-Upside), but this is a fact, not an argument for the verdict. The valuation multiples do not look stretched, and the dividend yield with our forecast exceeds the fair level.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 2 655 bn ₽ |
| P/E (LTM) | 7.0 |
| EV/EBITDA (LTM) | 4.1 |
| P/B | 0.89 |
| Net debt / EBITDA (LTM) | 2.63 |
| Operating cash flow (LTM) | 665 bn |
| ROE | 23.9% |
| Dividend yield (12m) | 8.1% |
| EV/EBITDA, 3-year average | 4.1 |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2021 | 50.00 | 9.0% |
| 2022 | 85.78 | 16.7% |
| 2023 | 95.10 | 10.2% |
| 2024 | 71.45 | 10.2% |
| 2025 | 44.51 | 8.9% |
| 2026 | 70.62 | — |
| Our estimate, current year | 66.75 | 11.9% on the current price |
Bottom line
The quarter was strong across all visible metrics: revenue accelerated to +15.6%, EBITDA rose 75.3%, net profit 182.5%. But a significant part of this growth is a consequence of the weak rouble and a low base a year earlier, not sustainable improvement. Operating cash flow of RUB 170.2 bn does not cover capex and dividends, forcing the company to increase debt. For a holder, the key question is whether the dividend yield above 10% will persist at the current price. Our full-year dividend estimate is RUB 66.75 per share, implying an 11.9% yield, and this outweighs the one-off nature of quarterly profit. The stock looks rather attractive for income-oriented investors, but requires monitoring of margin sustainability and debt load.
Open the company's financial profile SIBN →
See also: market overview · valuation map · stock screeners