Surgutneftegas preferred: a dividend model - what the pref will pay at which exchange rate
The preferred share of Surgutneftegas is a rare instrument on the Russian market: the size of its dividend is set by the charter as a formula, not by a management decision. It follows that the dividend can be calculated in advance - if you know two numbers: the company's base profit and the rouble exchange rate on 31 December. Below is a model that reproduces the actual payments of the last six years to the kopeck, scenarios for the 2026 dividend, and an estimate of the yield the share delivers "on average over the cycle".
The preferred share closed on 10 August 2026 at RUB 42.54, the ordinary share at RUB 17.08. The Bank of Russia rate for 11 August is RUB 82.61 per dollar, the key rate is 14%, and the two-year OFZ yield is 14.4%. All financial data come from the company's own disclosed RAS statements.
The pref dividend is a charter formula: 10% of RAS profit divided by 25% of the share capital
The charter defines the dividend on a preferred share as one tenth of net profit divided by the number of shares making up a quarter of the share capital. The share capital is 43,427,992,940 shares with a par value of RUB 1, of which 7,701,998,235 are preferred. A quarter of the capital is 10,856,998,235 shares. Hence the working formula:
- pref dividend, RUB = RAS net profit (RUB bn) × 0.00921
- in other words, every trillion roubles of profit gives RUB 9.21 on the pref;
- all the preferred shares together receive 7.09% of net profit - less than "10% of profit", because the divisor in the formula is larger than the number of prefs themselves;
- the "floor": the dividend on the pref cannot be lower than the dividend on the ordinary share. In loss-making years it is the floor that operates.
A check against the facts. RAS profit and the declared dividend: 2020 - RUB 729.6 bn and RUB 6.72; 2021 - RUB 513.2 bn and RUB 4.73; 2023 - RUB 1,334.1 bn and RUB 12.29; 2024 - RUB 923.3 bn and RUB 8.50. The formula matches in all cases. In 2022 profit was RUB 60.7 bn, the calculated dividend RUB 0.56, and RUB 0.80 was paid - the "floor" worked.
The RUB 0.85 payment in summer 2026 is not a dividend but a triggered "floor": the company closed 2025 with a loss
In the 2025 income statement (disclosed on 30 March 2026) almost all lines are closed with an "X" - the company uses the decree on the temporary disclosure procedure. Two lines are left open: a loss before tax of minus RUB 389.2 bn and a net loss of minus RUB 251.2 bn, against a profit of RUB 923.3 bn a year earlier.
The reason is the strengthening of the rouble: the Bank of Russia rate went through 2025 from 101.68 to 78.23 roubles per dollar. The currency revaluation of the "cash pile" turned from income into expense. Accordingly, the calculated dividend turned out negative, and shareholders received the "floor" - RUB 0.85, the same as on the ordinary shares. On 15 May 2026 the board of directors recommended allocating RUB 36.9 bn to dividends: divide by RUB 0.85 and you get exactly 43.4 bn shares, i.e. the whole share capital. Against the price on the last day to buy for the dividend (15 July 2026, RUB 37.22) this gave 2.3% - one of the worst results of the last ten years.
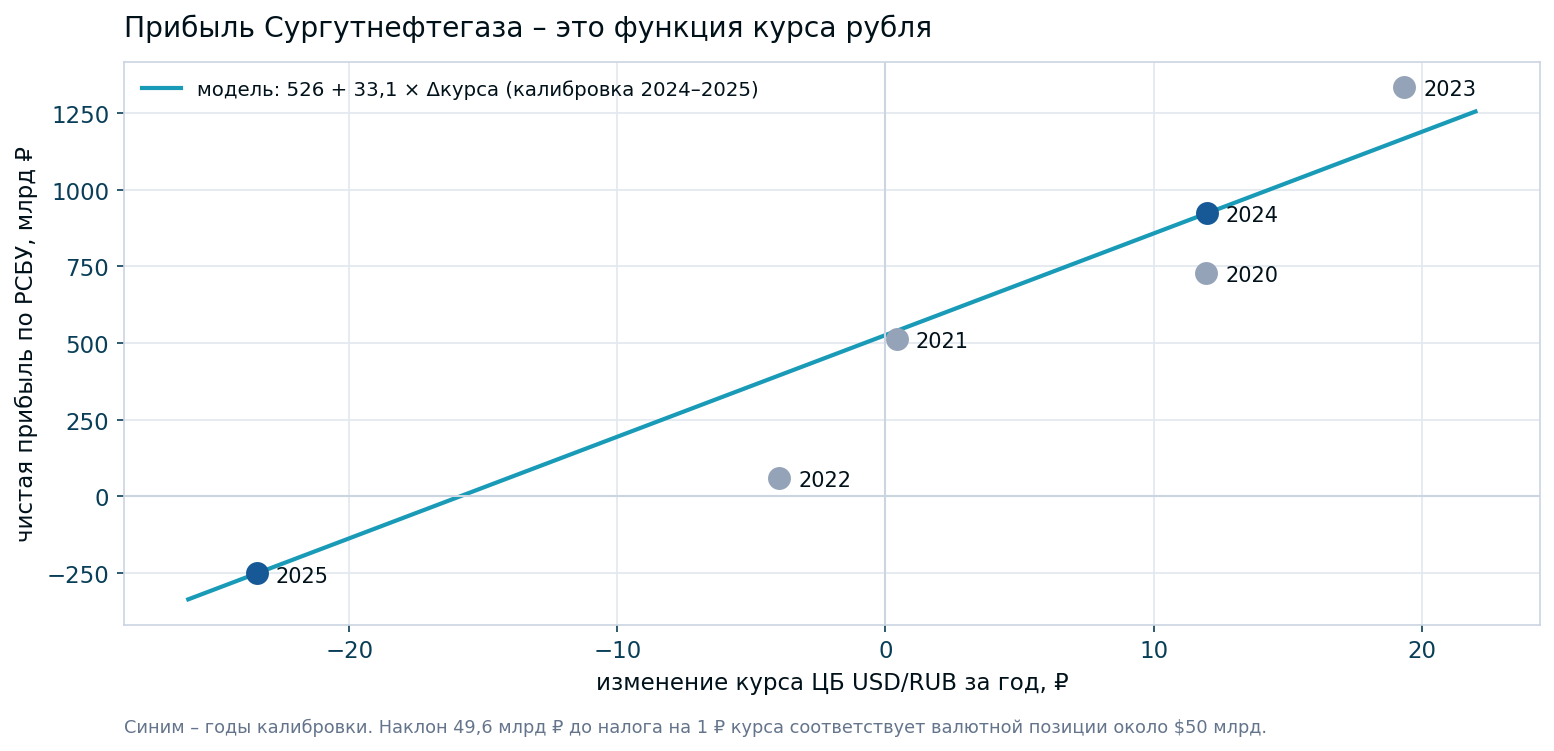
Surgutneftegas's profit is a function of the exchange rate: each rouble of depreciation gives about RUB 33 bn of net profit
Two adjacent years with opposite exchange-rate moves make it possible to split profit into two parts - one that does not depend on the rate, and one that depends on it linearly. In 2024 the dollar rose by RUB 11.99 and profit was RUB 923.3 bn. In 2025 the dollar fell by RUB 23.45 and there was a loss of RUB 251.2 bn. Two equations, two unknowns:
- net profit (RUB bn) ≈ 526 + 33.1 × annual change in the exchange rate (RUB per dollar)
- the same before tax: 774 + 49.6 × change in the exchange rate;
- the pre-tax slope has a direct physical meaning: RUB 49.6 bn per rouble of the exchange rate corresponds to a currency position of about $50 bn. The company does not disclose the currency composition of the cash pile - this is an estimate derived from the income statement, not from the notes.
The intercept of RUB 526 bn is the "core": operating profit from oil plus interest on deposits, net of tax. The model is calibrated on 2024-2025 and transfers less well to other years: for 2021 it gives RUB 540 bn against an actual 513, for 2023 RUB 1,167 bn against an actual 1,334, and for 2022 RUB 395 bn against an actual 61. The reason is clear: the core itself is not a constant, it grew with the size of the cash pile and with interest rates. That is why the scenarios below are calculated not from a single core value but from a range of RUB 400-600 bn.
The "cash pile" has been closed in the statements since 2023 but can be restored by subtraction: RUB 5.7 trn at 31.12.2025
The "Financial investments" lines (1170 and 1240) in the balance sheet have been replaced with "X" since 2023. However, the balance sheet total is disclosed, and so are all the other asset lines. The difference gives the closed lines exactly:
- 31.12.2022 - RUB 4,425 bn (≈ $63 bn), still a disclosed figure, serving as a check of the method;
- 31.12.2023 - RUB 5,777 bn (≈ $64 bn);
- 31.12.2024 - RUB 6,411 bn (≈ $63 bn) - the maximum;
- 30.06.2025 - RUB 5,509 bn;
- 31.12.2025 - RUB 5,724 bn (≈ $73 bn at the reporting-date rate).
The dollar equivalent is growing while the rouble one is almost unchanged - this is indirect evidence that part of the cash pile is no longer in foreign currency. If the currency part equals the $50 bn derived from profit, then at 31.12.2025 it is RUB 3,880 bn, and the remaining roughly RUB 1,850 bn is held in roubles at the key rate. The flows also add up: the estimated revaluation for 2025 (minus RUB 1,163 bn) plus interest and operating cash flow net of capex and dividends give exactly the size of the pile seen in the balance sheet.
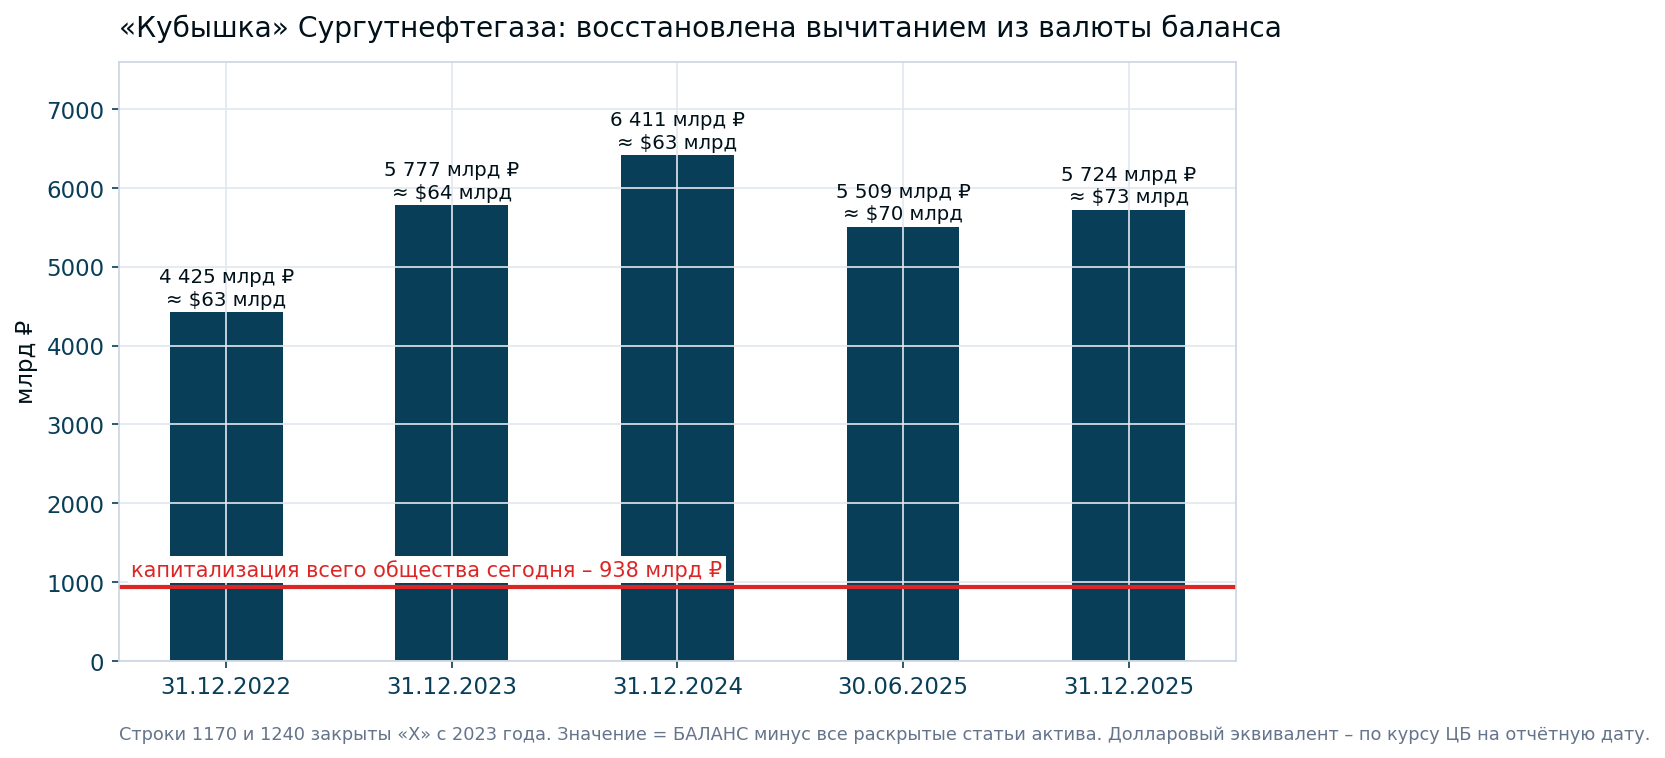
The scale is worth stating directly. The capitalisation of the whole company today is RUB 938 bn (RUB 610 bn ordinary, RUB 328 bn preferred). Liquid assets are RUB 5,724 bn, i.e. 6.1 times the capitalisation. There is RUB 131.8 of net cash per share against a pref price of RUB 42.54. Equity in the balance sheet is RUB 7,942 bn, so the company trades at 0.12 of its book value.
An important caveat on data freshness: the company has not disclosed interim statements for 2026. A year earlier the first-quarter report appeared on 6 June and the half-year report on 29 August. By comparison, LUKOIL, Tatneft, Gazprom Neft and Transneft disclosed their 1H2026 RAS statements at the end of July. So the freshest data point for Surgut today is 31 December 2025.
The cash pile behaves like a dollar one, not a yuan one: the yuan version requires 110% of the entire pile
A common version holds that after 2022 Surgut moved its cash pile into yuan. It can be tested in the same way as the size of the currency position: substitute the yuan rate instead of the dollar rate into the two equations.
- if the position is in dollars - the 2024 and 2025 profits imply $49.6 bn, i.e. RUB 3,881 bn at the 31.12.2025 rate;
- if in yuan - CNY 563.8 bn, i.e. RUB 6,291 bn;
- but the entire pile at 31.12.2025 per the audited balance sheet is RUB 5,724 bn. The yuan version requires 110% of it, which is physically impossible.
The reason is simple: in both years the yuan moved against the rouble about half as much as the dollar (in 2025 minus 16.9% against minus 23.1%). To explain the 2025 loss and the 2024 profit by yuan revaluation, you need twice as many yuan as fit in the balance sheet. These data cannot separate a "dollar plus yuan" mix more precisely - the two rates move almost in parallel - but the conclusion about the dominant currency is robust: it is not the yuan. The practical consequence for the investor: watch the dollar rate, not the yuan.
At 84-85 roubles at year-end the pref pays about RUB 6.5 - 15% of the current price
Next comes simple arithmetic. The dividend for 2026 will be declared in May 2027, with the record date in mid-July 2027. We calculate with a core of RUB 500 bn (the range of RUB 400-600 bn in brackets):
- rate 70 - dividend RUB 2.09 (1.17-3.02), yield 4.9%
- rate 78.23, i.e. unchanged over the year - RUB 4.61 (3.69-5.53), 10.8%
- rate 82.61, i.e. as today - RUB 5.94 (5.02-6.86), 14.0%
- rate 84.37 - what the Si-12.26 futures price in - RUB 6.48 (5.56-7.40), 15.2%
- rate 90 - RUB 8.20 (7.28-9.12), 19.3%
- rate 100 - RUB 11.25 (10.33-12.17), 26.4%
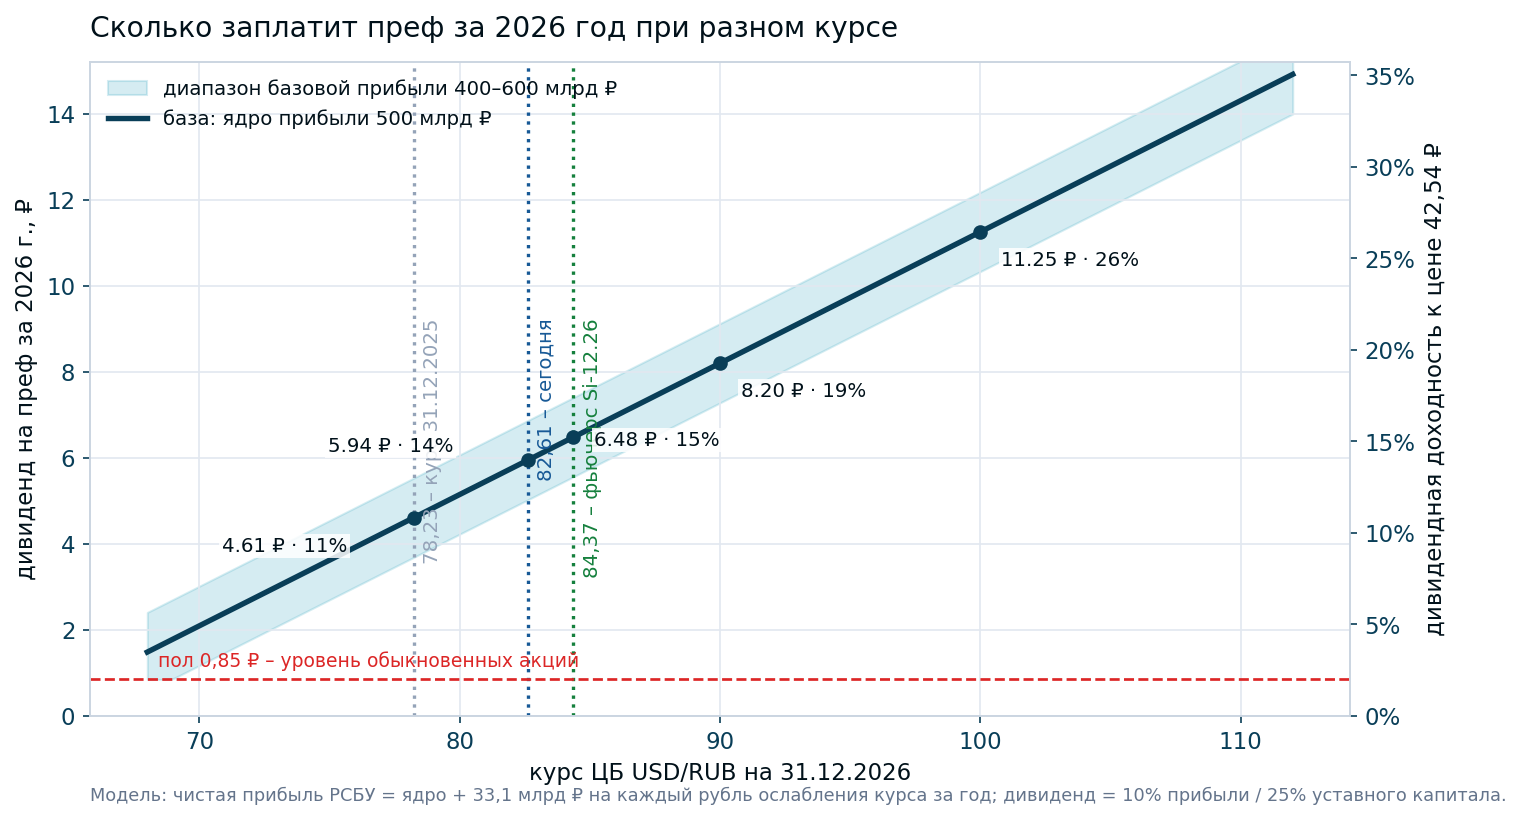
Three numbers from this table matter more than the rest. First: the rouble may not move at all - and the pref still pays about 11%, because the profit core has not gone anywhere. Second: for the dividend to fall back to the RUB 0.85 "floor", the rouble would have to strengthen to roughly 66-69 per dollar - levels not seen since mid-2022. Third: to repeat the 2024 record (RUB 12.29), the dollar must end the year at around 100-106.
Separately, a reference from the market rather than from an analyst. Dollar futures on the Moscow Exchange trade in contango: Si-12.26 at 84.37, Si-12.27 at 93.50. This is not a forecast but a forward price that embeds the rate differential (14% in roubles against about 4% in dollars). But if the exchange rate simply follows this curve, the pref would pay about RUB 6.5 for 2026 and about RUB 7.4 for 2027 - 15% and 17% of today's price. The logic here is circular: either the rouble weakens as the curve implies and currency revaluation works, or it does not weaken - but then the rouble part of the cash pile keeps earning a high rate.
The normalised yield of the pref is 13-16%, the historical median is 14.5%
A "normalised" dividend can be estimated in three independent ways, and they give a close answer.
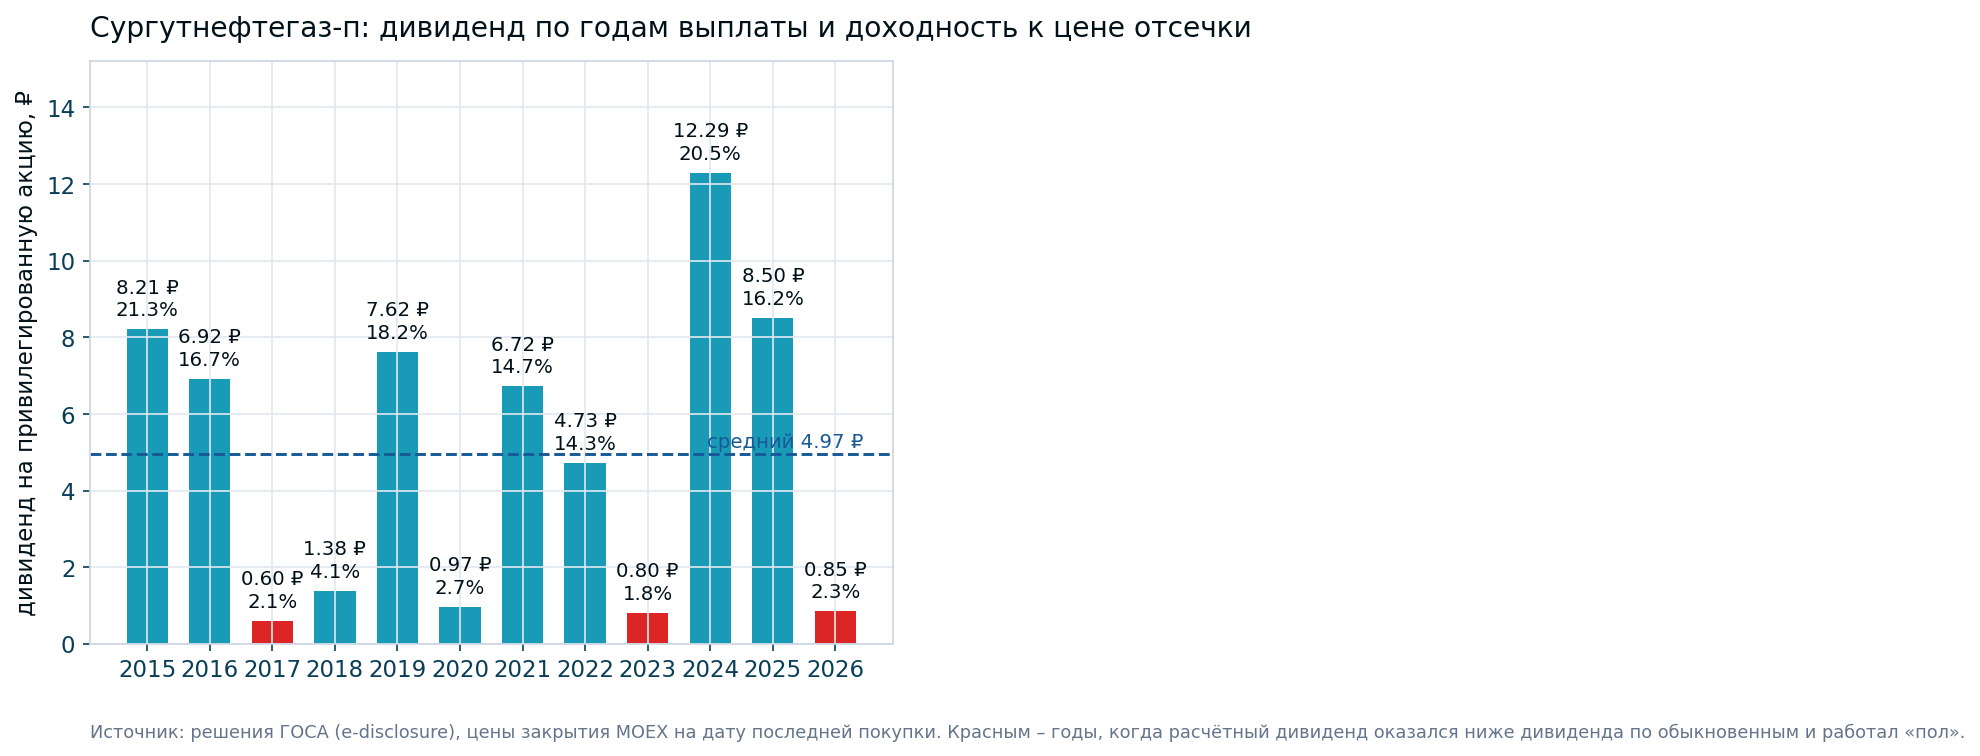
- By actual payments. Over 12 years (payments of 2015-2026) the average dividend is RUB 4.97 and the median RUB 5.72. Against today's price of RUB 42.54 that is 11.7% and 13.5%.
- By historical yield. Yield to the record-date price by year: 21.3%, 16.7%, 2.1%, 4.1%, 18.2%, 2.7%, 14.7%, 14.3%, 1.8%, 20.5%, 16.2%, 2.3%. The average is 11.2%, the median 14.5%.
- By the model. A core of RUB 500 bn plus currency revaluation under long-term rouble depreciation: 3% a year gives RUB 5.32 (12.5%), 5% a year RUB 5.80 (13.6%), 7% a year RUB 6.28 (14.8%).
Note the shape of the distribution: the pref's yield is not "average" but bimodal. In nine years out of twelve it is either 14-21% or 1.8-4.1%. There are almost no intermediate values - because the exchange rate either moved or the "floor" worked. This share does not suit an investor counting on a steady stream; for an investor holding it as insurance against rouble depreciation, it is the opposite.
A normalised yield of 14-15% means zero premium to OFZ, but a completely different risk profile
The pref should be compared not with other dividend shares but with the risk-free rate - because its whole point is the cash pile. Two-year OFZs yield 14.4%, ten-year ones 15.7%, and the key rate is 14%. The normalised 13-16% on the pref is effectively the same yield.
Against the equity market the picture is different. In our database of dividends covering 110 tracked Russian securities, 39 made a payment in 2026; the median yield among them is 6.3%, and only ten are above 13%. So the normalised 13-16% on the pref is the upper part of the market, but obtained in a completely different way: not through a sustainable payout, but through revaluation of currency assets. The pref itself, by the actual 2026 payment (2.3%), ended up in the lower part of the list. The question the investor decides here: is he buying the past payment or the formula that sets it?
Our own conclusion on the security: the Surgutneftegas pref is more accurately described not as a dividend share but as a bond with a coupon of about 11% plus an embedded option on rouble depreciation. The coupon is provided by the profit core, the option by the currency revaluation of roughly $50 bn. The price of this option is almost not reflected in the share now: the market values the company at 0.12 of book value and at 16% of its own cash cushion.
What our portal showed and what we corrected
The potential calculation for Surgut on our portal before this review had four problems, and they are worth naming honestly.
- The dividend model calculated potential on the ordinary share: it took the actual payment of RUB 0.85, a fair yield of 10.5%, and gave a target of RUB 8.10 and a potential of minus 52%. For the ordinary share this is logical in its own way, but it has nothing to do with the pref.
- There was no SNGSP card on the portal at all - even though the pref is the issuer's main security by liquidity: in the last session turnover in it was RUB 1.9 bn against RUB 0.8 bn in the ordinary share.
- The commodity potential model (+7.3%) relied on 2023 statements - the last ones where revenue and EBITDA are disclosed. This is not a calculation error but a consequence of closed reporting, but it should be flagged explicitly.
- A separate model for valuing the pref through the cash pile was tied to the yuan and gave an expected dividend of RUB 9.58 for 2026 and a potential of +57%. Besides the yuan link, it used an effective tax rate of 16% (the reports themselves show 32.6% for 2024 and 35.5% for 2025) and a base dividend from the oil business of RUB 4.00, which implies RUB 434 bn of profit from oil alone - more than the entire profit core over the two audited years.
What changed after recalibration. Deposits were reconciled with the audited balance sheet at 31.12.2025 (RUB 3,881 bn of currency plus RUB 1,843 bn of rouble deposits = RUB 5,724 bn), revaluation is tied to the dollar, the actual tax rate is used, and the oil part is no longer a free parameter: it is fitted so that at an unchanged exchange rate the bottom-up build converges to the RUB 500 bn core from the regression. After that, the two independent models give one and the same dividend - RUB 5.91 (it was 9.58 against 5.91). The target price at a fair yield of 12.4% is RUB 43.2, and the pref's potential moved from +57% to roughly zero. In other words, on dividend logic the share is now fairly valued, and all the undervaluation sits not in the dividend but in the cash pile itself, which does not work for the minority shareholder.
Following the review, all this has been corrected. A separate card for the preferred share has appeared on the portal - frontier.eninvs.com/company/RU_SNGSP. It carries the pref's own dividend history (RUB 12.29 for 2023, RUB 8.50 for 2024, RUB 0.85 for 2025), multiples are calculated from the capitalisation of the whole company, and the cash-pile valuation block now includes a check against the charter formula - the very table "rate on 31 December - dividend - yield" shown above. We also corrected stale market data on the ordinary share: the trailing 12-month dividend was shown as RUB 0.90 instead of RUB 0.85.
Risks: an opaque cash pile, sanctions and no return of capital beyond the formula
- The composition of the cash pile is not disclosed. The estimate of "$50 bn in currency" is derived from the income statement, not from the notes. If the company continues to move funds into roubles, sensitivity to the exchange rate will fall, and with it the upper part of the scenarios.
- The model rests on a single point. Until interim statements for 2026 appear, the latest balance sheet data are for 31 December 2025. We have set up a watcher for any new Surgut report, to recalculate the pile and the constants immediately rather than a year later.
- The profit core is not a constant. A lower key rate reduces interest on the rouble part, a stronger rouble reduces rouble oil revenue. Both effects work against the investor.
- Disclosure is shrinking. For 2025 two lines of the income statement are open, and for 2026 there are no interim statements at all. The investor learns the result after the fact, effectively once a year.
- There is no return of capital. Ordinary shares receive a symbolic dividend, the company does not conduct buybacks, and the ownership structure is opaque. The cash pile does not work for the minority shareholder - which is exactly why a reduction coefficient for management quality is applied to this company's potential in our ranking.
- Sanctions perimeter. The company is under blocking sanctions; the availability and jurisdiction of the currency part have not been publicly confirmed.
Conclusion
The Surgut pref dividend is a formula, not a decision: RUB 0.00921 for each billion roubles of RAS profit, with a "floor" at the level of the ordinary shares. Profit, in turn, is almost linear in the exchange rate: RUB 526 bn plus RUB 33 bn for each rouble of depreciation. At today's exchange rate, 2026 gives RUB 5.9 and 14%, at the rate on the futures curve RUB 6.5 and 15%. The normalised yield by three independent methods is 13-16%, the historical median 14.5%. This is not a premium to OFZ, but the price of the possibility that a cash pile six times the capitalisation may one day start working for the shareholder - and of insurance against rouble depreciation that is hard to buy elsewhere in such volume.
Cards on our portal: preferred share (SNGSP) and ordinary (SNGS). Other Russian issuers - frontier.eninvs.com/region/ru. Weekly analytics - the Telegram channel Enhanced Investments @eninv.
See also: market overview · valuation map · stock screeners