Tochka for RUB 70 bn: what the T-Technologies share issue parameters imply
T-Technologies is buying all of Tochka bank and paying with its own shares. The price will be announced at the end of September, and it will decide whether the deal is neutral for shareholders or expensive. The share issue parameters announced on 26 August imply a valuation of RUB 69-77 bn for Tochka. That is well below the RUB 150-200 bn analysts discussed before the announcement and close to the price at which Interros bought a stake in Tochka from VK four months ago.
The announced issue size points to a Tochka valuation of around RUB 70 bn. The board set a ceiling of 550 mn shares and added that only half of that will actually be needed. 275 mn shares at the current price of RUB 250.8 give RUB 69 bn for 100% of Tochka.
Tochka is profitable, but its peak is behind it. Net profit for 2025 fell 12% to RUB 20.2 bn as expenses rose 38%. In 1H2026 the bank's interest income fell another 14%.
Loans make up 2.5% of Tochka's balance sheet; the rest earns the key rate. 71% of assets sit in accounts with other banks. Tochka earns the spread between the key rate and the almost free balances entrepreneurs keep on their current accounts. Lower rates hit this profit directly.
On last year's profit the price looks fair; on this year's profit it does not. At a RUB 69 bn valuation Tochka costs 3.4x 2025 earnings, against 3.5x for T-Technologies itself. On expected 2026 earnings it is 5.8x against 3.2x.
The seller is the buyer's controlling shareholder. Interros owns more than 41% of T-Technologies and in April 2026 bought 25% of Tochka from VK for RUB 21.2 bn. That purchase gives a verifiable benchmark for a fair price: RUB 85 bn for all of Tochka. Anything above that Interros earns by reselling within six months.
T-Technologies takes all of Tochka and pays with new shares
Tochka has served small businesses since 2015. It is an online bank for entrepreneurs with no branches and has held its own banking licence since 2023. At the end of 2025 client accounts held RUB 353.6 bn. Its credit rating from Expert RA stands at ruA- with a stable outlook.
Ownership is layered. 64% of JSC Tochka belongs to Catalytic People, which T-Technologies and Interros hold almost equally (50.01% and 49.99%). Interros bought another 25% from VK in April 2026, and 11% remains with 1C. T-Technologies' own economic interest in Tochka is 32%.
In February 2026 the group announced its intention to take its stake to 100% and pay with a share issue. On 26 August the board named the maximum issue size, 550 mn shares, or 20.5% of current share capital. The question goes to an extraordinary shareholder meeting on 18 September. The board promises to announce Tochka's valuation and the placement price at the end of September; closing is scheduled for the end of 2026.
A third of the actual issue will go to converting the stake the group already owns through Catalytic People. These shares will return to the group as a quasi-treasury block, which the company does not plan to sell into the market.
The announced issue size implies a Tochka valuation of around RUB 70 bn
The board said the actual need for shares would be half the maximum. Half of 550 mn is 275 mn shares, which at the closing price of RUB 250.8 means RUB 69 bn for all of Tochka.
The other half of the maximum is reserved for pre-emptive rights. In a closed subscription, existing shareholders may buy new shares pro rata to avoid dilution. The board says outright that it plans to set the placement price above the market. In that case nobody will use the pre-emptive right and the reserve will remain unused. Unused shares are to be cancelled.
A placement price above the market works in minority shareholders' favour. The same valuation will require fewer new shares, and dilution will be smaller. At RUB 280 per share the same 275 mn shares would be worth RUB 77 bn.
| Valuation of 100% of Tochka | RUB 69 bn: announced issue size at market price | RUB 85 bn: price at which Interros bought 25% from VK in April | RUB 120 bn: intermediate scenario | RUB 150 bn: low end of analyst estimates |
|---|---|---|---|---|
| Shares to be issued, mn | 275 | 339 | 478 | 598 |
| Share of current share capital | 10.3% | 12.6% | 17.8% | 22.3% |
| Dilution for T shareholders | 7.0% | 8.6% | 12.1% | 15.2% |
| P/E on 2025 profit (RUB 20.2 bn) | 3.4x | 4.2x | 5.9x | 7.4x |
| P/E on 2026 profit, estimate (RUB 12 bn) | 5.8x | 7.1x | 10.0x | 12.5x |
| Price / book (RUB 51.5 bn) | 1.3x | 1.7x | 2.3x | 2.9x |
Calculation based on the announced issue parameters and Moscow Exchange prices as of 31.08.2026, assuming a placement price at market, RUB 250.8 per T-Technologies share. For comparison, T-Technologies itself now trades at 3.5x 2025 earnings, 3.2x expected 2026 earnings and 0.9x book. Dilution is calculated net of roughly 32% of the issue that returns to the group as a quasi-treasury block. If the placement price is above the market, the same valuation will need fewer shares and dilution will be lower.
A key caveat. The phrase "about half" is the board's wording and is not a precise figure. Firm numbers will come at the end of September.
Loans are 2.5% of the balance sheet; the rest earns the key rate
Tochka's assets at the end of 2025 were RUB 415.8 bn. Of these, RUB 295.1 bn was placed with other banks, RUB 79.7 bn held in cash and RUB 17.6 bn invested in OFZ. Loans to customers account for only RUB 10.4 bn.
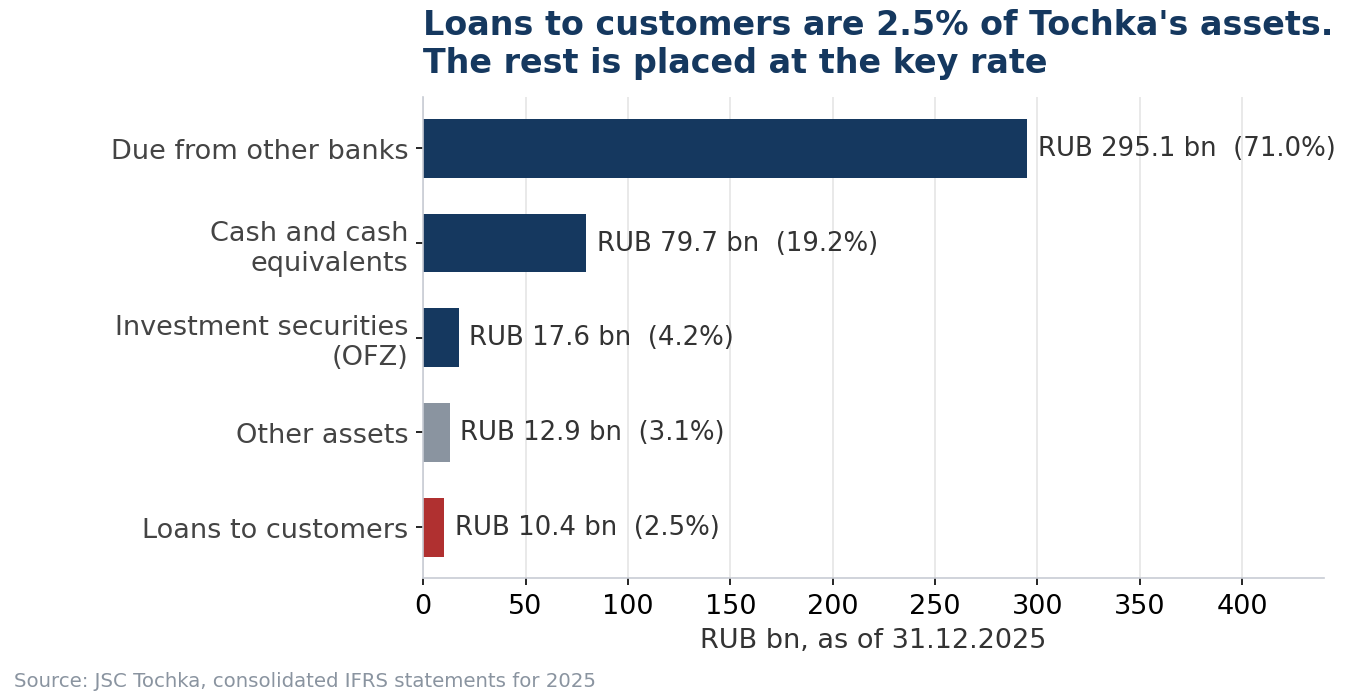
This structure has two consequences. The first is pleasant. There is almost no credit risk: provisions for 2025 were RUB 1.07 bn, and the bank's N1.0 capital adequacy ratio stood at 20.3% against a minimum of 8%. Funds of the ten largest creditors are below 2% of liabilities; funding is spread across hundreds of thousands of entrepreneurs and does not depend on a few large clients.
The second is unpleasant. About 60% of liabilities are current accounts on which the bank pays almost nothing. Interest income for 2025 was RUB 65.8 bn against interest expense of RUB 18.0 bn. The yield on earning assets was 17.3% with an average key rate of 19.2%, and the cost of funding was 5.4%. Tochka's profit is largely a function of the key rate, and the rate has gone from 21% to 14% since the start of 2025.
2025 profit fell 12% because expenses outpaced income
Tochka's net interest income for 2025 rose 18% to RUB 46.4 bn. Licence revenue and IT services income grew 35% to RUB 9.1 bn. Meanwhile, administrative and other operating expenses rose 38%, from RUB 24.7 bn to RUB 34.1 bn.
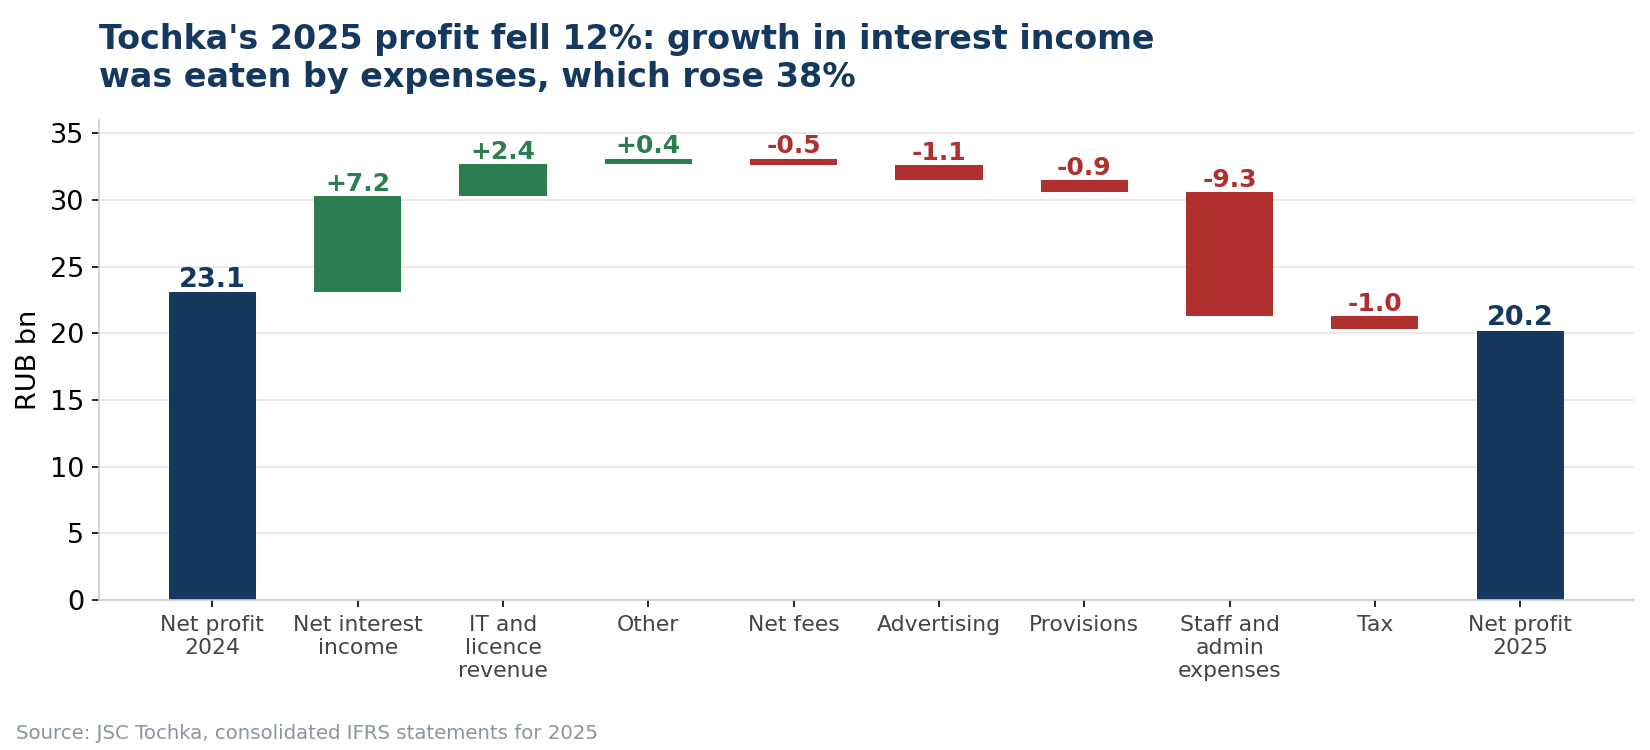
The cost-to-income ratio worsened from 46% to 56%. Fee income barely grew, RUB 11.9 bn against RUB 11.4 bn a year earlier. Advertising income more than halved, from RUB 1.9 bn to RUB 0.8 bn. Pre-tax profit fell 6% and net profit 12%, because the effective tax rate rose from 19.9% to 25.0%.
Return on equity nevertheless remains high at 42% on average equity for the year. Group equity at the end of 2025 was RUB 51.5 bn.
Dividends deserve separate attention. For 2025 Tochka declared RUB 14 bn, which is 69% of profit and a fifth of the expected deal price. The money went to the current owners, including Interros and 1C, before the company passes to T-Technologies.
The decline continued in 1H2026
Tochka publishes consolidated statements once a year, but the bank reports to the Bank of Russia on Form 102. That shows what is happening right now.
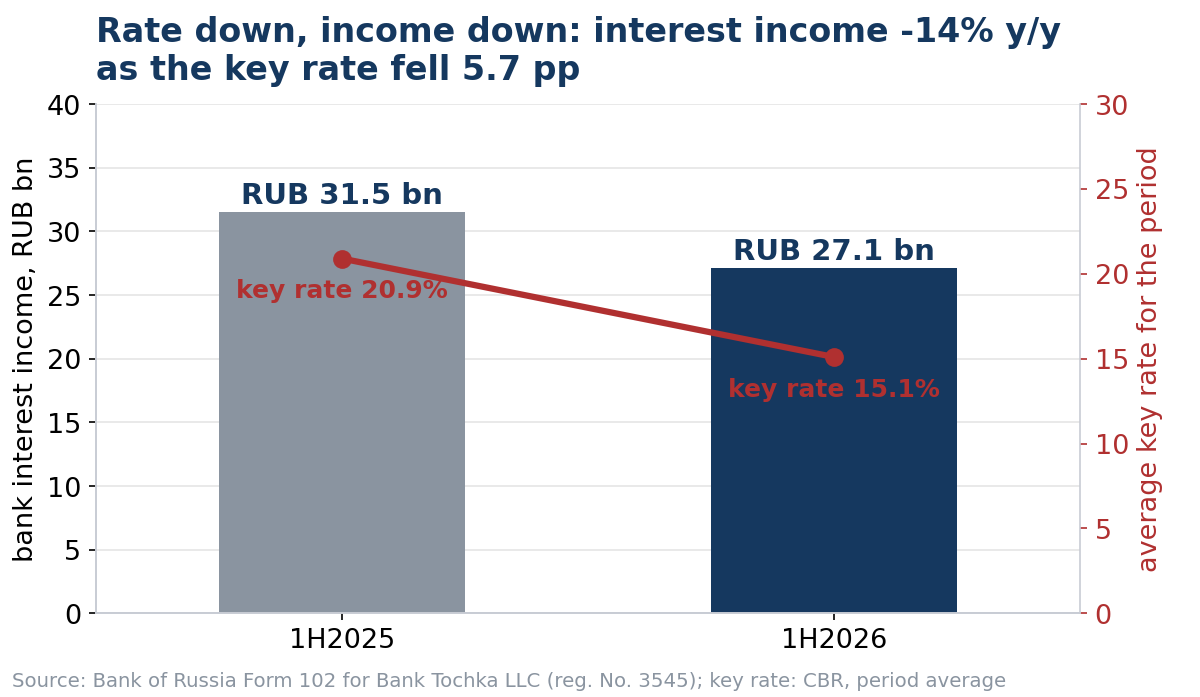
The bank's interest income for 1H2026 was RUB 27.1 bn against RUB 31.5 bn a year earlier, down 14%. Interest expense fell less, by 11%, so the bank's net interest income shrank 15%. The average key rate over the same period dropped from 20.9% to 15.1%. Fee income grew 4.8% and could not offset the drop.
The bank's profit under Russian accounting standards rose by half for the half-year, to RUB 9.5 bn, but this figure is not useful for valuing the business. The bank regularly pays fees to its parent company, and the allocation of costs within the group changed sharply over the year. The "other operating expenses" line fell from RUB 18.7 bn to RUB 4.5 bn, while operating support expenses rose from RUB 2.1 bn to RUB 6.5 bn. The bank's total expenses nearly halved, which is what created the profit growth on paper. Only the holding's consolidated statements show the economics of the business.
Tax added to this. From 1 January 2026, Law 425-FZ extended VAT to operations and services related to bank card servicing and IT interaction between payment participants. Tochka described this as a subsequent event in its 2025 statements. Fee and licence revenue are hit, exactly the lines that were supposed to replace interest income.
The authors' estimate for 2026 is as follows. If the group's net interest income falls 15% in line with the bank, fees grow 5%, IT revenue grows 15%, provisions double on the back of a fivefold larger loan book, and expenses rise 10-20%, net profit for the year comes to RUB 10-13 bn against RUB 20.2 bn for 2025. This is an estimate, not a company forecast, and it depends entirely on the path of the key rate.
On last year's profit the deal is neutral; on this year's it dilutes EPS by 3%
T-Technologies is not buying all of Tochka. The group already holds 32%, so the actual acquisition comes down to the remaining 68%.
At a valuation of RUB 69 bn for all of Tochka, 187 mn new shares are issued to outside owners for this 68%, diluting existing shareholders by 7.0%. In return the group receives 68% of Tochka's 2025 profit, RUB 13.7 bn, or 7.1% of its own profit for the same year (RUB 192.4 bn). Earnings per share are unchanged in this case.
On 2026 data the calculation looks worse. The acquired share of profit will be RUB 8.2 bn assuming Tochka earns RUB 12 bn, while T-Technologies' operating net profit, by the company's own guidance, will grow by more than 20% to RUB 209 bn. Gaining 3.9% of profit against 7.0% dilution means a 3% loss in earnings per share.
The second angle concerns book value. At a RUB 69 bn valuation Tochka costs 1.3x its book value, while T-Technologies shares trade at 0.9x book. The company pays with stock that is undervalued relative to its balance sheet for an asset priced above its book, and book value per share falls as a result. There is a justification. Tochka's 42% return on equity is well above T-Technologies' own 27%, and it is logical to pay a higher price-to-book multiple for higher returns.
There is visible synergy in the deal, but the company has not yet given any figures for it. T-Bank and Tochka operate in the same segment and compete for the same client, so part of the effect will come from cutting duplicate costs, and part of the client base may overlap.
Interros sits on both sides of the table
The seller and the buyer are directly related here. Interros owns more than 41% of T-Technologies, holds the other half of Catalytic People, and also owns the 25% of Tochka bought from VK. The price is set by the board of a company whose largest shareholder is Interros.
The good news is that there is an external benchmark to check the price against. VK bought 25% of Tochka in 2023 for RUB 11.6 bn, received RUB 4.3 bn in dividends while it held the stake, and sold it to Interros in April 2026 for at least RUB 21.2 bn. The April deal values all of Tochka at RUB 84.8 bn, and it was concluded between two unrelated parties.
This gives a simple test. A valuation of about RUB 85 bn means Interros passes on the stake at cost and makes nothing on the resale. A higher valuation means the stake appreciated over four months of ownership, and the other T-Technologies shareholders will pay for it through dilution. A valuation below RUB 85 bn would be a gift to minority shareholders, but there is no reason to count on it.
The company itself said the independent valuation will take into account market approaches, financial and technology sector multiples, and T-Technologies' own share price. The last point matters most. T-Technologies currently trades at 3.5x earnings, and valuing Tochka well above the buyer's own multiples would be odd.
What to check at the end of September
Valuation of 100% of Tochka. The benchmark is RUB 84.8 bn from Interros' April deal with VK. Anything above RUB 100 bn means a premium to the recent market price, paid by minority shareholders.
Placement price. The further it is above the market, the fewer shares go for the same amount and the smaller the dilution. A high price also settles the pre-emptive rights question.
Actual issue size. 275 mn shares would confirm a valuation of around RUB 70 bn; approaching 550 mn would mean a valuation twice as high.
Voting procedure at the 18 September meeting. This is a related-party transaction, and good practice would be separate approval by disinterested shareholders. It is worth checking how the agenda is worded.
Tochka dividends before closing. RUB 14 bn was taken out of the company for 2025. Any new payouts before closing should reduce the price; otherwise the buyer pays for money that is no longer there.
See also: market overview · valuation map · stock screeners