Tatneft H1 2026: EBITDA up 79%, but net profit turned negative on FX losses and tire business disposal
31 августа 2026 года Татнефть раскрыла результаты за первое полугодие 2026 года: выручка выросла на 15,8% до 881,6 млрд руб., EBITDA — на 79,4% до 259,3 млрд руб., при этом чистая прибыль составила минус 0,8 млрд руб. против убытка годом ранее. Основной удар по прибыли нанесён убытком от курсовых разниц и расходами по сделке по продаже шинного бизнеса, отражёнными в составе прекращённых операций. При текущей цене акция выглядит привлекательно: мультипликатор EV/EBITDA (3,8) ниже собственного трёхлетнего среднего (3,4), дивидендная доходность 5,9% за 12 месяцев и 7,7% по нашей оценке следующей выплаты, а модель портала даёт потенциал роста +17%.
Key takeaways
— EBITDA grew 79% on stronger Refining & Marketing segment and lower FX losses
— Net profit turned negative due to FX losses and the effect of the tire business disposal
— Operating cash flow rose to RUB 207.9 bn, while capex declined
— Leverage remains low: net debt is negative and net debt/EBITDA stands at -0.1
— Dividends over 12 months were RUB 34.09 per share, a 5.9% yield — below our fair level of 10.5%
— The portal's model sees +17% upside for the share at current oil prices
Attractiveness
Key figures, RUB bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 761 | 882 | +15.8% |
| EBITDA | 145 | 259 | +79.4% |
| Operating profit | 111 | 222 | +99.5% |
| Net profit | -24.9 | -4.30 | — |
| Operating cash flow | -14.8 | -4.06 | — |
| Capex | 67.8 | 62.5 | -7.9% |
| EBITDA margin | 19.0% | 29.4% | +10.4 pp |
| Net margin | -3.3% | -0.5% | +2.8 pp |
EBITDA grew 79% on stronger Refining & Marketing segment and lower FX losses
In H1 2026, Tatneft's EBITDA reached RUB 259.3 bn versus RUB 144.5 bn a year earlier (derived from RUB 881.6 bn of H1 revenue less operating expenses, plus depreciation and excluding financial items). The 79.4% growth was driven mainly by the Refining & Marketing segment, whose result rose from RUB 47.9 bn to RUB 152.5 bn on higher refined product sales and a lower FX loss (RUB 24.9 bn in H1 2025, RUB 33.7 bn in Q2 2025).
EBITDA margin expanded to 29.4% from 19.0% a year earlier, reflecting both operational improvement and a presentation change: the tire business, sold in Q1 2026, is now shown as discontinued operations and its results are excluded from continuing operations. Revenue growth of 15.8% to RUB 881.6 bn was supported by higher sales of own crude oil (RUB 310.0 bn vs RUB 257.6 bn) and refined products (RUB 504.0 bn vs RUB 450.7 bn).
Net profit turned negative due to FX losses and the effect of the tire business disposal
Net profit for H1 2026 was minus RUB 0.8 bn versus a loss of RUB 3.3 bn a year earlier (derived from RUB 54.2 bn of profit in H1 2025, adjusted for the loss from discontinued operations). The report shows profit from continuing operations of RUB 161.5 bn, but then a loss from discontinued operations of RUB 4.0 bn and the effect of the tire business disposal, recorded directly in equity (minus RUB 51.5 bn in retained earnings).
The main driver of the loss was FX: the FX loss for H1 2026 was RUB 4.3 bn (versus RUB 24.9 bn a year earlier), but in Q2 2025 it was RUB 33.7 bn — pointing to rouble volatility. In addition, other operating expenses include impairment losses of RUB 2.7 bn and expected credit losses of RUB 8.9 bn.
Operating cash flow rose to RUB 207.9 bn, while capex declined
Operating cash flow for H1 2026 was RUB 207.9 bn versus RUB 104.7 bn a year earlier, reflecting higher pre-tax profit and improved working capital management (accounts receivable rose by RUB 68.7 bn, but accounts payable by RUB 25.6 bn and taxes payable by RUB 58.0 bn).
Capex for the half-year declined to RUB 59.8 bn (versus RUB 65.6 bn a year earlier), while additions to property, plant and equipment were RUB 58.0 bn. Free cash flow (operating flow minus capex) was about RUB 148.1 bn (derived), covering dividends and allowing further debt reduction.
Leverage remains low: net debt is negative and net debt/EBITDA stands at -0.1
At end-June 2026, Tatneft's net debt was minus RUB 36.9 bn, meaning cash and financial investments exceed debt. Net debt/EBITDA over the trailing twelve months was minus 0.1, indicating virtually no leverage.
Over the last 12 months, net debt declined by RUB 165.4 bn (by RUB 115.5 bn since the previous reporting date), driven by strong operating flow and moderate capex. The company also has access to debt financing: it raised RUB 54.1 bn and repaid RUB 70.0 bn of debt during the half-year.
Dividends over 12 months were RUB 34.09 per share, a 5.9% yield — below our fair level of 10.5%
Over the last 12 months, Tatneft paid dividends of RUB 34.09 per share, a yield of 5.9% at the current price. This is well below the 10.5% level we consider fair for this stock, pointing to upside in the share price or the need for higher payouts.
Our model estimates the next payout at RUB 44.49 per share, implying a forward yield of 7.7% — still below the fair level, but closer to it. The implied payout ratio of 0.48 of profit leaves ample room to raise dividends without hurting the investment programme.
The portal's model sees +17% upside for the share at current oil prices
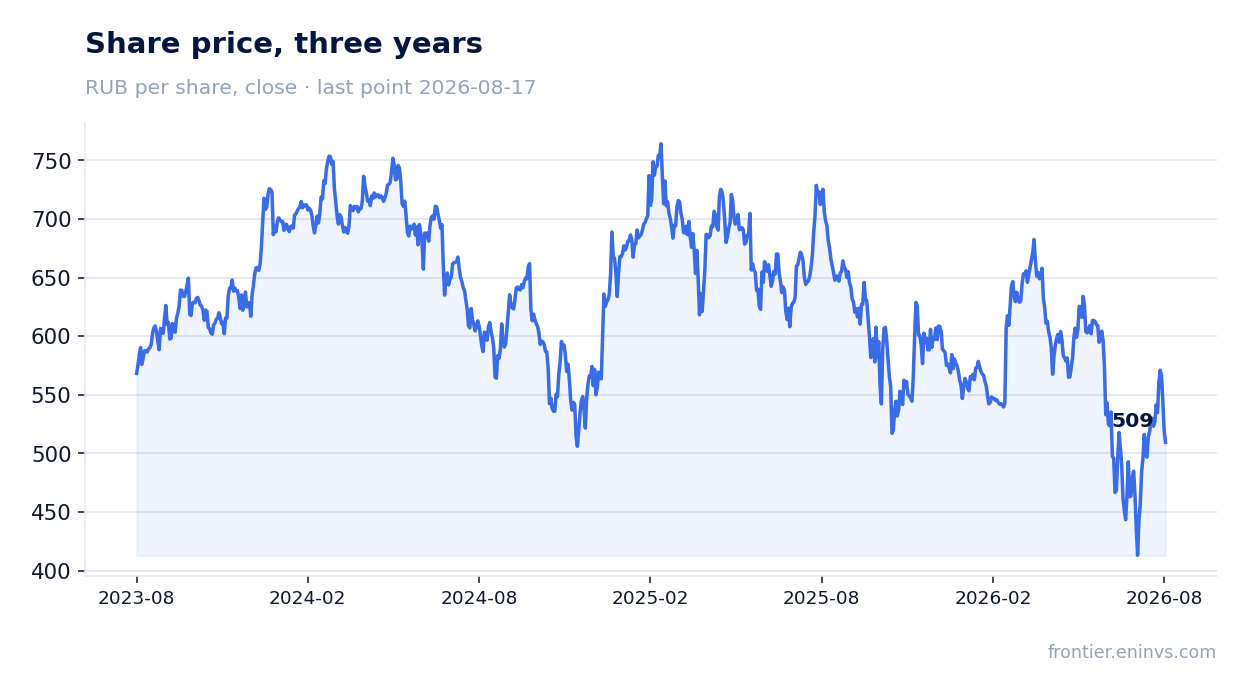
Our portal's model, which re-prices EBITDA at current oil prices and applies a target EV/EBITDA multiple, shows the share has +17% upside to fair value. This means the market values the company cheaper than we consider justified at the current environment.
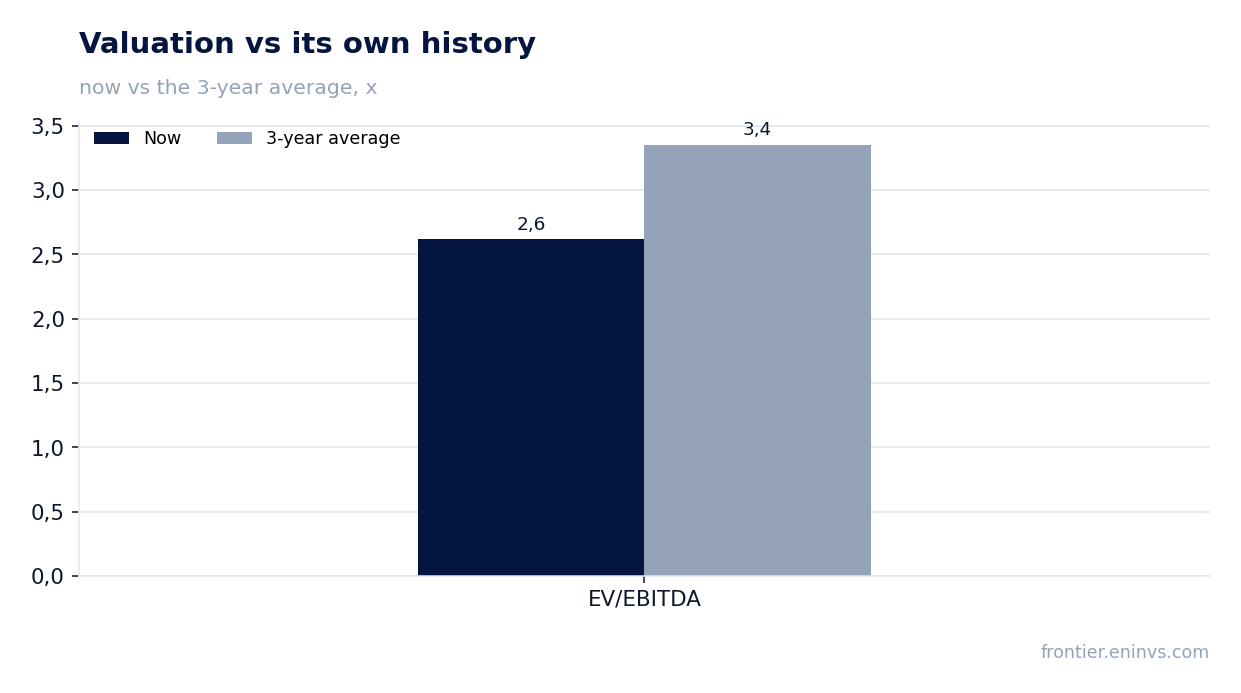
The current EV/EBITDA multiple is 3.8 versus the three-year average of 3.4 — the share trades at a slight discount to its own history, despite strong EBITDA growth and low leverage. P/E over the trailing twelve months is 9.3, also looking moderate for a company with such cash flows.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 1 409 bn ₽ |
| P/E (LTM) | 9.3 |
| EV/EBITDA (LTM) | 3.8 |
| P/B | 1.06 |
| Net debt / EBITDA (LTM) | -0.10 |
| ROE | -0.6% |
| Dividend yield (12m) | 5.8% |
| EV/EBITDA, 3-year average | 3.4 |
Bottom line
The strong side of the report is operational: EBITDA grew 79% to RUB 259.3 bn, margin expanded to 29.4%, and operating cash flow doubled to RUB 207.9 bn. The net loss is the result of FX losses and one-off effects from the tire business disposal, not a deterioration of the core business. Leverage is virtually zero, giving the company freedom to raise dividends. With EV/EBITDA of 3.8 versus the 3.4 average and +17% upside on the portal's model, the share looks attractive, but realising that potential depends on rouble stability and the company's ability to increase payouts to a fair yield level.
Open the company's financial profile TATN →
See also: market overview · valuation map · stock screeners