Transneft (pref): revenue grows, but EBITDA falls — margin compresses to 37.0%
28 августа Транснефть (прив) раскрыла результаты за второй квартал 2026 года: выручка выросла на 5,8% год к году до 378,8 млрд руб., но EBITDA снизилась на 5,7% до 140,3 млрд руб., а маржа по EBITDA упала с 41,5% до 37,0%. При этом чистая прибыль прибавила 3,8%, до 80,2 млрд руб. На текущей цене акция выглядит привлекательно: мультипликатор EV/EBITDA составляет 0,94 против среднего за три года 1,33, а дивидендная доходность 19,2% более чем вдвое превышает наш справедливый уровень в 10,5%.
Key takeaways
— Revenue +5.8% in Q2 — the strongest growth in five quarters, but EBITDA fell 5.7% on higher operating costs
— EBITDA margin narrowed from 41.5% to 37.0% — labour and materials costs rose faster than revenue
— Net profit +3.8% was driven by higher other income and share of associates' profit, not by operations
— Debt burden stays negative: net debt of minus RUB 307.4 bn, net debt/EBITDA of minus 0.57
— Capex for H1 reached RUB 157.7 bn, exceeding operating cash flow of RUB 136.0 bn
— Dividend for 2025 — RUB 204.17 per share, yield 19.2% versus our fair yield of 10.5%
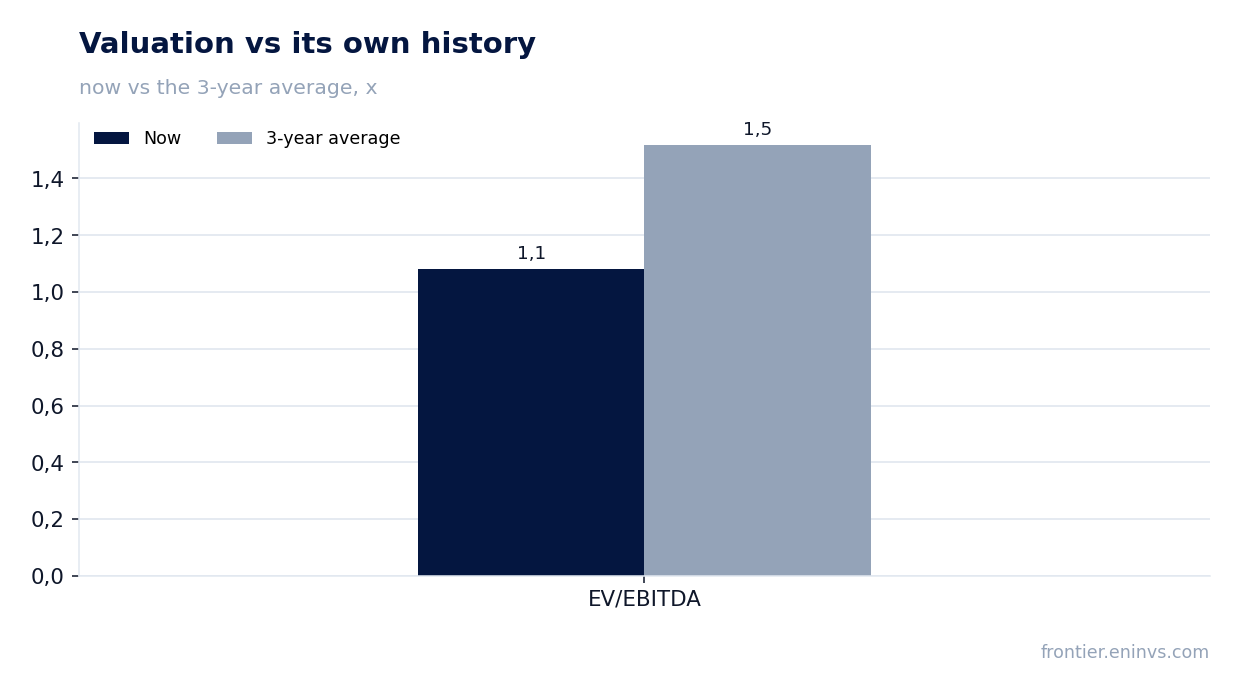
— Valuation: EV/EBITDA of 0.94 versus its 3-year average of 1.33 — the stock trades at a discount to its own history
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 358 | 379 | +5.8% |
| EBITDA | 149 | 140 | -5.7% |
| Operating profit | 89.3 | 83.6 | -6.4% |
| Net profit | 77.2 | 80.2 | +3.8% |
| Operating cash flow | 60.7 | 41.4 | -31.8% |
| Capex | 80.4 | 81.0 | +0.7% |
| EBITDA margin | 41.5% | 37.0% | -4.5 pp |
| Net margin | 21.6% | 21.2% | -0.4 pp |
Revenue +5.8% in Q2 — the strongest growth in five quarters, but EBITDA fell 5.7% on higher operating costs
In Q2 2026, Transneft (pref) revenue reached RUB 378.8 bn, up 5.8% year-on-year. This is the strongest reading in five quarters: previous growth rates ranged from minus 2.0% to plus 4.5%. The main driver was core revenue – oil and oil products transportation – which rose to RUB 338.0 bn from RUB 321.3 bn a year earlier.
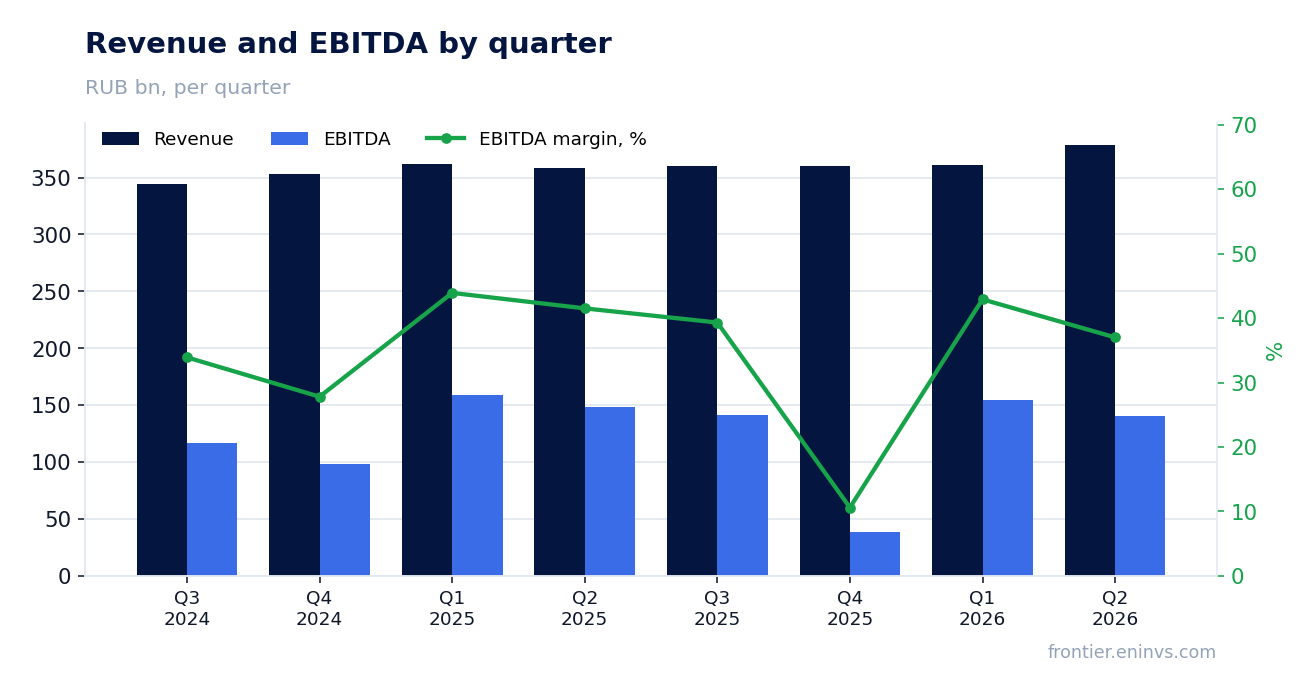
However, quarterly EBITDA fell 5.7% to RUB 140.3 bn. Operating expenses before depreciation increased 14.2% to RUB 238.8 bn, far outpacing revenue growth. As a result, operating profit declined 6.4% to RUB 83.6 bn.
EBITDA margin narrowed from 41.5% to 37.0% — labour and materials costs rose faster than revenue
EBITDA margin in Q2 2026 stood at 37.0% versus 41.5% in the same period a year earlier. Pressure came from operating cost lines: labour costs, insurance premiums and social expenses rose to RUB 98.9 bn from RUB 85.0 bn a year earlier, and materials costs to RUB 29.5 bn from RUB 24.1 bn.
Cost of goods sold also increased – to RUB 79.6 bn from RUB 70.1 bn in Q2 2025. As a result, operating profit before depreciation fell to RUB 140.1 bn from RUB 148.9 bn, while net margin was nearly flat at 21.2% versus 21.6% a year earlier.
Net profit +3.8% was driven by higher other income and share of associates' profit, not by operations
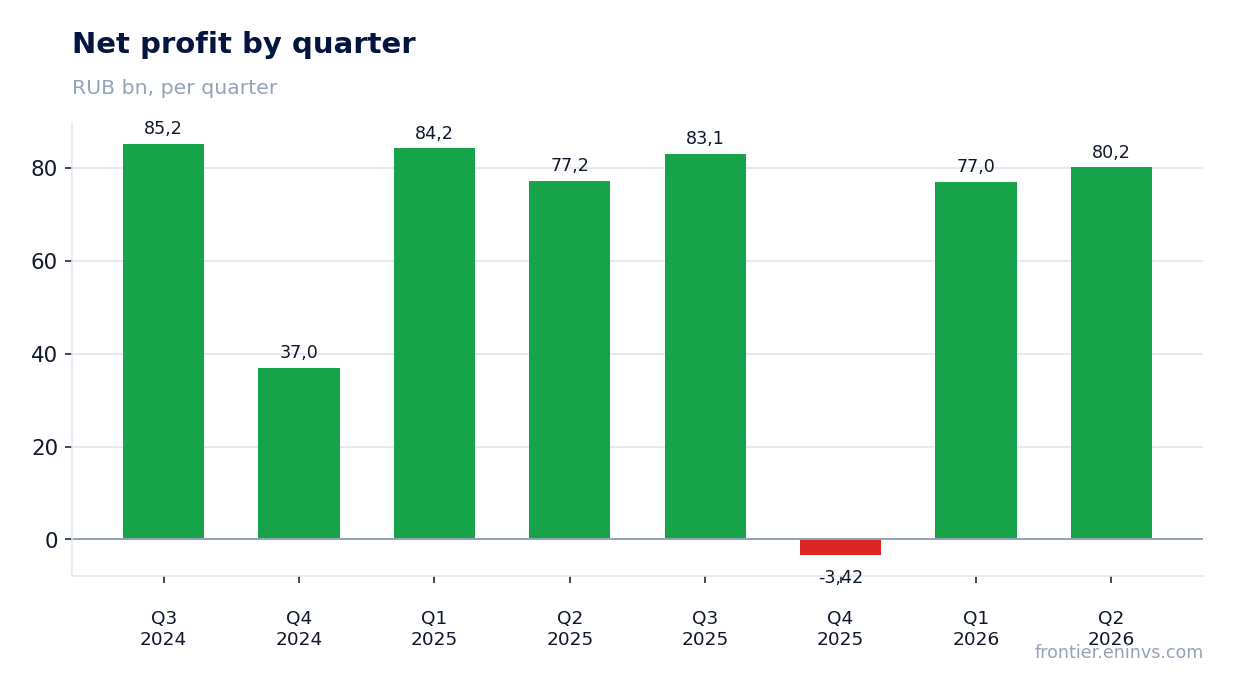
Net profit in Q2 2026 rose 3.8% to RUB 80.2 bn, despite lower operating profit. Support came from other income, which increased to RUB 8.3 bn from RUB 2.3 bn a year earlier, and from the share of profit of associates and joint ventures – RUB 12.9 bn versus RUB 5.2 bn.
Finance income, by contrast, fell to RUB 29.6 bn from RUB 34.2 bn, partly offsetting the gain in other items. The effective income tax rate declined to 35.6% from 38.4%, also supporting the bottom line.
Debt burden stays negative: net debt of minus RUB 307.4 bn, net debt/EBITDA of minus 0.57
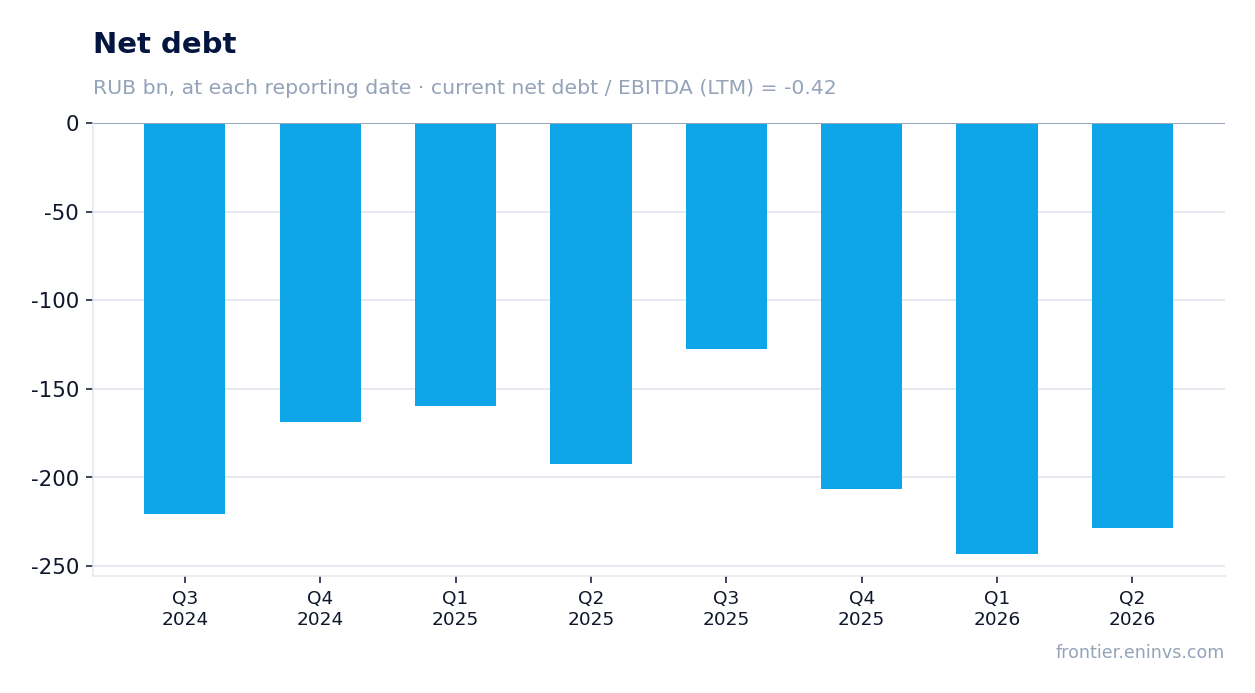
At the end of Q2 2026, Transneft (pref) net debt stood at minus RUB 307.4 bn – the company remains a net creditor. Net debt rose by RUB 14.9 bn over the quarter but fell by RUB 36.3 bn over the trailing twelve months.
Net debt/EBITDA for the last twelve months is minus 0.57. Cash and deposits on the balance sheet reach RUB 442.5 bn, comfortably covering loans and borrowings of RUB 157.4 bn.
Capex for H1 reached RUB 157.7 bn, exceeding operating cash flow of RUB 136.0 bn
In H1 2026, Transneft (pref) capital expenditures reached RUB 157.7 bn, while operating cash flow was RUB 136.0 bn. The gap was covered by drawing down cash and deposits: the cash balance fell to RUB 122.4 bn from RUB 223.5 bn at the start of the year.
In Q2, operating cash flow was only RUB 41.4 bn – the lowest level in eight quarters. Capex remains high at RUB 81.0 bn for the quarter, consistent with the company's investment programme.
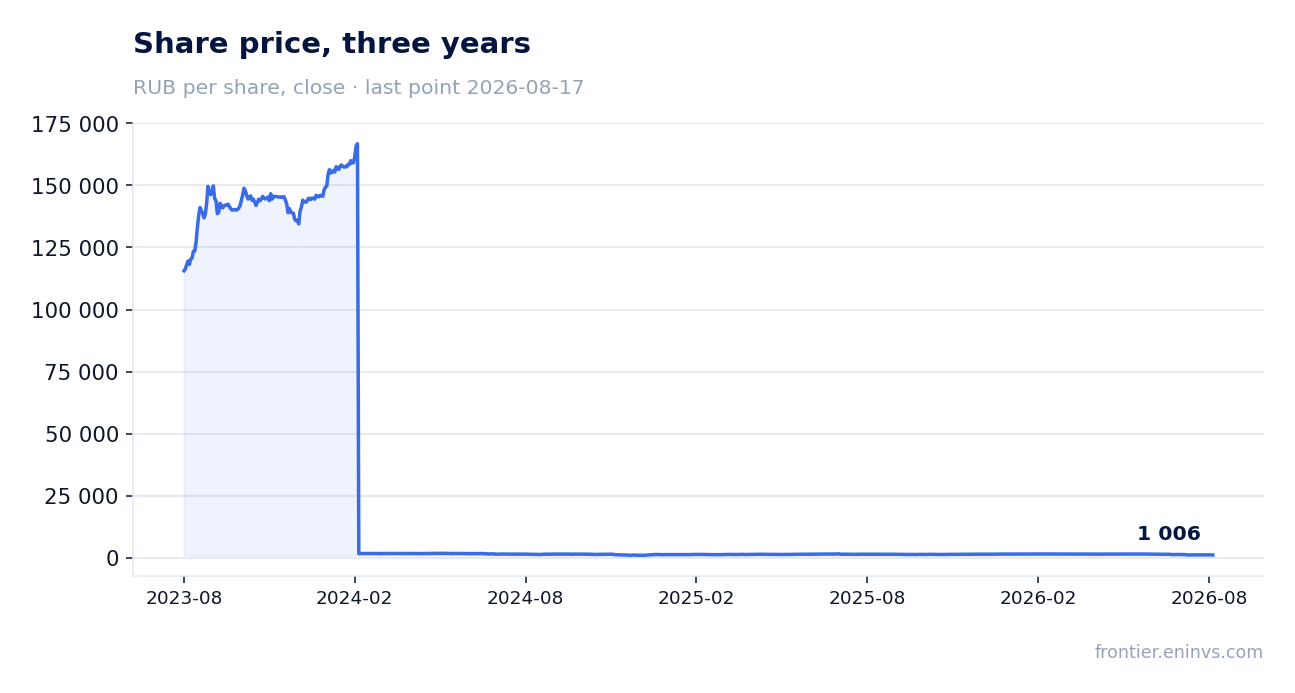
Dividend for 2025 — RUB 204.17 per share, yield 19.2% versus our fair yield of 10.5%
The annual shareholders' meeting in June 2026 approved dividends for 2025 of RUB 204.17 per share – both ordinary and preferred. Payments on preferred shares were made in July and August 2026.
The trailing twelve-month dividend yield is 19.2%, well above our fair yield of 10.5%. The implied payout ratio is 0.5 of profit, leaving room to sustain dividends.
Valuation: EV/EBITDA of 0.94 versus its 3-year average of 1.33 — the stock trades at a discount to its own history
Transneft (pref) trades at an EV/EBITDA of 0.94 for the last twelve months, well below its three-year average of 1.33. P/E stands at 3.19, also pointing to undervaluation relative to historical levels.
Return on equity is 10.5%, which at the current price provides shareholders with a return above the cost of capital. The stock is held in our live model strategies on the portal: RU AI conviction (Claude), RU AI long-short (market-neutral), and RU Dividend growers (income).
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 756 bn ₽ |
| P/E (LTM) | 3.2 |
| EV/EBITDA (LTM) | 0.9 |
| P/B | 0.25 |
| Net debt / EBITDA (LTM) | -0.57 |
| Operating cash flow (LTM) | 439 bn |
| ROE | 10.5% |
| Dividend yield (12m) | 19.2% |
| EV/EBITDA, 3-year average | 1.3 |
Bottom line
The strength of the report is revenue growth – the best in five quarters – and resilient net profit, supported by non-operating items. However, operating efficiency deteriorated: EBITDA margin fell 4.5 percentage points, and Q2 operating cash flow was the lowest in two years. Capex exceeds operating cash flow, funded by the accumulated liquidity cushion. Valuation remains attractive: EV/EBITDA of 0.94 versus its 3-year average of 1.33, and a dividend yield of 19.2% is more than double our fair yield. The key question for holders is whether the company can sustain margins and cash flow amid rising costs without cutting its investment programme.
Open the company's financial profile TRNFP →
See also: market overview · valuation map · stock screeners