Transneft (pref): revenue accelerated to 5.8%, but EBITDA fell 5.7%
On 28 September, Transneft (pref) reported results for the second quarter of 2026. Revenue rose 5.8% year on year to RUB 378.8 bn, net profit added 3.8% to RUB 80.2 bn, but EBITDA fell 5.7% to RUB 140.3 bn and the EBITDA margin dropped to 37.0% from 41.5%. With an EV/EBITDA multiple of 0.93 versus its three-year average of 1.33 and an expected dividend yield of 18.9%, the share looks attractive, but the weakness in EBITDA and the absence of payouts over the last 12 months call for caution.
Key takeaways
— Revenue accelerated to 5.8% year on year, but EBITDA fell 5.7%
— EBITDA margin dropped to 37.0% from 41.5% a year earlier
— Net profit rose 3.8%, but the margin was almost unchanged at 21.2%
— Operating cash flow fell to RUB 41.4 bn with capex at RUB 81.0 bn
— Net debt remains negative: –RUB 307.4 bn as of 30 June 2026
— No dividends paid over the last 12 months, but our estimate for the current year is RUB 196.01 per share
— EV/EBITDA of 0.93 is below the three-year average of 1.33, pointing to undervaluation
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 358 | 379 | +5.8% |
| EBITDA | 149 | 140 | -5.7% |
| Operating profit | 89.3 | 83.6 | -6.4% |
| Net profit | 77.2 | 80.2 | +3.8% |
| Operating cash flow | 60.7 | 41.4 | -31.8% |
| Capex | 80.4 | 81.0 | +0.7% |
| EBITDA margin | 41.5% | 37.0% | -4.5 pp |
| Net margin | 21.6% | 21.2% | -0.4 pp |
Revenue accelerated to 5.8% year on year, but EBITDA fell 5.7%
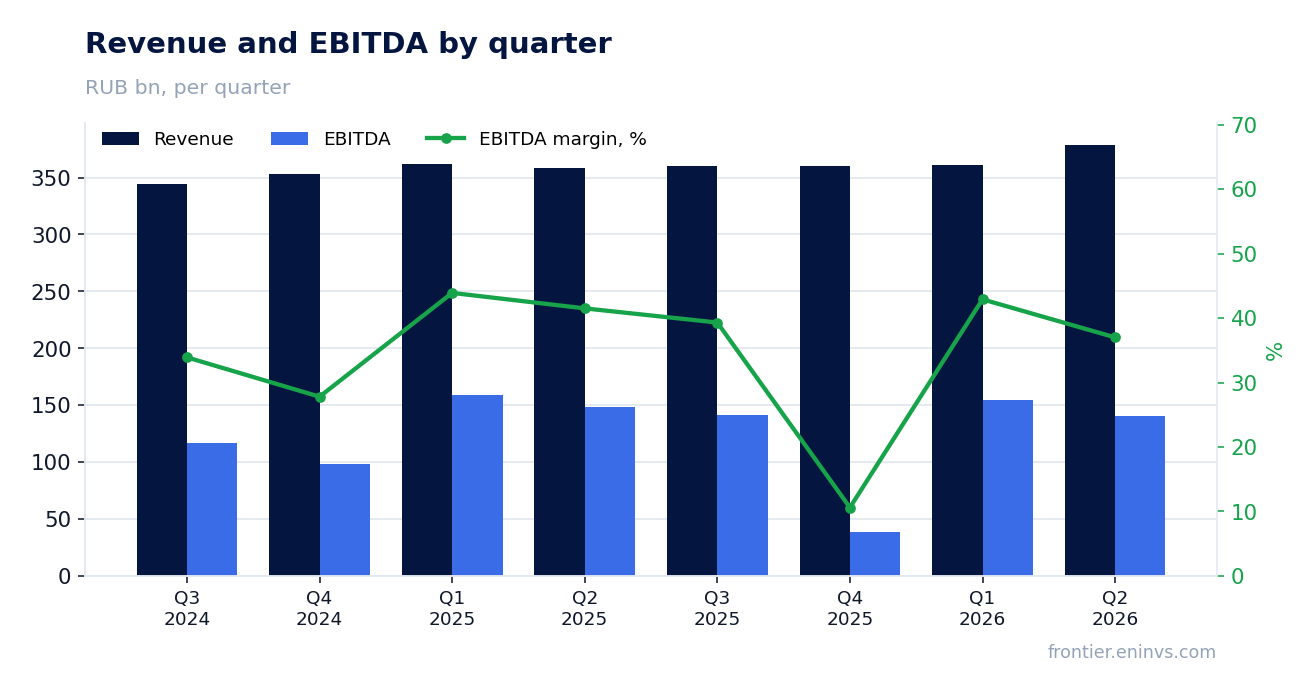
In the second quarter of 2026, Transneft (pref) revenue grew 5.8% year on year to RUB 378.8 bn. This is a marked acceleration compared with the first quarter, when growth was only 0.1%. The main contribution to revenue growth likely came from export supplies and tariffs, but details are not disclosed in the report.
However, EBITDA for the same period fell 5.7% to RUB 140.3 bn, and the EBITDA margin dropped to 37.0% from 41.5% a year earlier. This divergence points to faster growth in costs that are eating into revenue. Operating profit also declined, to RUB 83.6 bn from RUB 89.3 bn a year earlier.
EBITDA margin dropped to 37.0% from 41.5% a year earlier
The 4.5 percentage point decline in EBITDA margin to 37.0% indicates that revenue growth did not translate into profitability. With revenue of RUB 378.8 bn and EBITDA of RUB 140.3 bn, the share of costs in revenue increased. This could be due to higher operating expenses, but the exact reasons are not detailed in the report.
For investors, this is a signal that the company is facing cost pressure that may persist in coming quarters. If the margin does not recover, it will limit profit growth and the dividend base.
Net profit rose 3.8%, but the margin was almost unchanged at 21.2%
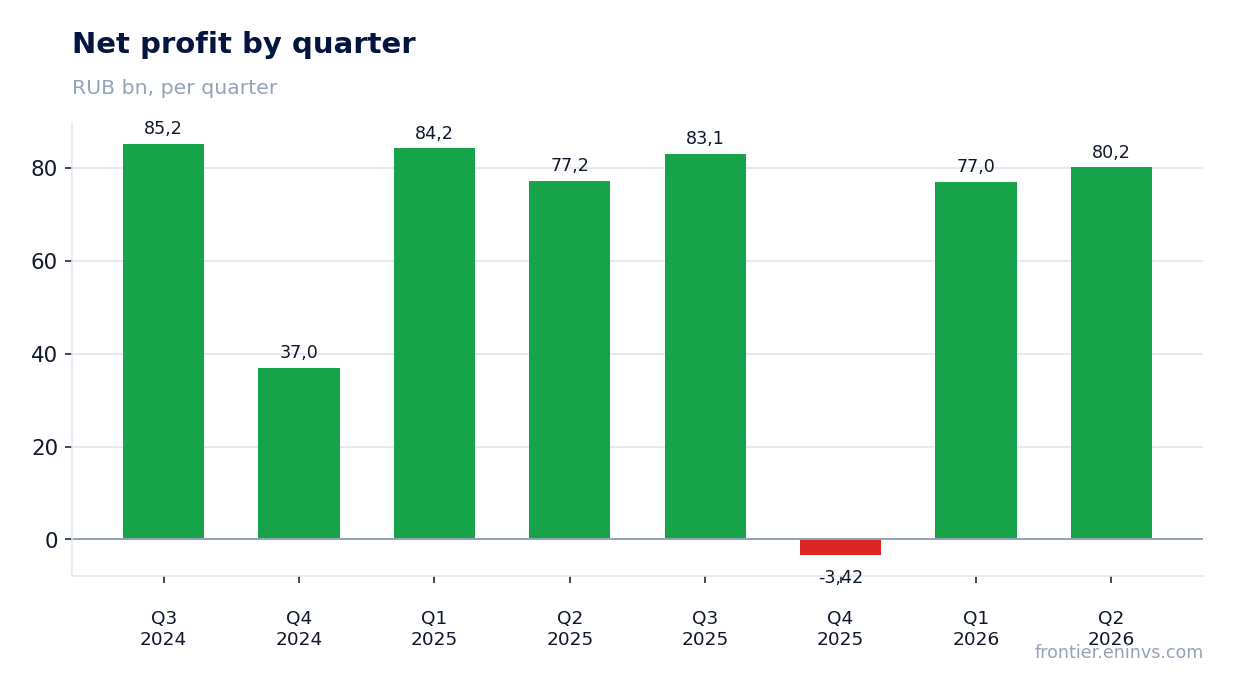
Net profit in the second quarter of 2026 was RUB 80.2 bn, up 3.8% from a year earlier. The net margin was almost unchanged at 21.2% versus 21.6%. This means the company managed to maintain profitability at last year's level despite the decline in EBITDA.
Net profit was likely supported by financial income related to negative net debt or lower tax payments. However, without detailed reporting, it is impossible to say for sure. Importantly, net profit is growing slower than revenue, reflecting pressure on operating efficiency.
Operating cash flow fell to RUB 41.4 bn with capex at RUB 81.0 bn
Operating cash flow in the second quarter of 2026 was RUB 41.4 bn, significantly lower than RUB 60.7 bn a year earlier. At the same time, capital expenditures remained high at RUB 81.0 bn. As a result, free cash flow was negative: an outflow of about RUB 39.6 bn.
This means the company is financing investments from accumulated reserves or borrowed funds, despite negative net debt. High capex may be related to large projects, but their payback is not yet clear. For dividend payments, this level of free cash flow poses a risk.
Net debt remains negative: –RUB 307.4 bn as of 30 June 2026
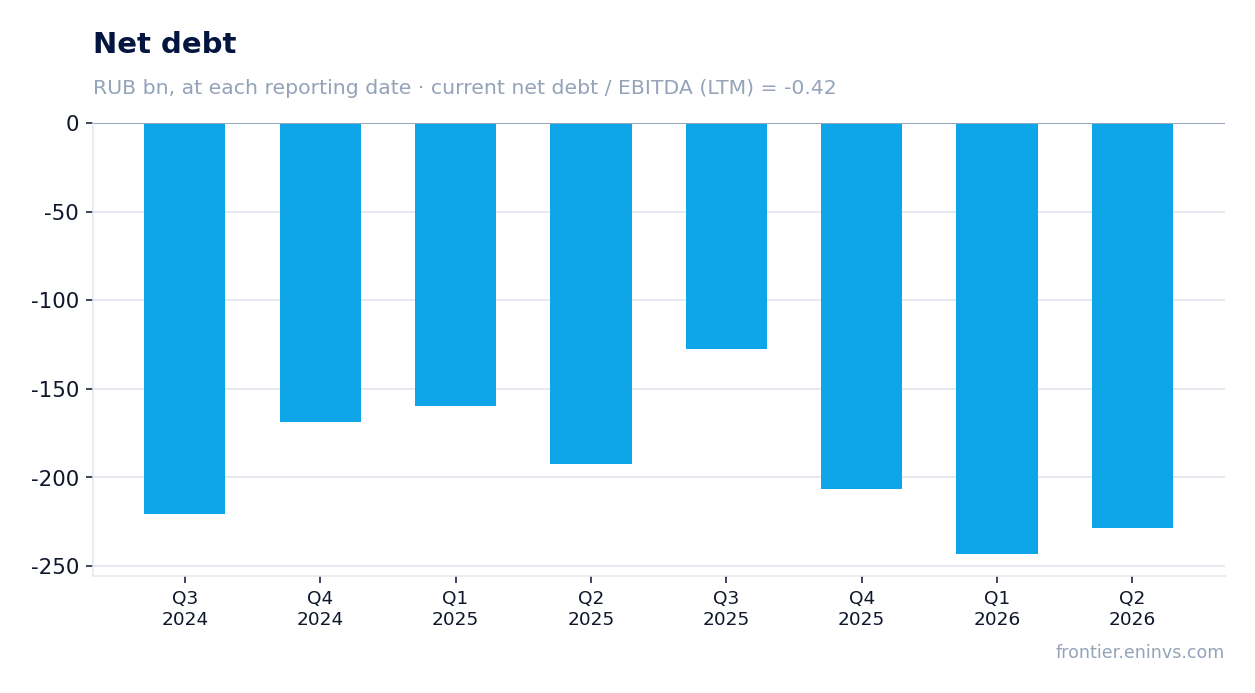
Transneft (pref) net debt as of 30 June 2026 was –RUB 307.4 bn, meaning the company has a significant cash cushion. Compared with 31 March 2026, net debt changed from –RUB 325.8 bn to –RUB 307.4 bn (+RUB 18.4 bn), and over 12 months from –RUB 263.6 bn to –RUB 307.4 bn (–RUB 43.8 bn).
Negative net debt means cash exceeds debt obligations. This reduces financial risks and supports credit quality. However, the direction of change does not allow us to speak of a decrease or increase in leverage, since the net debt/EBITDA LTM ratio is –0.62, and its previous value is not in the facts.
No dividends paid over the last 12 months, but our estimate for the current year is RUB 196.01 per share
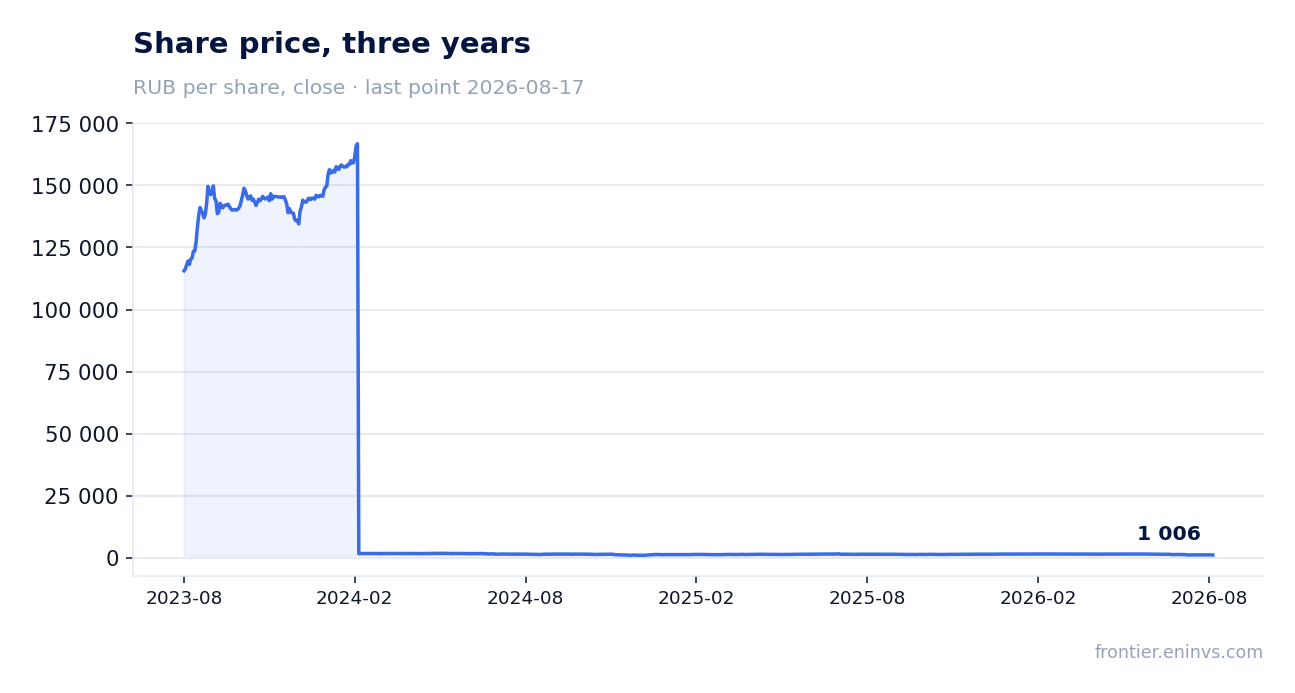
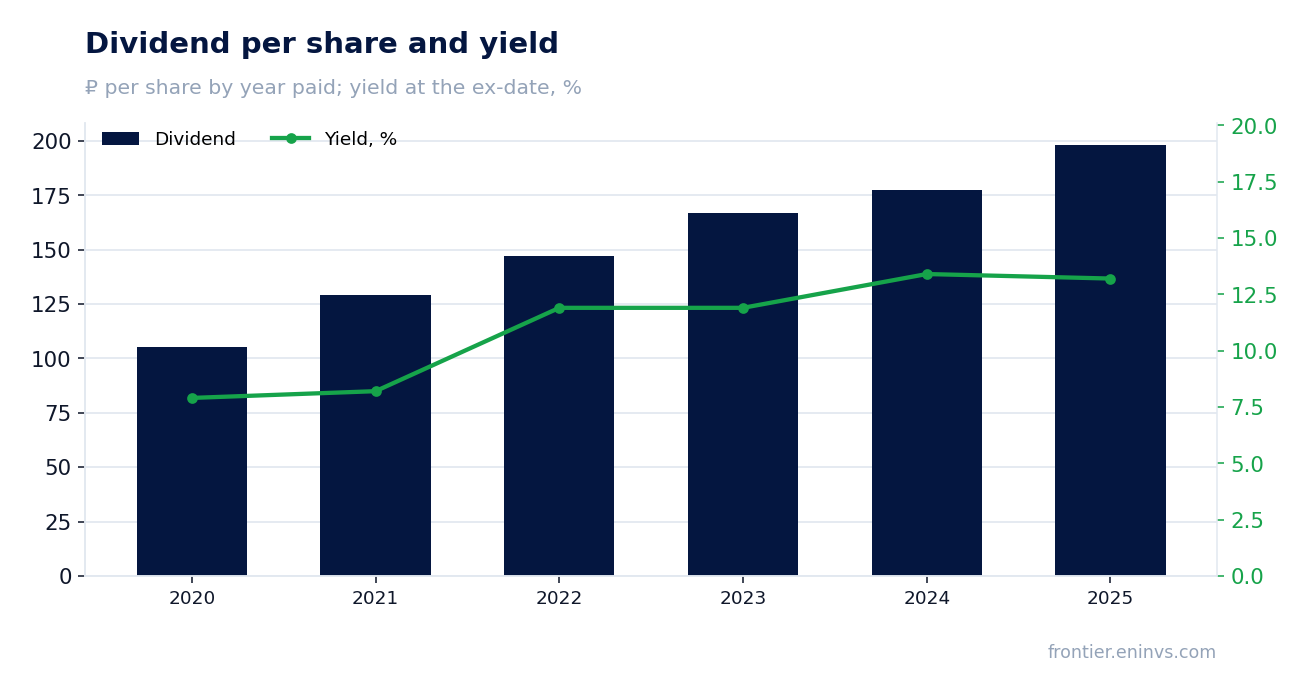
No dividends were paid over the last 12 months. However, our estimate for the current financial year (to be paid next year) is RUB 196.01 per share, giving a yield of 18.9% at the current price. This is our forecast based on a payout ratio of 0.6 of LTM profit and the number of shares; the board decides.
For comparison, in 2025, RUB 198.25 per share was paid with a yield of 13.2% at the ex-date. The current expected yield is higher, making the share attractive for income strategies. The central bank key rate is 14.0%, and the spread to it remains positive. A risk to the dividend is a further decline in net profit or an increase in capex, which could limit free cash flow.
EV/EBITDA of 0.93 is below the three-year average of 1.33, pointing to undervaluation
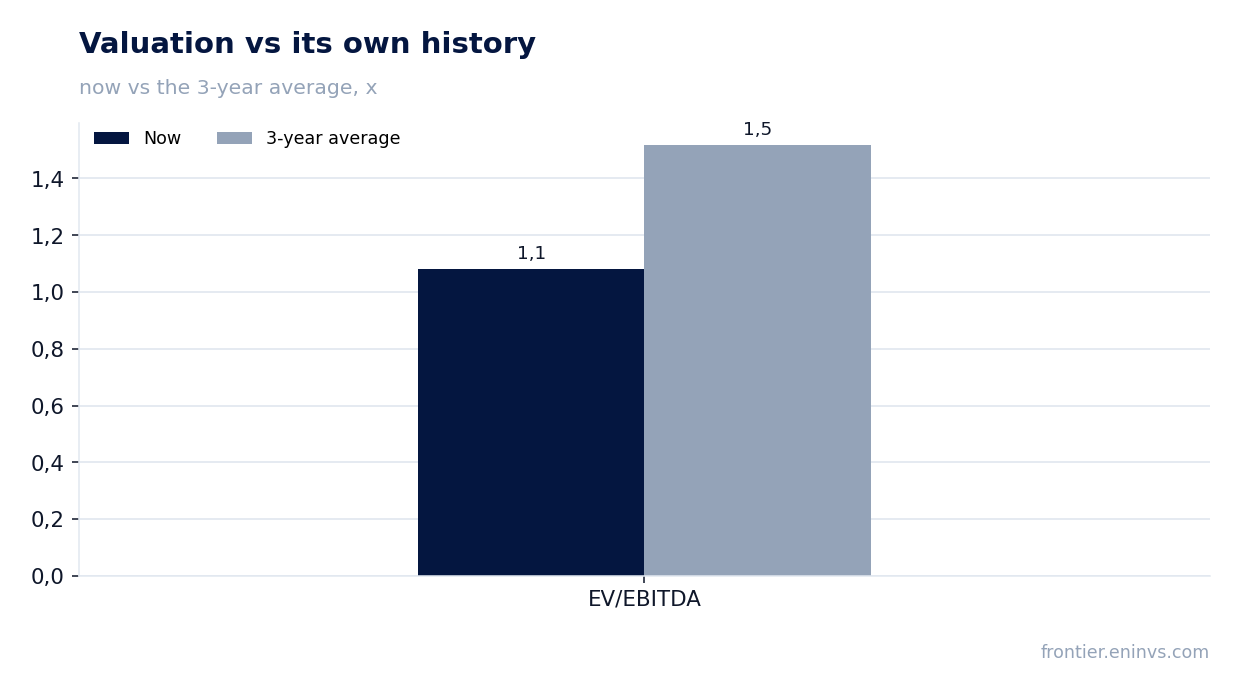
The current EV/EBITDA multiple is 0.93, below the three-year average of 1.33. This indicates that the market values the company cheaper than in recent years on average. P/E LTM is 3.17, also suggesting a low valuation.
Such low multiples may be related to expectations of lower profit or risks associated with sanctions and regulation. However, with stable cash flow and negative net debt, this valuation looks undervalued. For investors, this creates potential for share price growth if profit recovers.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 751 bn ₽ |
| P/E (LTM) | 3.2 |
| EV/EBITDA (LTM) | 0.9 |
| P/B | 0.25 |
| Net debt / EBITDA (LTM) | -0.62 |
| Operating cash flow (LTM) | 446 bn |
| ROE | 10.7% |
| EV/EBITDA, 3-year average | 1.3 |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2020 | 105.24 | 7.9% |
| 2021 | 129.09 | 8.2% |
| 2022 | 147.18 | 11.9% |
| 2023 | 166.65 | 11.9% |
| 2024 | 177.20 | 13.4% |
| 2025 | 198.25 | 13.2% |
| Our estimate, current year | 196.01 | 18.9% on the current price |
Bottom line
The report's strengths were revenue growth of 5.8% and net profit growth of 3.8%, along with maintaining negative net debt. However, EBITDA fell 5.7%, the margin declined, and free cash flow remains negative. The estimated dividend yield of 18.9% looks attractive, but the absence of payouts over the last 12 months and pressure on the margin call for caution. With an EV/EBITDA multiple of 0.93 versus the average of 1.33, the share is undervalued, but confirmation of the trend requires a recovery in profitability and cash flow.
Open the company's financial profile TRNFP →
See also: market overview · valuation map · stock screeners