Tattelecom: profit grows faster than revenue, but the portal's model sees 7% downside
On August 15, 2026, Tattelecom reported H1 2026 results: revenue grew 17.6% to RUB 13.4 bn, EBITDA rose 24.5% to RUB 3.87 bn, and net profit increased 33.1% to RUB 2.6 bn. The shares trade at P/E of 4.9 and EV/EBITDA of 3.3, notably below its own three-year average of 4.5, with a dividend yield of 9.9% versus our fair yield of 7.0%. However, the portal's model implies 7% downside, making the shares rather attractive, but with caveats.
Key takeaways
— Net profit for the half-year grew 33.1% – faster than revenue and EBITDA
— EBITDA margin expanded to 28.8% from 27.2% a year earlier
— Net debt is negative: minus RUB 939.9 mln, with a net debt/EBITDA ratio of minus 0.28 over 12 months
— Dividend yield of 9.9% over the last 12 months – above our fair yield of 7.0%
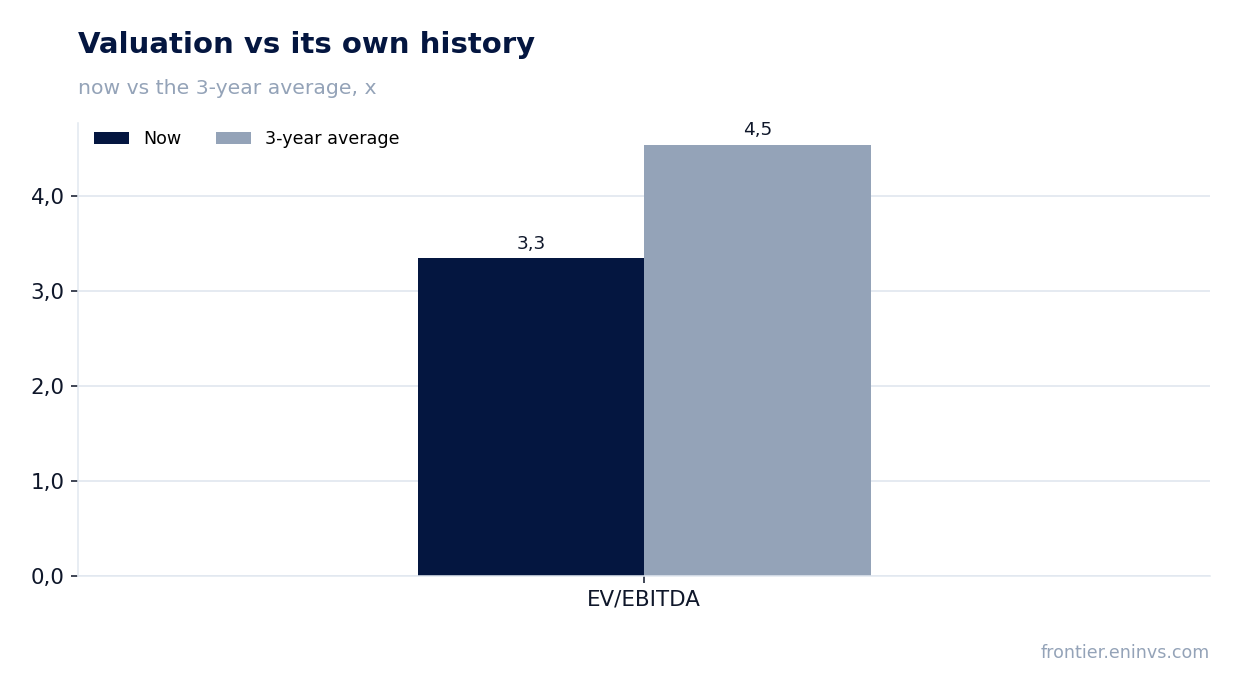
— EV/EBITDA multiple of 3.3 – 27% below its own three-year average
— The portal's model implies 7% downside for the shares
— The shares are held in the RU AI conviction (Claude) strategy on the portal
Attractiveness
Key figures, RUB bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 5.95 | 7.00 | +17.6% |
| EBITDA | 1.62 | 2.01 | +24.5% |
| Operating profit | 0.85 | 1.24 | +45.0% |
| Net profit | 1.02 | 1.35 | +33.1% |
| Operating cash flow | 1.32 | 1.47 | +11.9% |
| Capex | 0.59 | 0.76 | +30.1% |
| EBITDA margin | 27.2% | 28.8% | +1.6 pp |
| Net margin | 17.1% | 19.3% | +2.2 pp |
Net profit for the half-year grew 33.1% – faster than revenue and EBITDA
In H1 2026, Tattelecom's net profit reached RUB 2.6 bn, up 33.1% year-on-year. Revenue for the same period grew 17.6% to RUB 13.4 bn, while EBITDA rose 24.5% to RUB 3.87 bn. Thus, profit is growing faster than revenue and operating profit, indicating improved efficiency or one-off factors.
Net profit growth outpacing EBITDA suggests lower depreciation or interest expenses, or one-off gains. The report does not disclose the reasons for this outperformance, but it is a positive signal for shareholders as it increases the base for dividends.
EBITDA margin expanded to 28.8% from 27.2% a year earlier
EBITDA margin for H1 2026 was 28.8%, up from 27.2% a year earlier. The 1.6 percentage point expansion is the result of EBITDA growing faster than revenue: EBITDA rose 24.5% against revenue growth of 17.6%.
The margin improvement may be due to cost control or a shift in revenue mix toward higher-margin services. Net margin also increased to 19.3% from 17.1%, confirming improved business efficiency.
Net debt is negative: minus RUB 939.9 mln, with a net debt/EBITDA ratio of minus 0.28 over 12 months
As of the latest balance sheet date, Tattelecom's net debt was minus RUB 939.9 mln, meaning cash exceeds debt. The net debt/EBITDA ratio over the last 12 months is minus 0.28, indicating financial stability.
Over the last 12 months, net debt decreased by RUB 1.4 bn, and compared to the previous reporting date, by RUB 6.5 bn. This trend reflects strong operating cash flow, which amounted to RUB 3.1 bn over 12 months.
Dividend yield of 9.9% over the last 12 months – above our fair yield of 7.0%
Over the last 12 months, Tattelecom paid dividends of RUB 0.0573 per share, providing a yield of 9.9%. Our model estimates the next payment at RUB 0.06 per share, implying a forward yield of 9.9% as well.
The fair yield for this stock, in our view, is 7.0%. The current yield is notably higher, making the shares attractive for income-oriented investors. The payout ratio is 0.27 of profit, leaving ample room to maintain or increase dividends.
EV/EBITDA multiple of 3.3 – 27% below its own three-year average
The current EV/EBITDA multiple is 3.3 – 27% below its own three-year average of 4.5. P/E LTM stands at 4.9, also indicating undervaluation relative to historical levels.
The low valuation is combined with strong financials: return on equity is 17.6%, and operating cash flow over 12 months is RUB 3.1 bn. This combination makes the stock fundamentally attractive, ignoring the portal model's signal.
The portal's model implies 7% downside for the shares
Our fundamental value-creation model, based on EBITDA growth and target multiple, shows that the share's potential relative to its fair value is minus 7%. This means that, on the portal's model, the shares trade slightly above the estimated fair price.
This signal contradicts the low multiples and high dividend yield. The discrepancy may be due to conservative assumptions about future growth or the target multiple. Nevertheless, we factor this into our attractiveness assessment.
The shares are held in the RU AI conviction (Claude) strategy on the portal
Tattelecom is currently held in the 'RU AI conviction (Claude)' strategy on our portal. This means the stock meets the selection criteria of that strategy, but it is not an argument for a recommendation.
Inclusion in the strategy reflects certain quantitative and qualitative characteristics that the strategy's model finds attractive. However, the decision to buy or sell should be made considering all factors, including the portal model's valuation and market risks.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 12.2 bn ₽ |
| P/E (LTM) | 4.9 |
| EV/EBITDA (LTM) | 3.3 |
| P/B | 0.87 |
| Net debt / EBITDA (LTM) | -0.28 |
| Operating cash flow (LTM) | 3.10 bn |
| ROE | 17.6% |
| Dividend yield (12m) | 9.8% |
| EV/EBITDA, 3-year average | 4.5 |
Bottom line
Tattelecom reported H1 2026 with strong profit growth (+33.1%), margin expansion, and negative net debt. The dividend yield of 9.9% is well above our fair yield of 7.0%, and multiples are below their own historical averages. However, the portal's model implies 7% downside, which tempers the attractiveness assessment. Overall, the shares look rather attractive, but investors should consider the model's signal and potential growth slowdown risks.
Open the company's financial profile TTLK →
See also: market overview · valuation map · stock screeners