VK company: revenue up 21%, but the RUB 6.2 bn EBITDA rests on advertising, not on the new projects
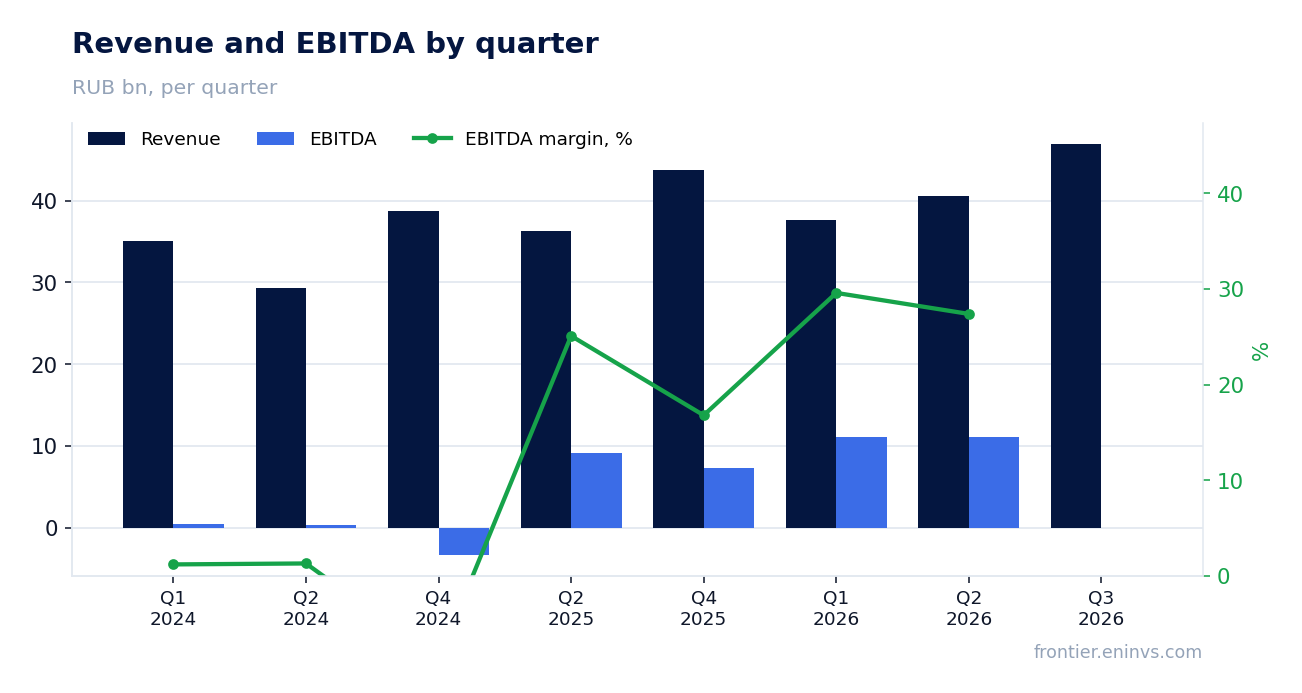
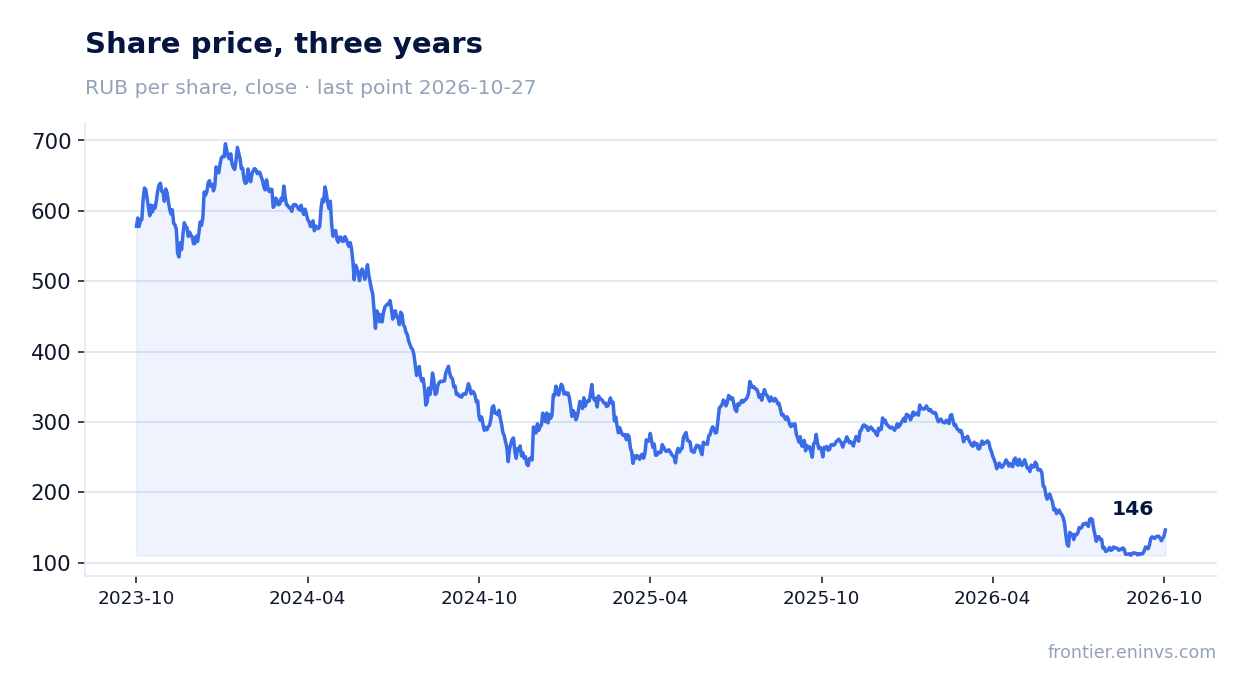
On 28 October VK company released unaudited results for the third quarter and the first nine months of 2026. Quarterly revenue rose 21% to RUB 47.0 bn and EBITDA 22% to RUB 6.2 bn, while nine-month revenue reached RUB 128.0 bn (+15%) with EBITDA of RUB 20.2 bn (+30%). Net debt at end-September stood at RUB 73.3 bn, net debt/EBITDA over the last twelve months at 2.23, and on the portal's model the share trades 62% below fair value. The stock looks rather attractive: an EV/EBITDA of 5.15 is below its own history and leverage sits inside the target range, but growth in the new projects is not yet converting into profit.
Key takeaways
— Quarterly revenue rose 21% to RUB 47.0 bn, with online advertising supplying almost two-thirds
— Quarterly EBITDA of RUB 6.2 bn grew 22%, but the nine-month margin is only 16%
— Social platforms delivered RUB 18.5 bn of nine-month EBITDA at a 20% margin
— VK Tech grew 35%, but its EBITDA margin fell to 12%
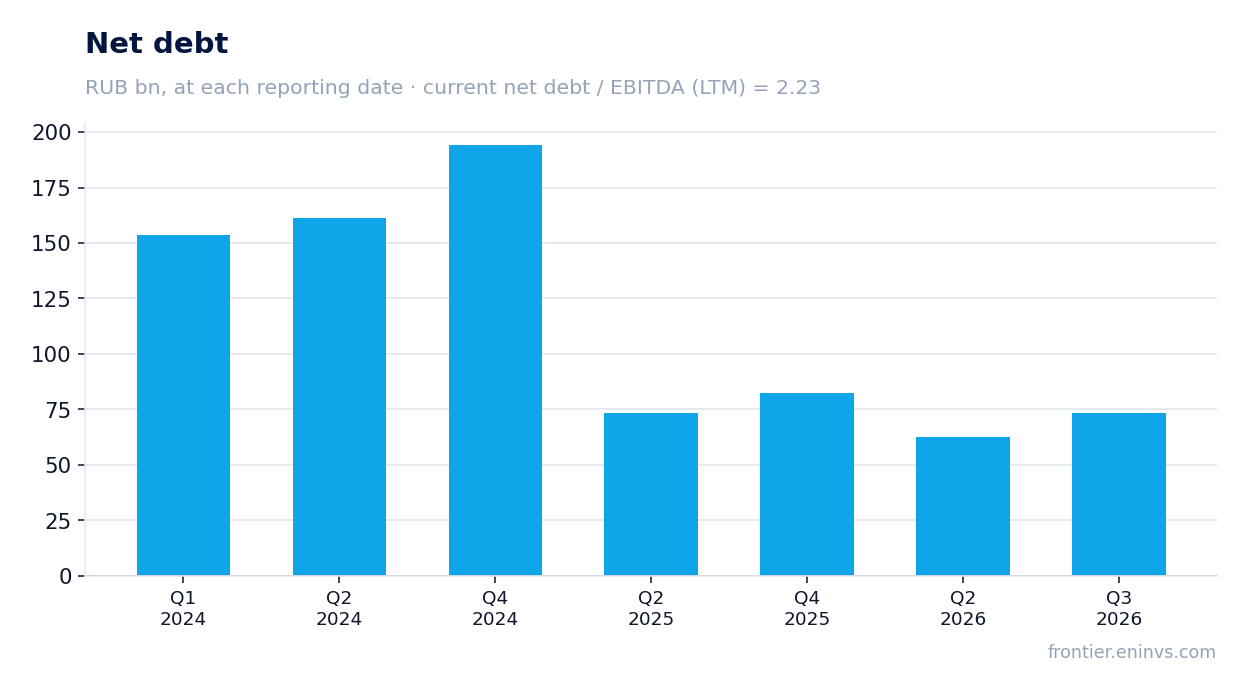
— Net debt of RUB 73.3 bn equals 2.23x trailing-twelve-month EBITDA, inside the 2–3x target
— Nine-month operating cash flow reached RUB 17.4 bn against a negative figure a year earlier
— EV/EBITDA of 5.15 and the portal model imply 62% upside to fair value
Attractiveness
Key figures, RUB bn
| Metric | — | Q3 2026 | Change |
|---|---|---|---|
| Revenue | — | 47.0 | — |
| Operating cash flow | — | 1.99 | — |
Quarterly revenue rose 21% to RUB 47.0 bn, with online advertising supplying almost two-thirds
In the third quarter of 2026 VK company's revenue reached RUB 47.0 bn, 21% more than a year earlier. Online advertising brought in RUB 28.2 bn (+18%), roughly 60% of the total. Within advertising, in-stream video grew fastest, up 48% to RUB 2.7 bn, while large-business advertising added 29% to RUB 18.0 bn.
Over nine months revenue reached RUB 128.0 bn (+15%), of which online advertising supplied RUB 76.8 bn (+11%). In-stream video rose 44% to RUB 7.6 bn over nine months. Social commerce brought in RUB 2.1 bn over nine months, 65% more than in all of 2025, and in the third quarter its revenue rose 81% quarter on quarter to RUB 1.2 bn.
The new projects remain small relative to the group. The MAX messenger generated more than RUB 700 m of revenue from July to October, VK Tech RUB 14.4 bn over nine months (+35%), and educational services RUB 6.8 bn (+26%). Revenue growth rests on advertising rather than on these businesses, which limits how quickly they can change the overall picture.
Quarterly EBITDA of RUB 6.2 bn grew 22%, but the nine-month margin is only 16%
Third-quarter EBITDA reached RUB 6.2 bn, 22% more than a year earlier. Over nine months the figure reached RUB 20.2 bn (+30%) at a 16% EBITDA margin, 2 pp above the nine months of 2025. The company reiterated its 2026 EBITDA guidance of more than RUB 24 bn.
Every segment contributed to the margin: social platforms at 20%, educational technology at 13%, VK Tech at 12%, ecosystem services at 7%. In absolute terms the picture is uneven: the ecosystem services segment generated RUB 21.5 bn of revenue but only RUB 1.6 bn of EBITDA, while unallocated costs and eliminations absorbed RUB 2.6 bn.
Quarterly EBITDA of RUB 6.2 bn is about 13% of quarterly revenue, against a 16% nine-month margin. The gap reflects a higher share of advertising and social platforms in the first half, with spending on new projects spread across the year. Margin resilience will depend on how quickly MAX and VK Tech start covering their costs.
Social platforms delivered RUB 18.5 bn of nine-month EBITDA at a 20% margin
The social platforms and media content segment posted nine-month revenue of RUB 91.3 bn (+18%) and EBITDA of RUB 18.5 bn (+19%) at a 20% margin. That is 71% of group revenue and 92% of group EBITDA, so almost all of the company's profit is still generated here.
The main driver is VKontakte: its revenue grew 21% year on year, helped by in-stream video and social commerce. VKontakte's Russian audience is 93.2 m monthly and 64.2 m daily. MAX has reached 109 m monthly users, but its July–October revenue is only just above RUB 700 m, so the messenger is still a cost line rather than a profit source.
VK Video grew to 82.1 m monthly users in Russia, viewing time rose 45% and app installs 73% to 157 m. These metrics support advertising revenue, but video monetisation runs through in-stream, which generated RUB 7.6 bn over nine months, about 6% of group revenue.
VK Tech grew 35%, but its EBITDA margin fell to 12%
The business technology segment (VK Tech) raised nine-month revenue 35% to RUB 14.4 bn and EBITDA 21% to RUB 1.8 bn. The EBITDA margin was 12% against 14% a year earlier: revenue is outpacing profit because segment operating costs rose 37%.
The drivers are VK WorkSpace productivity services, with revenue up 61%, and AI solutions, with revenue of RUB 1 bn. Recurring revenue rose 52% and reached 86% of VK Tech's total, while the client count hit 38,000 (+42%). That is a quality base, but for now it consumes more cost than it generates in profit.
Educational technology showed the best margin dynamics: EBITDA rose 70% to RUB 0.9 bn at a 13% margin (+3 pp). The segment is small, with RUB 6.8 bn of revenue, but it is already profitable and growing faster than the group.
Net debt of RUB 73.3 bn equals 2.23x trailing-twelve-month EBITDA, inside the 2–3x target
Net debt at 30 September 2026 stood at RUB 73.3 bn. It rose from RUB 62.8 bn at 30 June (+RUB 10.5 bn), while over twelve months from 30 June 2025 it was unchanged, at RUB 73.3 bn at both ends. Net debt to trailing-twelve-month EBITDA is 2.23, or 2.7x on the company's own basis against 3.6x at end-2025; the difference reflects different calculation bases, but both sit inside the 2–3x target range.
The company reiterated its target of 2–3x net debt/EBITDA for the end of 2026. In September subsidiary Mail.Ru Finance placed RUB 5 bn of bonds and repaid a RUB 15 bn issue, so debt is being refinanced rather than increased. In April VK sold a 25% stake in Tochka for RUB 21.2 bn, a one-off inflow that supported the debt reduction.
EV/EBITDA over the last twelve months is 5.15 on a market capitalisation of RUB 86.7 bn. That is below where the company traded in previous years and reflects both EBITDA growth and the market's caution about the advertising cycle and spending on new projects.
Nine-month operating cash flow reached RUB 17.4 bn against a negative figure a year earlier
Net operating cash flow for the first nine months of 2026 was RUB 17.4 bn, against a negative figure in the same period of 2025. In the third quarter the flow was positive at RUB 1.992 bn. That is an important shift: the company is starting to turn EBITDA growth into cash rather than only reported profit.
The improvement coincided with EBITDA rising to RUB 20.2 bn over nine months and with a one-off RUB 21.2 bn inflow from the April sale of the Tochka stake. Without that inflow the cash flow would have been smaller, but it would still have been positive, since EBITDA grew 30%.
The company did not disclose capital expenditure in the press release, so free cash flow cannot be assessed. For an advertising and technology business that is a material gap: without capex one cannot tell how much of the RUB 17.4 bn remains after investment in VK Video, MAX and infrastructure.
EV/EBITDA of 5.15 and the portal model imply 62% upside to fair value
With a market capitalisation of RUB 86.7 bn and net debt of RUB 73.3 bn, EV/EBITDA over the last twelve months is 5.15. That is below where the company traded in previous years, when the market priced its growth more richly. On the portal's model, which sets EBITDA growth against a target multiple, the share trades 62% below fair value.
The valuation rests on EBITDA resilience. If the company's guidance of more than RUB 24 bn for 2026 is met, the multiple will stay low even at the current price. But if spending on MAX and VK Tech keeps outpacing revenue, EBITDA may fall short of the target, and the discount to fair value would prove justified.
The company's ROE is 0.02%, so return on capital is close to zero. That reflects a high asset base and one-off items rather than operational weakness, but for an investor it means earnings-based valuation does not yet work: the market is paying for EBITDA and for expectations about the advertising market.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 86.7 bn ₽ |
| EV/EBITDA (LTM) | 5.1 |
| Net debt / EBITDA (LTM) | 2.23 |
| ROE | 0.0% |
Bottom line
The strong part of the report is revenue and EBITDA: the quarter delivered RUB 47.0 bn and RUB 6.2 bn respectively, and nine-month EBITDA rose 30% at a 16% margin. The weak part is structure: almost all profit still comes from social platforms and advertising, while MAX and VK Tech are increasing costs faster than revenue. The RUB 21.2 bn inflow from the Tochka stake sale was one-off and supported both debt and cash flow. The key question for a holder is whether the company can hold the 16% margin and meet its EBITDA guidance of more than RUB 24 bn without adding debt. At an EV/EBITDA of 5.15 and 62% upside on the portal model, the share looks rather attractive.
Open the company's financial profile VKCO →
See also: market overview · valuation map · stock screeners