VI.ru: a RUB 6-7 dividend is on the way, and the stock trades at six years of earnings
*Updated 5 October: we lowered our estimate of the next dividend to RUB 6-7 and of the annual payout to RUB 9-10, lowered the entry threshold to RUB 70, and added the risk of an overhang of shares from the incentive programme. For reference: on 5 October, the day the idea was published, the stock rose 5% to RUB 76.8, while the MOEX Russia Index gained 1.8%. Calculations in the text are based on the price of RUB 73.15 as of 2 October.*
VI.ru is the holding company of the online store VseInstrumenty.ru, Russia's largest online retailer of tools, equipment and construction and renovation goods. Three quarters of revenue comes from companies and entrepreneurs. The stock listed in July 2024 at RUB 200 and now trades at RUB 73.15. On 1 October the operating subsidiary decided to transfer RUB 3.55 bn to the holding company, and this sets the size of the next dividend.
The stock is attractive as a dividend play when bought at around RUB 70 or below. By our estimate, the next payout will be RUB 6-7 per share, or 8-9.5% of the current price. The company trades at six years of earnings, and net cash accounts for 18% of its market capitalisation. Fair value under three approaches is RUB 84-94. The dividend announcement itself will not lift the price for long: on the day the previous payout was announced the stock rose 2%, and on the record date it fell by more than the dividend.
- Cash for the payout is already being transferred: RUB 3.55 bn from the subsidiary, or up to RUB 7.1 per share.
- No debt and low capex, so the company can pay out almost all of its earnings.
- Earnings are growing on efficiency and lower interest costs, not on sales.
- Six times earnings and 2.6x EBITDA is cheap even after adjusting for a weak market.
- The building materials market is shrinking, and retail customers are moving to marketplaces.
Cash for the payout is already being transferred: RUB 3.55 bn from the subsidiary
The listed VI.ru sells nothing itself: the entire business and its cash sit in VseInstrumenty.ru LLC. So before each dividend the subsidiary first pays the holding company, and the holding company then pays shareholders. [On 1 October](https://smart-lab.ru/blog/news/1358031.php) the subsidiary decided to pay RUB 3.549 bn out of earnings for 2025 and 1H2026. The money will arrive within 60 days.
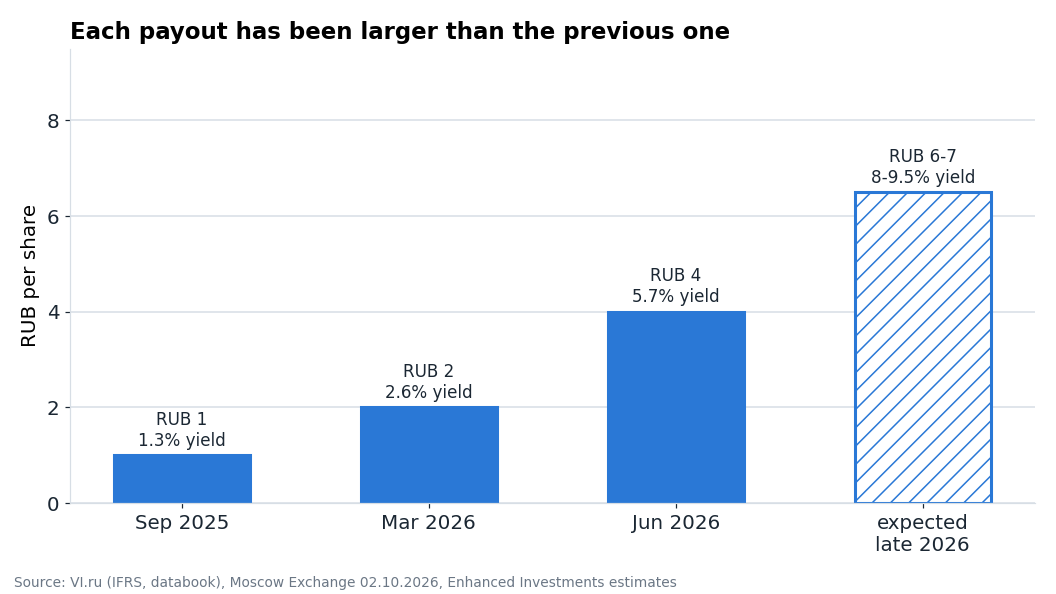
In previous rounds the holding company passed almost everything it received on to shareholders. In June 2025 the subsidiary paid the holding company RUB 525 mn, and in September shareholders received RUB 1 per share, or RUB 500 mn. In December 2025 the holding company received RUB 1.06 bn and in March 2026 paid RUB 2 per share, or RUB 1 bn. Spread over 500 mn shares, RUB 3.55 bn gives RUB 7.1. The holding company will probably keep part of the amount for its own expenses, so we expect RUB 6-7.
[On 29 September](https://www.retail.ru/news/sovet-direktorov-vseinstrumenty-ru-odobril-vykup-aktsiy-obemom-do-500-mln-rubley-29-sentyabrya-2026-282700/) the board approved a share buyback of RUB 500 mn from November 2026 until the end of 2027. The subsidiary itself will carry out the buyback, and the shares will go to the employee incentive programme. The company's CFO separately said that the buyback does not cancel dividends. Therefore the buyback does not reduce the amount going to the holding company and does not affect the next payout. We expect the board meeting on the dividend in late October or November, and the record date before the end of the year.
No debt and low capex, so the company can pay out almost all of its earnings
Under its [dividend policy](https://ir.vseinstrumenti.ru/dividendnaya-politika) the company pays at least 50% of IFRS net income as long as net debt does not exceed 3x EBITDA. In practice it pays more: for 2025 shareholders received RUB 6 per share, or 89% of net income. A payout of RUB 6-7 now would be 115-135% of 1H2026 net income.
Such a payout looks more like bringing forward part of the dividends for 2026 than a new norm. Under the budget package, from 2027 dividends will fall under the progressive personal income tax scale of 13-22%, so shareholders are better off receiving the money in 2026. In that case the payout in 1H2027 is likely to be smaller than usual. For the next 12 months we assume RUB 9-10 per share.
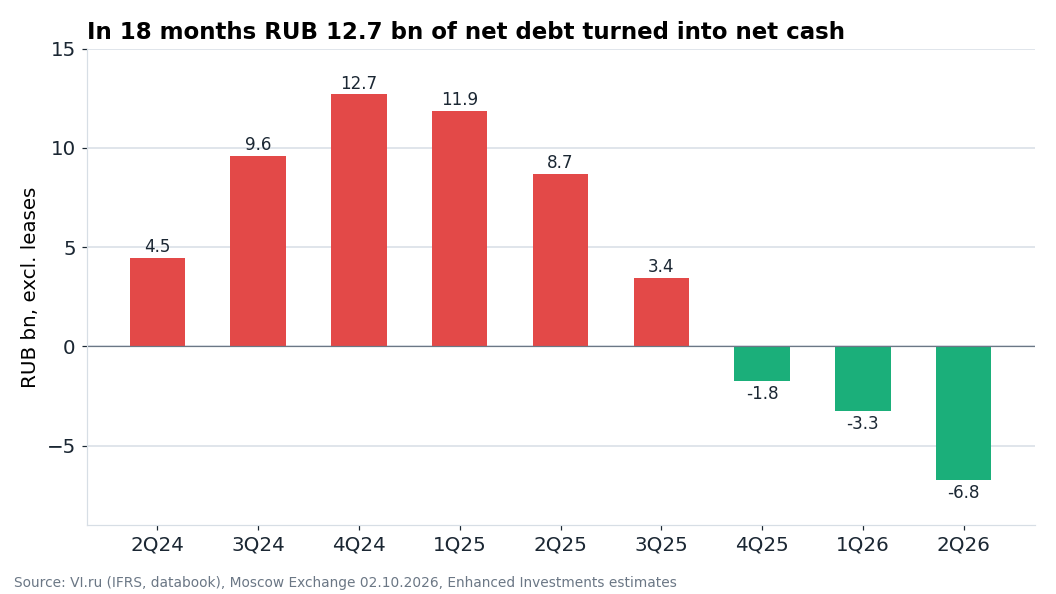
The company can afford this because the debt is gone. At the end of 2024 loans and bonds exceeded cash by RUB 12.7 bn. By the end of June 2026 cash exceeded debt by RUB 6.75 bn. Capex is small: RUB 0.4 bn for the half-year and RUB 1.1 bn for 2025. The company mostly leases its warehouses and pick-up points. Lease liabilities are RUB 20.8 bn; including them, net debt equals 0.74x annual EBITDA.
There is a caveat. Free cash flow in 2025, RUB 14.1 bn, was heavily inflated by a reduction in inventories from RUB 29.2 bn to RUB 24.4 bn. This cannot be repeated. By our estimate, normalised cash flow is close to annual net income, i.e. RUB 6 bn. On average this allows a payout of about RUB 12 per share per year, but no more without increasing debt. Over the next 12 months the payout will be lower because of the shift in timing. Management targets debt of zero to 1x annual EBITDA, so there is headroom for payouts.
Earnings are growing on efficiency and lower interest costs, not on sales
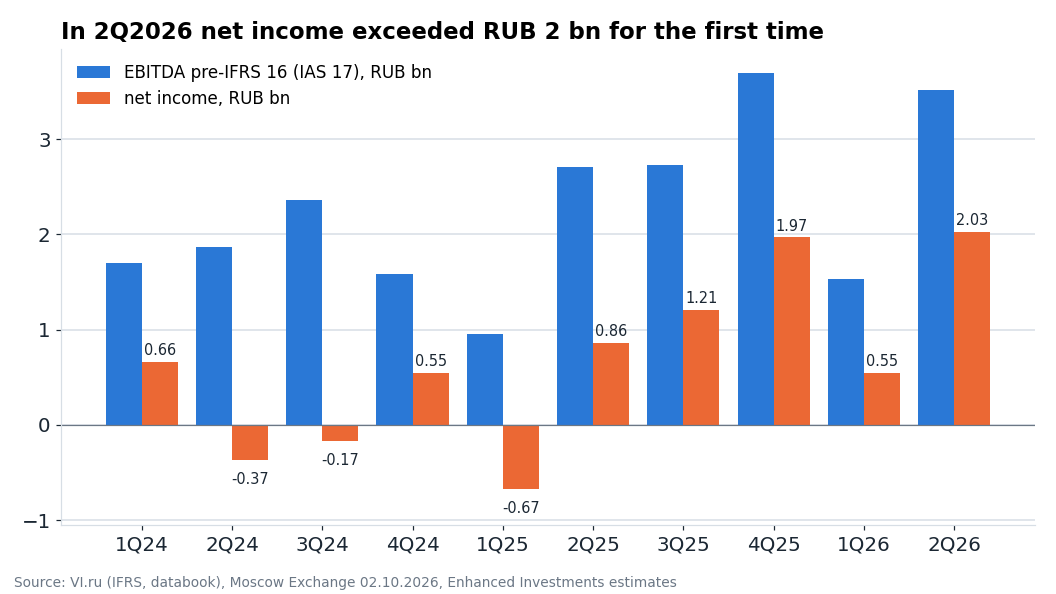
In 2Q2026 net income was RUB 2.03 bn versus RUB 0.86 bn a year earlier. EBITDA before IFRS 16, i.e. after lease payments, grew 30% to RUB 3.52 bn. Revenue rose 9.7% to RUB 50.6 bn; for the half-year growth was 3.2%.
Earnings growth came mainly from cost savings and interest. Gross margin in 2Q2026 was 33.4% versus about 30% in 2024. Net finance costs for the half-year fell from RUB 3.3 bn to RUB 1.9 bn thanks to debt repayment. The company is shrinking its network: 1,076 pick-up points versus 1,181 a year earlier, and fewer warehouses. Management itself has called 2026 a year of efficiency rather than rapid growth.
Net income guidance for 2026 is RUB 4.5-6.5 bn. In 1H2026 the company earned RUB 2.58 bn, and its second half is seasonally stronger: in 2025 it brought RUB 3.18 bn versus RUB 0.19 bn in the first. 1H2026 net income includes RUB 0.58 bn of deferred tax; without it, net income is RUB 2 bn. Our estimate for the year is RUB 6 bn. The company's 2028 target (RUB 4.9-6.8 bn) has almost been reached already, so we do not assume rapid earnings growth from here.
Six times earnings and 2.6x EBITDA is cheap even after adjusting for a weak market
Market capitalisation is RUB 36.6 bn. Over the last 12 months (July 2025 to June 2026) the company earned RUB 5.76 bn, for a P/E of 6.4. EBITDA before IFRS 16 for the same period was RUB 11.5 bn; taking net cash into account, EV/EBITDA is 2.6. Including leases under IFRS 16 it is 2.7.
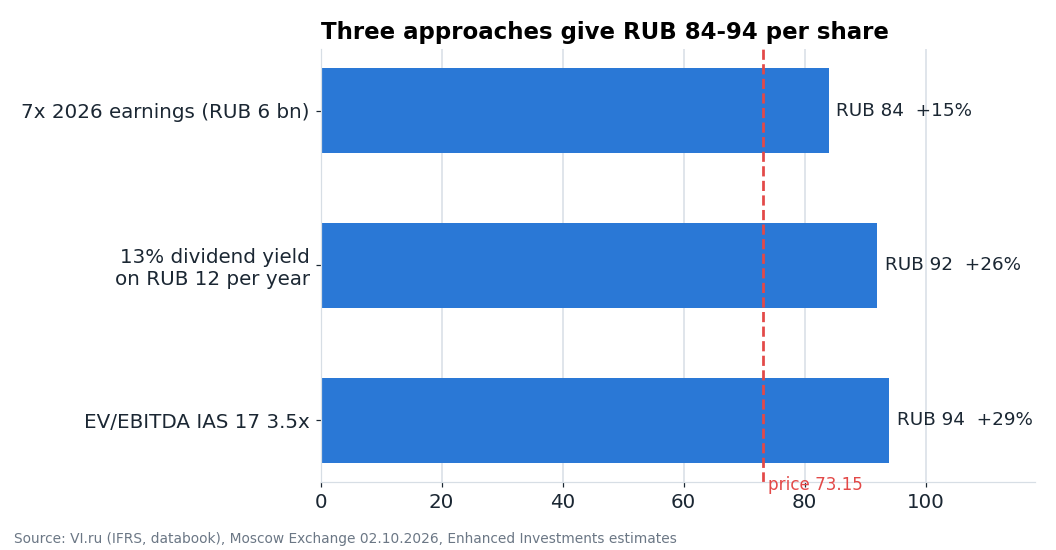
We estimate fair value in three ways:
- Seven times 2026 earnings. With net income of RUB 6 bn this is RUB 84 per share.
- A 13% dividend yield. With a payout of RUB 12 per year, i.e. all normalised earnings, this is RUB 92. We take a yield below the CBR key rate, anticipating rate cuts, but above the yield of large dividend stocks because of the small free float.
- EV/EBITDA of 3.5x under IAS 17. This gives RUB 94.
The range is RUB 84-94, 15-29% above the current price. According to the company's IR, brokers set targets of RUB 95-124 after the half-year results.
A dividend announcement does not lift the price for long
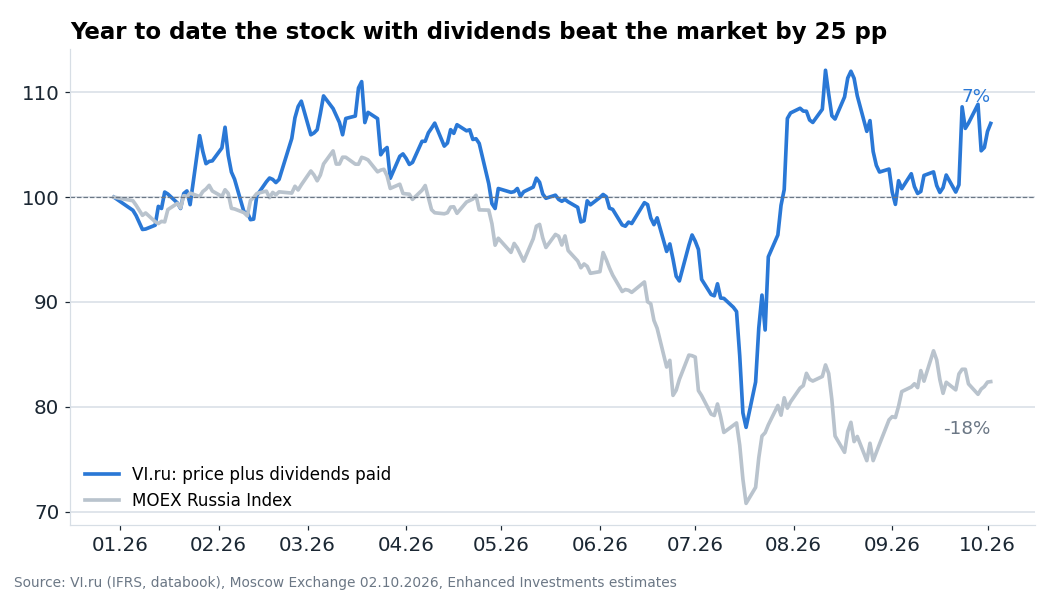
On 30 April the board recommended RUB 4 per share, 5.5% of the price. That day the stock rose 2% while the index gained 0.7%, and then it went sideways. On the record date, 22 June, it fell 9%: 5.7% was due to the dividend and the rest to the market, which fell 4% that day. After the 1 October disclosure the stock gained about 2%.
At the same time, dividends have noticeably supported the stock. Since the start of 2026 the price has barely changed, but together with RUB 6 of payouts shareholders earned 7%. The MOEX Russia Index lost 18% over the same period. We expect the next payout to follow the same pattern: a gain of a few percent before the record date, then a drop of roughly the size of the dividend. A rerating above RUB 80 will come not from the dividends themselves but from confirmation of net income of around RUB 6 bn per year.
For dividends, the stock is worth buying at around RUB 70 or below
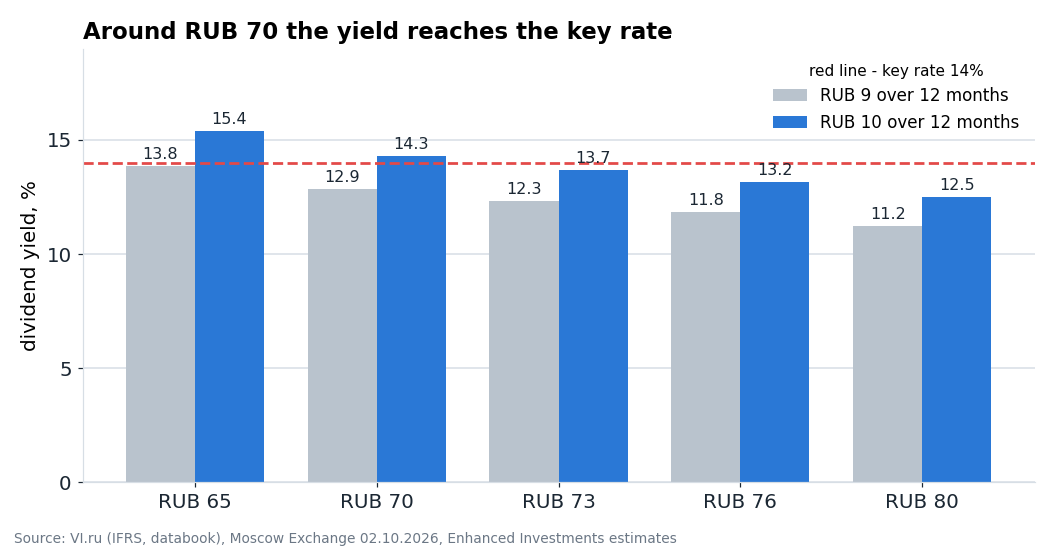
We expect RUB 9-10 of dividends over the next 12 months. At a price of RUB 73 that is 12-14% versus a key rate of 14%, i.e. a yield in line with the rate, not above it. When buying at around RUB 70 it will be 13-14%, and with the expected rate cuts a risk premium appears. Above that level the stock is worth holding for earnings growth and the fair value of RUB 84-94, not for the payouts.
The building materials market is shrinking, and retail customers are moving to marketplaces
- Market. According to [INFOLine data](https://www.retail.ru/news/rossiyskiy-rynok-tovarov-dlya-doma-i-remonta-nachal-vosstanavlivatsya-posle-pade-28-maya-2026-278244/), in 1Q2026 the home and renovation goods market contracted by 8%, and B2B by 10.5%. According to Rosstat, housing completions in January-August 2026 fell 14%, and individual housing construction 23.5%.
- Retail customers. There are 3.48 mn active B2C customers versus 4.01 mn a year earlier, and B2C orders are down 3%. Marketplaces grew sales of renovation goods by 42% in 2025. The company's growth relies on large corporate customers.
- Private labels. Their share of revenue fell from 14.1% to 10.7%, although the company targets more than 20% by 2030. This was one of the pillars of the margin.
- Free float and liquidity. About 12% of shares are in free float, and the main shareholder owns 83.9%. Average turnover is about RUB 90 mn per day, so it is hard for a large investor to get in and out quickly.
- Supply overhang. According to IFRS, at the end of 2025 about 13 mn shares, 2.6% of capital, remained locked up in the incentive programme launched for the IPO. The programme runs for roughly two years after the IPO, and a significant part of these shares may become available for sale in the coming months. The buyback starting in November may absorb part of this volume.
- Share-based compensation. In 2025 it cost the company RUB 0.83 bn. The company excludes this expense from EBITDA; we keep it in our valuation.
What to watch
- 23 October – CBR key rate meeting;
- by 30 October – 9M operating results: B2B growth and B2C dynamics;
- late October or November – board decision on the dividend and the record date;
- 19 November – 9M IFRS results;
- from 1 November – progress of the share buyback.
Financials, multiples and dividend history are available on the VI.ru card on the Enhanced Investments portal.
Open the company's financial profile VSEH →
See also: market overview · valuation map · stock screeners