X5 Retail: revenue grows 11.3% but quarterly profit undisclosed – dividend story underpins valuation
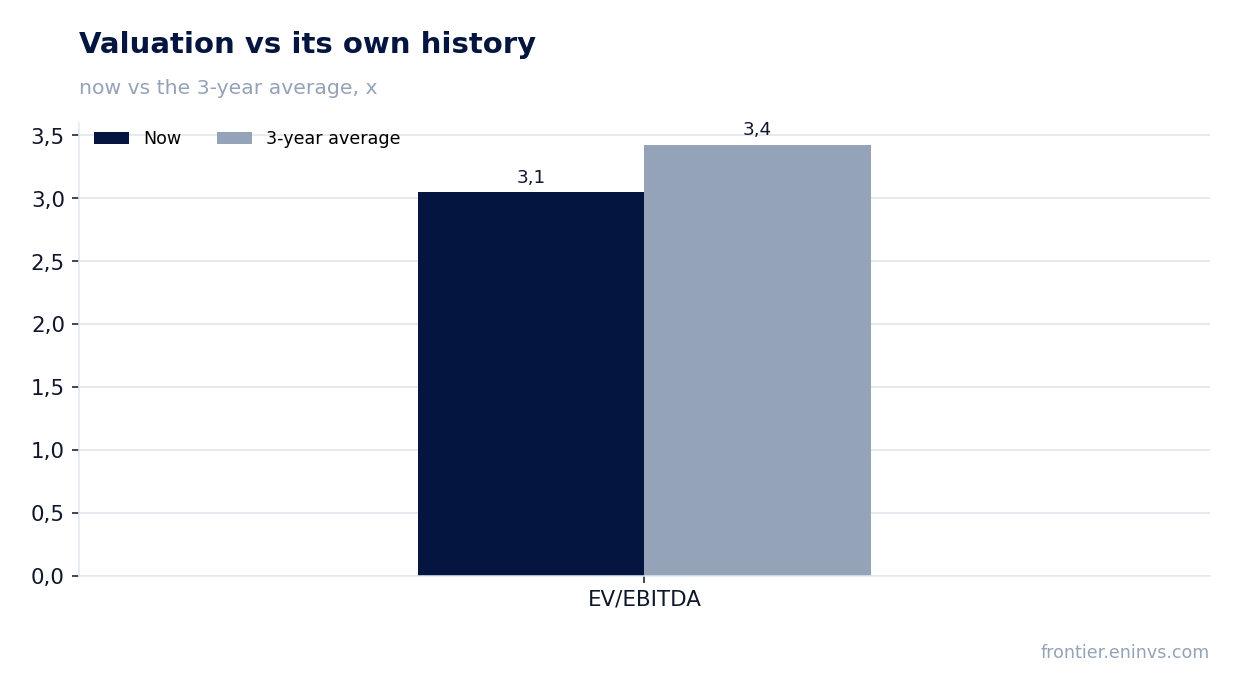
On 30 September 2026, X5 Retail released its third-quarter 2026 results. Revenue reached RUB 1,311.0 bn, up 11.3% year on year, but EBITDA and net profit for the reported quarter were not disclosed. Over the trailing twelve months, revenue amounted to RUB 5,029.5 bn, net profit to RUB 67.9 bn, and the dividend yield on last year's payouts stands at 26.2%. At the current price the share looks attractive: the EV/EBITDA multiple of 3.1 is below its own three-year average of 3.4, and the dividend yield exceeds the fair level of 22.5%.
Key takeaways
— Q3 revenue grew 11.3% year on year, but the pace decelerated from 20.7% a year earlier
— EBITDA and net profit for Q3 were not disclosed, so the margin for the reported period cannot be assessed
— Over the trailing twelve months, net profit reached RUB 67.9 bn on revenue of RUB 5,029.5 bn
— Dividends paid over the last year were RUB 613 per share, a 26.2% yield versus the 22.5% we consider fair
— Our estimate for the current financial year's dividend is RUB 239.16 per share, or a 10.2% yield on the current price
— Leverage on the latest balance sheet is 0.87 net debt to LTM EBITDA, a moderate level
— EV/EBITDA of 3.1 is below its own three-year average of 3.4, and the portal model implies 43% upside to fair value
Attractiveness
Key figures, RUB bn
| Metric | — | Q3 2026 | Change |
|---|---|---|---|
| Revenue | — | 1 311 | — |
Q3 revenue grew 11.3% year on year, but the pace decelerated from 20.7% a year earlier
Q3 2026 revenue reached RUB 1,311.0 bn, up 11.3% from the same quarter a year earlier. This is a deceleration from the 20.7% growth in Q1 2025 and from 11.3% in Q1 2026. The slowdown in revenue growth has been observed since early 2025.
Over the trailing twelve months, revenue amounted to RUB 5,029.5 bn, reflecting the scale of the business. The company did not disclose which factors drove the slowdown in Q3. Without additional data, one can only note that growth remains in double digits but is decelerating.
For an investor, it is important that the revenue slowdown is not accompanied by disclosed quarterly margins. This limits the assessment of operating efficiency in the reported period.
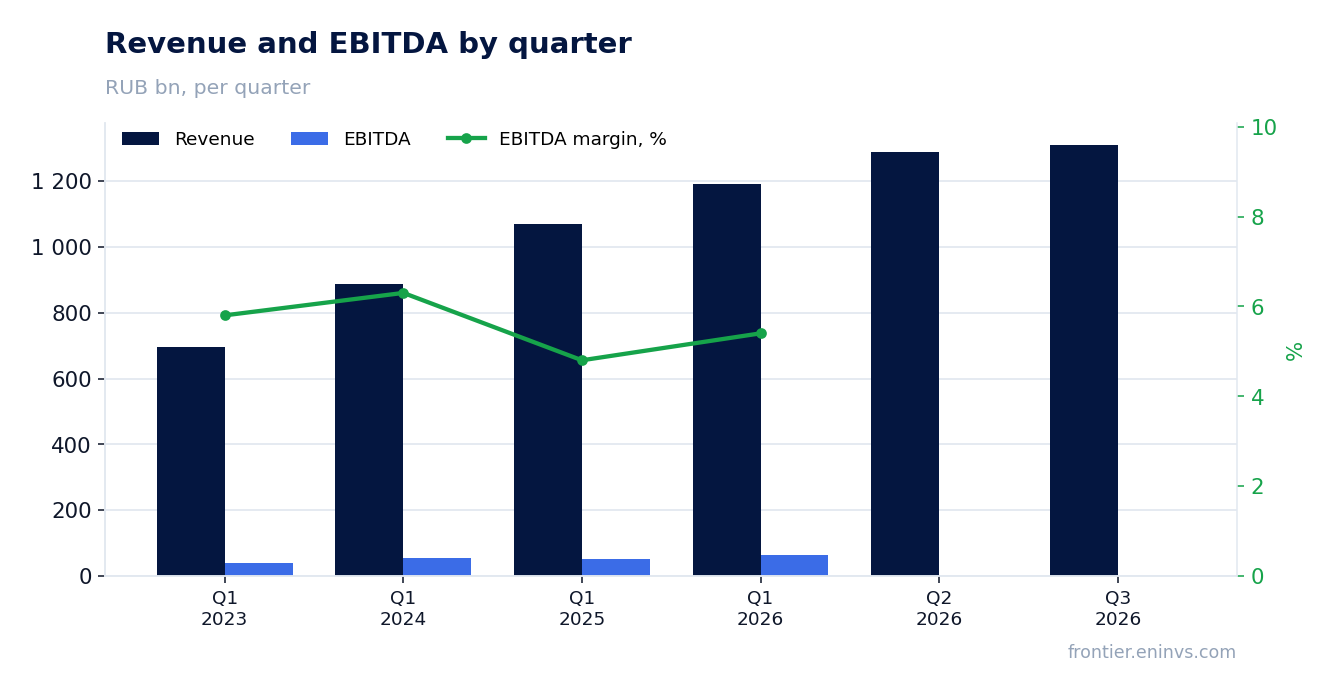
EBITDA and net profit for Q3 were not disclosed, so the margin for the reported period cannot be assessed
In the reported quarter, the company did not disclose EBITDA or net profit. This prevents an assessment of margin dynamics for Q3 2026. In Q1 2026, EBITDA was RUB 64.3 bn, operating profit RUB 56.7 bn, and net profit RUB 13.3 bn.
The absence of Q3 data creates uncertainty for profitability assessment. An investor can rely only on trailing twelve-month figures: net profit of RUB 67.9 bn and EBITDA of RUB 263.6 bn.
Without quarterly data, one cannot judge whether margins held at prior levels or changed. This limits the analysis but does not overturn the overall picture of a profitable business.
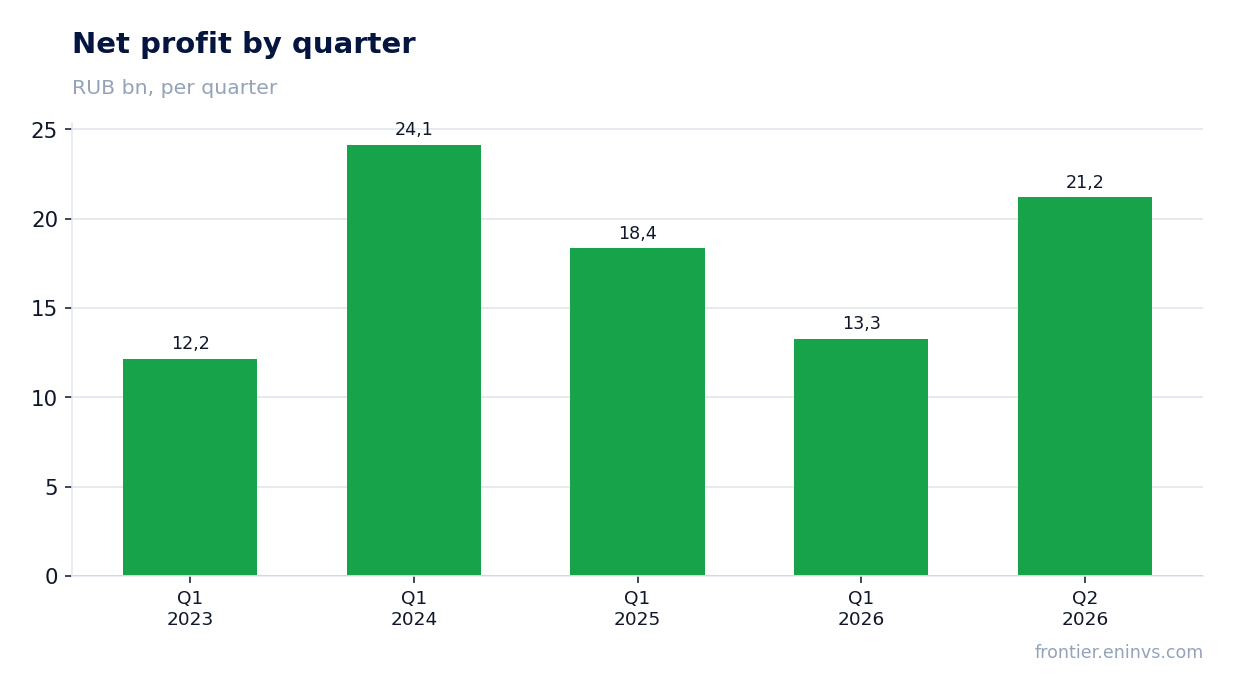
Over the trailing twelve months, net profit reached RUB 67.9 bn on revenue of RUB 5,029.5 bn
Over the trailing twelve months, net profit reached RUB 67.9 bn on revenue of RUB 5,029.5 bn. The net margin is about 1.3%, a low figure typical of high-turnover retail.
LTM EBITDA reached RUB 263.6 bn, giving an EBITDA margin of about 5.2%. Operating profit in Q1 2026 was RUB 56.7 bn but was not disclosed for Q3.
LTM profit is the base for dividend calculations and multiple valuation. The LTM P/E of 8.5 indicates a low market valuation of earnings.
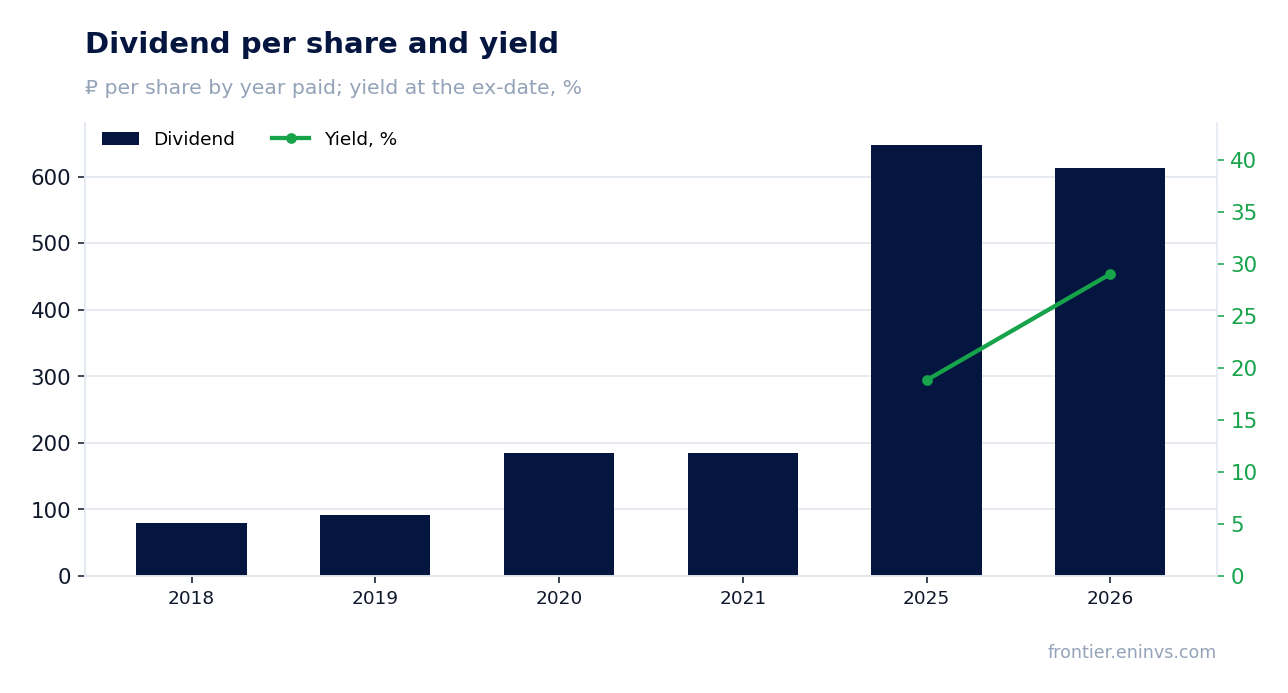
Dividends paid over the last year were RUB 613 per share, a 26.2% yield versus the 22.5% we consider fair
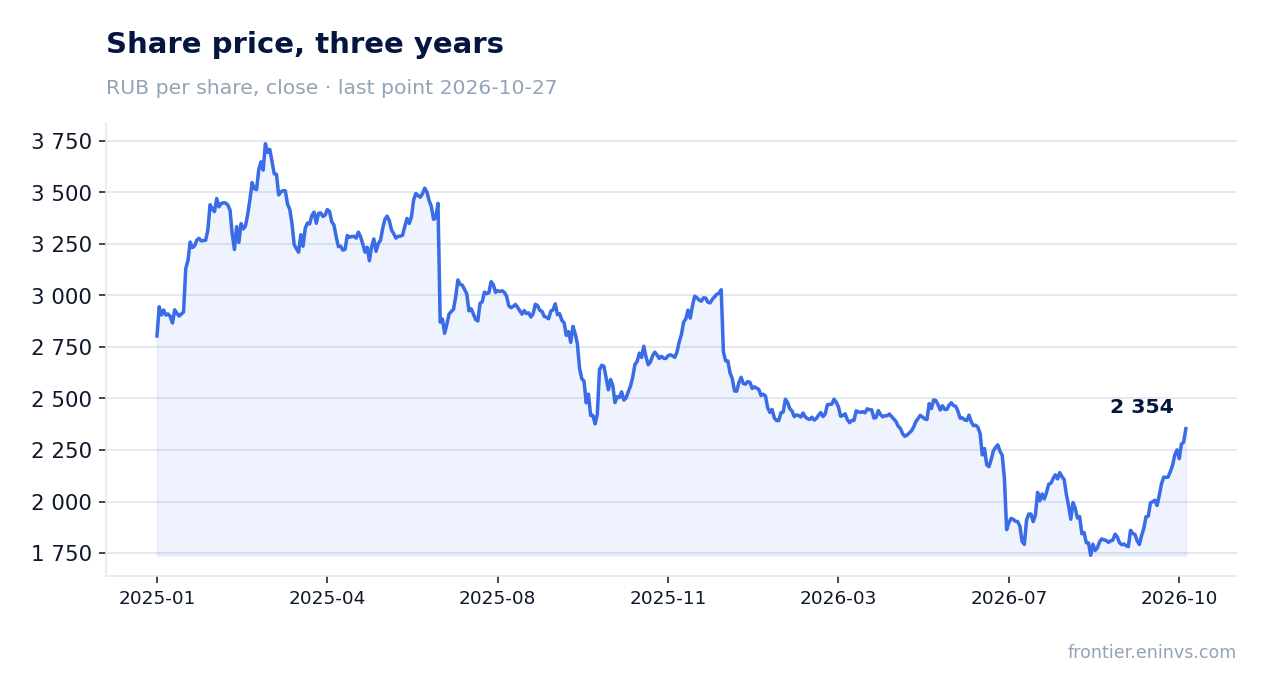
Over the last twelve months, the company paid RUB 613 per share. At the current price, this gives a dividend yield of 26.2%. We consider a 22.5% yield fair for this name, so the current payout exceeds our benchmark.
The payout history shows growth: RUB 648 per share was paid in 2025 with an 18.8% yield at the ex-date price, and RUB 613 in 2026 with a 29.0% yield. The lower absolute payout in 2026 is offset by the share price decline, which raised the yield.
The payout ratio is 0.86 of profit. This is a high level that supports the yield but limits room for growth without higher profit.
Our estimate for the current financial year's dividend is RUB 239.16 per share, or a 10.2% yield on the current price
We estimate the dividend for the current financial year at RUB 239.16 per share. This is our own calculation based on LTM profit and a payout ratio of 0.864. At the current price, this implies a 10.2% yield.
The estimate is well below actual payouts over the last year. This is because the calculation relies on LTM profit rather than peak profit from prior periods. The board decides on the payout; our estimate is not a guarantee.
Key risks to the payout size are lower profit and possible changes to dividend policy. With a payout ratio of 0.86, any decline in profit directly reduces the dividend.
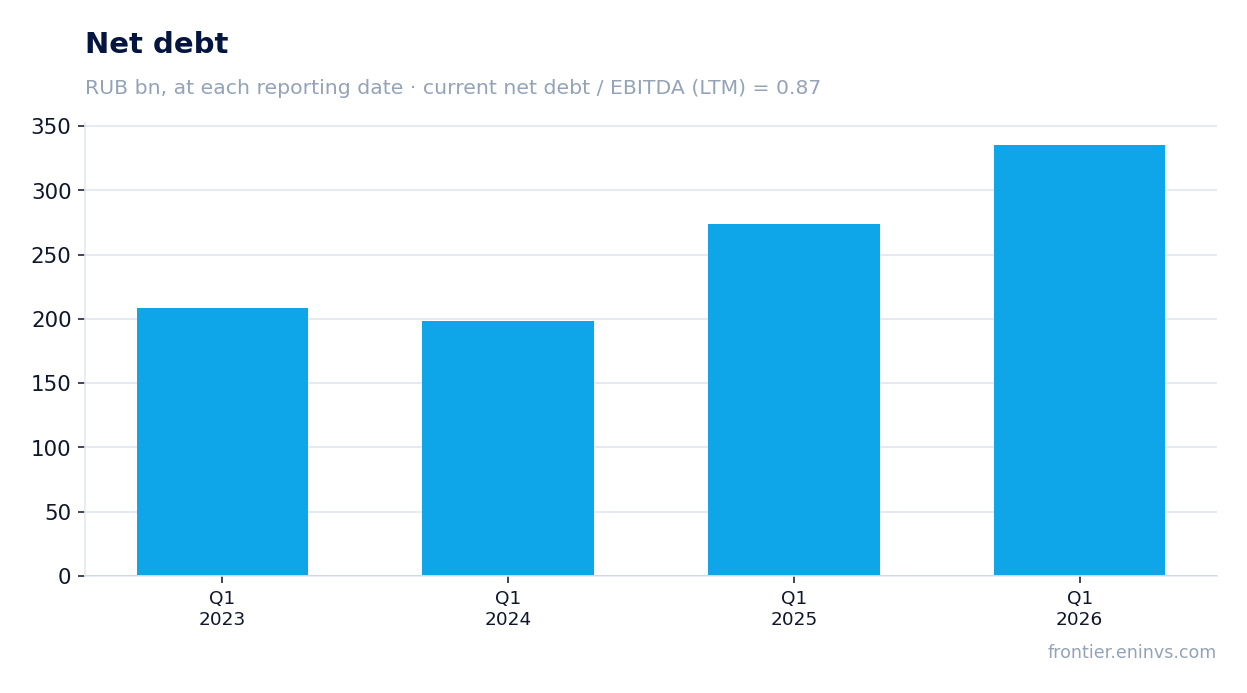
Leverage on the latest balance sheet is 0.87 net debt to LTM EBITDA, a moderate level
Net debt on the latest balance sheet is RUB 228.5 bn. The ratio of net debt to LTM EBITDA is 0.87. This is a moderate level for a retailer and leaves room for manoeuvre.
We do not have an earlier value for this ratio, so we cannot judge its direction of change. The level of 0.87 by itself does not create a debt burden that threatens dividends.
Interest expenses are not disclosed in the provided data, but with the key rate at 14.0%, debt servicing remains a significant factor for profit. However, the current debt level does not look critical.
EV/EBITDA of 3.1 is below its own three-year average of 3.4, and the portal model implies 43% upside to fair value
The LTM EV/EBITDA multiple is 3.1, which is 11% below its own three-year average of 3.4. This indicates the share trades cheaper than its historical valuation on this multiple.
According to the portal model, which compares EBITDA growth with the target multiple, the upside to fair value is 43%. This is our own estimate, not a market consensus or a target price.
The LTM P/E of 8.5 also points to a low valuation of earnings. The combination of low multiples and a high dividend yield makes the share attractive for income-oriented investors.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 575 bn ₽ |
| P/E (LTM) | 8.5 |
| EV/EBITDA (LTM) | 3.1 |
| P/B | 5.94 |
| Net debt / EBITDA (LTM) | 0.87 |
| ROE | 80.9% |
| Dividend yield (12m) | 26.2% |
| EV/EBITDA, 3-year average | 3.4 |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2018 | 79.50 | — |
| 2019 | 92.06 | — |
| 2020 | 184.12 | — |
| 2021 | 184.14 | — |
| 2025 | 648.00 | 18.8% |
| 2026 | 613.00 | 29.0% |
| Our estimate, current year | 239.16 | 10.2% on the current price |
Bottom line
The strong side of the report is maintained double-digit revenue growth and moderate leverage of 0.87. The weak side is the absence of quarterly profit data and decelerating growth. The dividend yield of 26.2% exceeds the fair level of 22.5%, and the EV/EBITDA multiple of 3.1 is below its own history. Verdict: the share is attractive at the current price, but the key question for a holder is whether profit will remain sufficient for payouts.
Open the company's financial profile X5 →
See also: market overview · valuation map · stock screeners