Yandex: profit quadrupled, but half came from the sale of Auto.ru
20 августа Яндекс раскрыл результаты за второй квартал 2026 года: выручка выросла на 16,2% до 386,3 млрд руб., EBITDA — на 78,8% до 114,4 млрд руб., чистая прибыль — в 3,97 раза до 64,5 млрд руб. Рост прибыли обеспечен как операционным рывком, так и разовым доходом от продажи Авто.ру в размере 25,7 млрд руб. Акции торгуются по EV/EBITDAC 6,9 против среднего за три года 10,2, что выглядит привлекательно на фоне ускорения рентабельности и снижения долга.
Key takeaways
— Выручка +16,2% — это замедление после +21,6% в первом квартале, но драйверы роста сменились с поиска на города и подписку
— EBITDA-маржа выросла с 19,2% до 29,6% — главный вклад внес сегмент Городов, где рентабельность подскочила с 4,6% до 10,2%
— Чистая прибыль выросла в 4 раза, но 25,7 млрд руб. из 64,5 млрд — разовый доход от продажи Авто.ру
— Операционный денежный поток во втором квартале — 136,2 млрд руб., что в 2,7 раза выше EBITDA за квартал
— Чистый долг сократился на 20,5 млрд руб. за квартал и на 81 млрд руб. за год — до 66,5 млрд руб.
— Дивиденд за 12 месяцев — 190 руб. на акцию, доходность 5,0% — ниже справедливых для нас 7,0%
— EV/EBITDAC 6,9 — на 32% ниже собственного трехлетнего среднего (10,2), модель портала оценивает апсайд в +59%
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 333 | 386 | +16.2% |
| EBITDA | 64.0 | 114 | +78.8% |
| Operating profit | 41.1 | 88.9 | +116.3% |
| Net profit | 16.2 | 64.5 | +297.5% |
| Operating cash flow | 50.7 | 136 | +168.6% |
| Capex | 23.6 | 60.1 | +154.5% |
| EBITDA margin | 19.2% | 29.6% | +10.4 pp |
| Net margin | 4.9% | 16.7% | +11.8 pp |
Revenue +16.2% — a slowdown from +21.6% in Q1, but growth drivers shifted from search to cities and subscription
In Q2 2026, Yandex's revenue grew 16.2% YoY to RUB 386.3 bn, down from 21.6% growth in Q1. The slowdown reflects a structural shift: search advertising, historically the main revenue source, declined 1% YoY to RUB 122.6 bn in Q1, and the trend continued into Q2.
Growth came from other segments. In Cities (ride-hailing, e-commerce, delivery), revenue rose 18% YoY to RUB 210.5 bn in Q1, while Personal services (Plus subscription, entertainment) grew 30% to RUB 62.4 bn. B2B Tech was up 36% to RUB 13.6 bn. Thus, the company is successfully diversifying away from search ads: ad revenue grows only 9% versus group revenue of 22% (Q1 data).
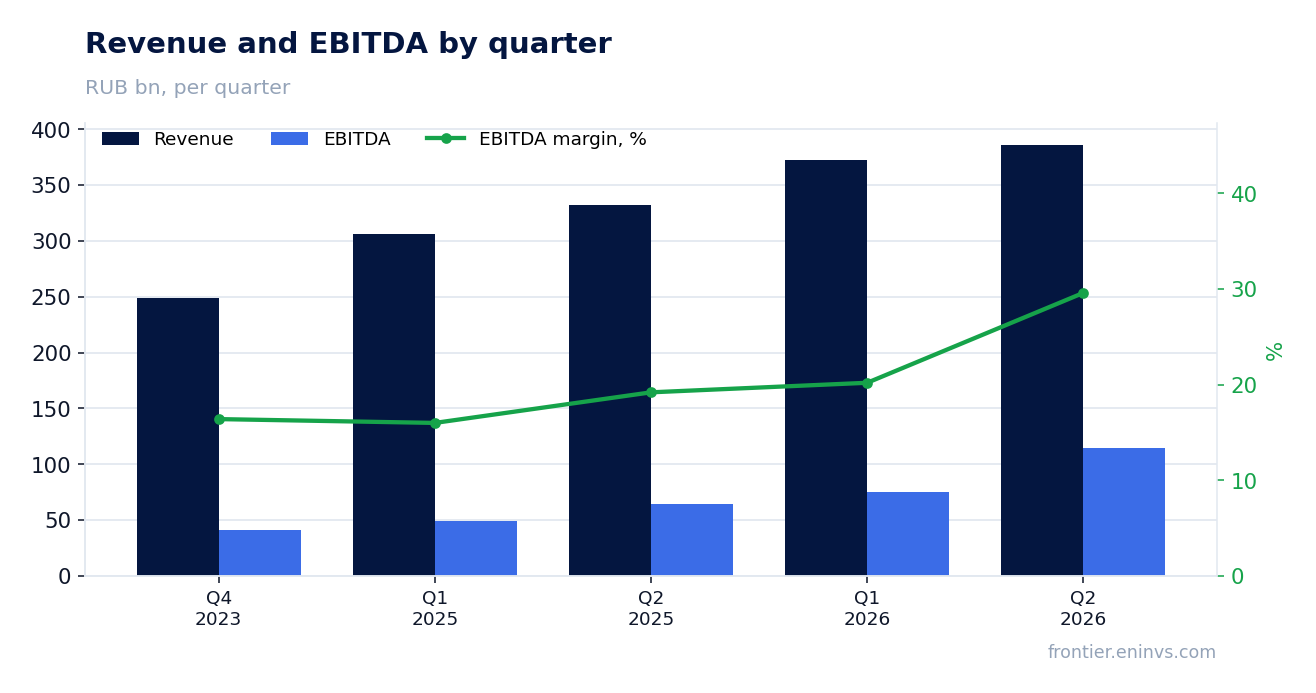
EBITDA margin rose from 19.2% to 29.6% — mainly driven by Cities, where profitability jumped from 4.6% to 10.2%
EBITDA in Q2 rose 78.8% to RUB 114.4 bn, with margin expanding from 19.2% to 29.6%. The key driver was the Cities segment (ride-hailing, e-commerce, delivery): its adjusted EBITDA grew 161% YoY to RUB 21.5 bn in Q1, and margin rose from 4.6% to 10.2%. Ride-hailing achieved high profitability through scaling and improved take-rate.
Other segments also contributed: Personal services turned EBITDA-positive (RUB 0.8 bn vs a loss of RUB 1.1 bn a year earlier), B2B Tech expanded margin to 19.4%. Search, by contrast, saw EBITDA decline 6% in Q1 due to ad slowdown, though its margin remains high at 43.1%.
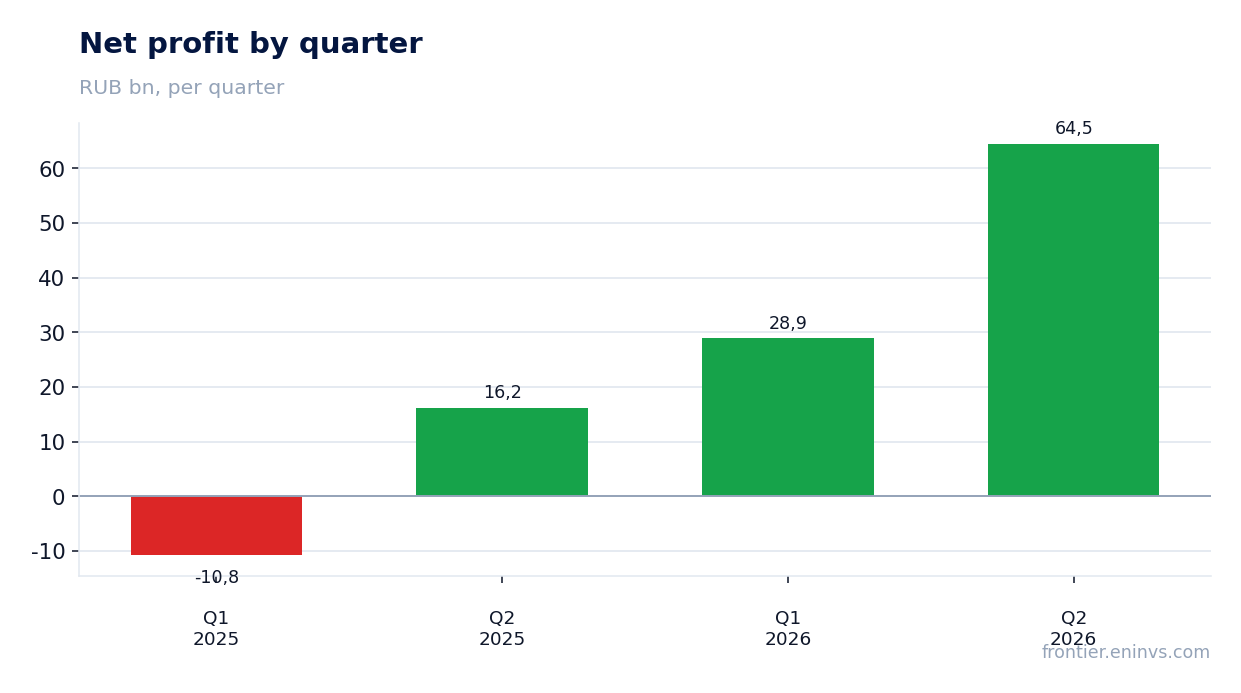
Net profit quadrupled, but RUB 25.7 bn of RUB 64.5 bn is a one-off gain from the sale of Auto.ru
Net profit in Q2 reached RUB 64.5 bn versus RUB 16.2 bn a year earlier — a 3.97x increase. However, operating profit (RUB 88.9 bn) includes a RUB 25.7 bn gain from the sale of Auto.ru. Without this one-off, profit would be roughly 40% lower.
The sale of Auto.ru for RUB 35 bn was completed in June 2026, part of a strategy to focus on key areas. Operating profit excluding this gain would have been about RUB 63.2 bn, still 1.5x higher than last year's RUB 41.1 bn — the underlying business did accelerate.
Operating cash flow in Q2 was RUB 136.2 bn, 2.7x the quarterly EBITDA
In Q2, operating cash flow reached RUB 136.2 bn — 2.7x the quarterly EBITDA (RUB 114.4 bn). The gap reflects seasonality and working capital dynamics, including inflows from client deposits in financial services. For H1, OCF was RUB 136.2 bn (per the cash flow statement: RUB 136,174 mn), almost double last year's RUB 81.8 bn.
Capex in Q2 was RUB 60.1 bn, notably above the 2025 average of RUB 23.6 bn per quarter. The company is increasing investments in infrastructure and autonomous technologies. Free cash flow (OCF minus capex) for the quarter was RUB 76.1 bn, comfortably covering dividends.
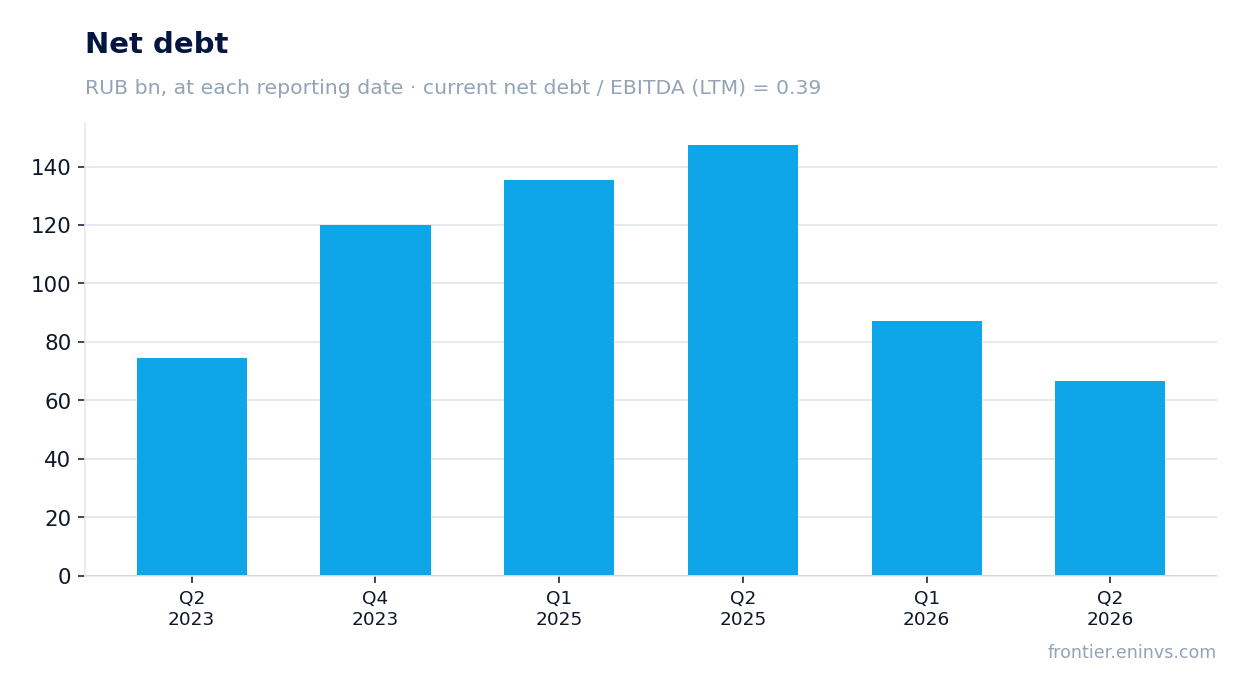
Net debt fell by RUB 20.5 bn in the quarter and RUB 81 bn over the year — to RUB 66.5 bn
At the end of Q2, net debt stood at RUB 66.5 bn, down RUB 20.5 bn from the previous reporting date and RUB 81 bn over 12 months. The reduction was driven by strong operating cash flow and proceeds from the Auto.ru sale.
Net debt to EBITDA for the trailing twelve months is 0.39, a low level. The company maintains significant liquidity: cash and equivalents at period end were RUB 296 bn, plus undrawn credit lines of RUB 493 bn.
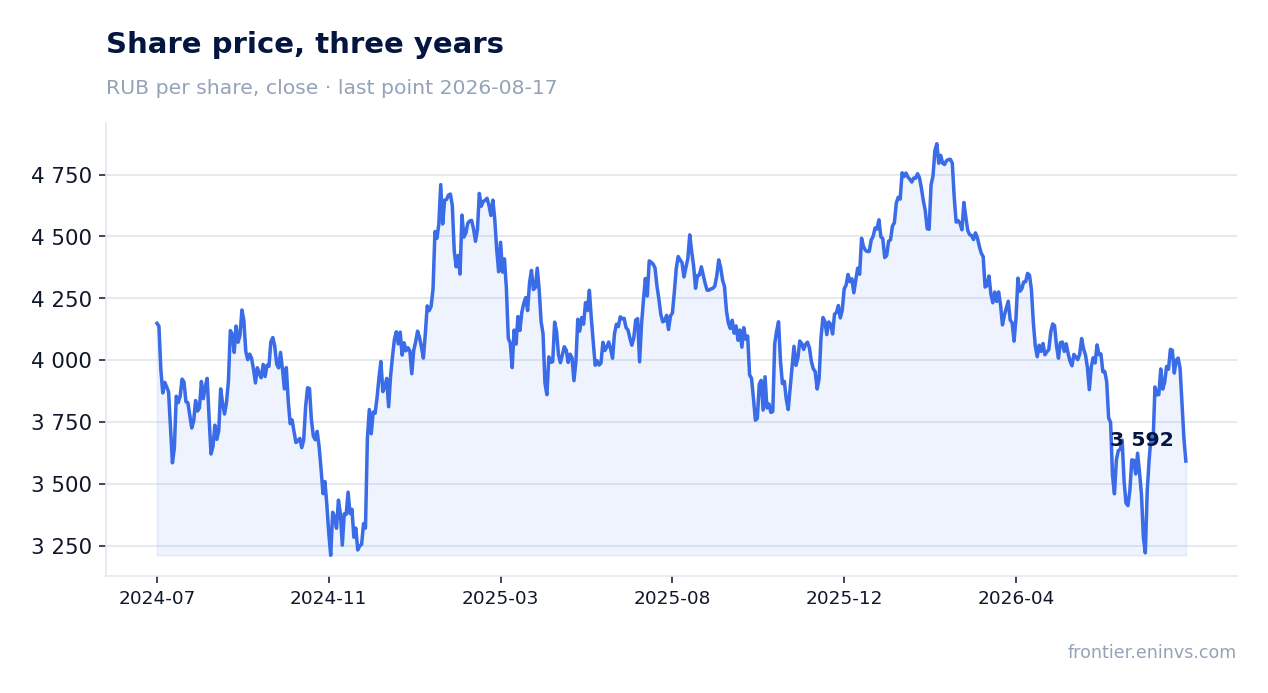
Dividend over 12 months — RUB 190 per share, yield 5.0% — below our fair yield of 7.0%
Over the last 12 months, Yandex paid RUB 190 per share, a yield of 5.0%. Our model forecasts the same RUB 190 per share for the next period, implying a forward yield of 5.0%. However, we consider a fair yield for this stock to be 7.0%, meaning the current price either needs further dividend growth or a higher share price to reach equilibrium.
The payout ratio is 0.56 of profit — a moderate level leaving room for investment. In April 2026, shareholders approved a dividend of RUB 110 per share for FY2025 (total ~RUB 42 bn), confirming commitment to the policy.
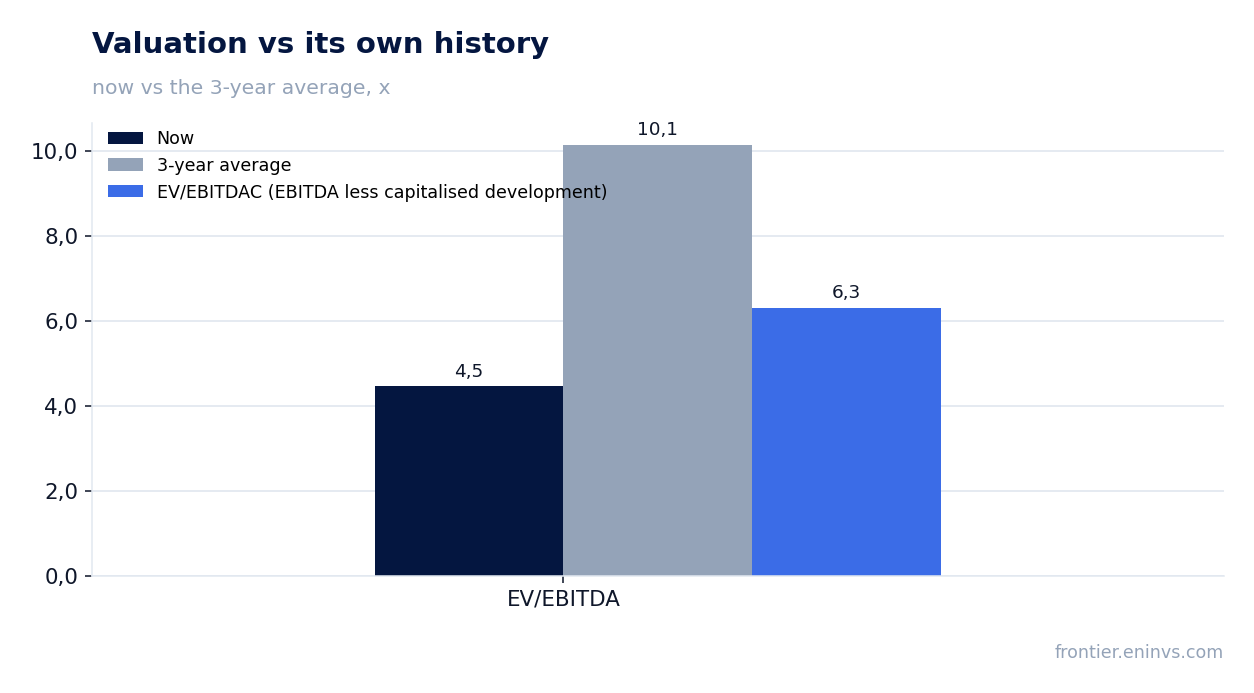
EV/EBITDAC of 6.9 — 32% below its own 3-year average (10.2); the portal's model sees +59% upside
Yandex capitalizes development costs, so EV/EBITDAC (adding capitalized development to EBITDA) is the right metric. It stands at 6.9 — 32% below its own 3-year average of 10.2. Even classic EV/EBITDA is 4.9 versus the average of 10.2, indicating a significant discount to history.
According to the portal's model, the share's fundamental value is 59% above the current price. The stock is included in our strategies: RU AI conviction, RU AI long-short, RU GARP + acceleration, RU Growth-potential, RU Growth-stories — this reflects passing the screens, not an argument for the verdict.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 1 514 bn ₽ |
| P/E (LTM) | 11.8 |
| EV/EBITDA (LTM) | 4.9 |
| EV/EBITDAC (EBITDA less capitalised development) | 6.9 |
| P/B | 5.15 |
| Net debt / EBITDA (LTM) | 0.39 |
| Operating cash flow (LTM) | 282 bn |
| ROE | 65.1% |
| Dividend yield (12m) | 4.9% |
| EV/EBITDA, 3-year average | 10.2 |
Bottom line
The report is strong: EBITDA margin expanded by 10.4 pp to 29.6%, operating cash flow reached RUB 136.2 bn in the quarter, and net debt fell to RUB 66.5 bn. However, nearly half of net profit is a one-off gain from the Auto.ru sale, and revenue growth slowed to 16.2%. Valuation remains attractive: EV/EBITDAC of 6.9 versus a 3-year average of 10.2, and the portal's model implies +59% upside. The shares look rather attractive: the operational leap and debt reduction offset the revenue slowdown, but the key question is whether growth in Cities and Personal services can fully compensate for stagnation in search advertising.
Open the company's financial profile YDEX →
See also: market overview · valuation map · stock screeners