Yandex: profit nearly quadrupled, but RUB 25.7bn of it came from the one-off sale of Auto.ru
On 21 August, MKPAO Yandex released its results for the second quarter of 2026. Revenue rose 16.2% year on year to RUB 386.3bn, EBITDA by 88.5% to RUB 120.6bn, and net profit by 297.8% to RUB 64.5bn. Profit growth was largely one-off: RUB 25.7bn came from the gain on the sale of Auto.ru; excluding it, profit would have roughly doubled. At the same time, revenue growth decelerated from 28.2% in the fourth quarter of 2025. In our view, the share looks attractive at the current price: EV/EBITDAC of 6.6 against a three-year average of 10.2, a dividend yield of 6.1% versus the 7.0% we consider fair, and 64% upside on the portal's model.
Key takeaways
— Revenue grew 16.2%, but that is slower than the 28.2% a quarter earlier
— EBITDA rose 88.5%, and more than half of the gain came from the Auto.ru sale
— EBITDA margin rose to 31.2% from 19.2% a year earlier
— Net profit nearly quadrupled, but RUB 25.7bn of it was one-off
— Net debt fell to RUB 66.5bn from RUB 94.8bn at end-2025
— The dividend for 2026 could be RUB 354.45 per share on our estimate
— EV/EBITDAC of 6.6 versus a three-year average of 10.2 – the share is cheaper than its own history
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 333 | 386 | +16.2% |
| EBITDA | 64.0 | 121 | +88.5% |
| Operating profit | 41.1 | 88.9 | +116.3% |
| Net profit | 16.2 | 64.5 | +297.8% |
| Operating cash flow | 50.7 | 68.1 | +34.3% |
| Capex | 23.6 | 30.0 | +27.2% |
| EBITDA margin | 19.2% | 31.2% | +12.0 pp |
| Net margin | 4.9% | 16.7% | +11.8 pp |
Revenue grew 16.2%, but that is slower than the 28.2% a quarter earlier
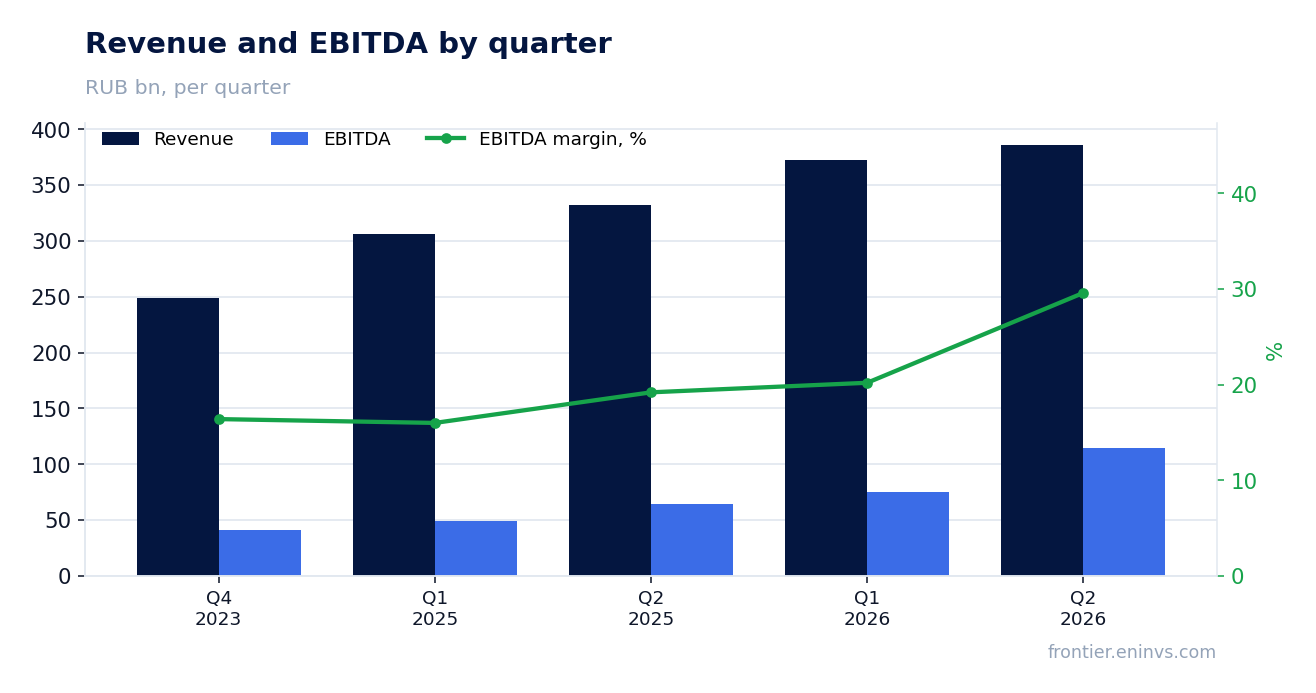
Revenue in the second quarter of 2026 was RUB 386.3bn, up 16.2% year on year. That is a deceleration from the fourth quarter of 2025, when growth was 28.2%. The slowdown is explained primarily by the base effect: a year ago revenue was growing faster, and part of the Auto.ru business was disposed of in June 2026.
By segment, the main contributors to revenue were Search and AI services – RUB 137.4bn, or 35.6% of total revenue, and E-commerce services – RUB 123.7bn (32.0%). Ride-tech brought in RUB 77.6bn (20.1%), Plus and entertainment services – RUB 34.9bn (9.0%), Financial services – RUB 29.5bn (7.6%).
Total segment revenue was RUB 445.8bn, but inter-segment turnover of RUB 59.5bn was eliminated on consolidation, giving the final RUB 386.3bn of revenue from third parties.
The slowdown in revenue growth is the key signal from the report. If in the fourth quarter of 2025 the company grew 28.2%, then in the second quarter of 2026 it grew only 16.2%. This may reflect both market saturation and the high base effect of last year, but the fact remains: growth rates have decelerated.
EBITDA rose 88.5%, and more than half of the gain came from the Auto.ru sale
EBITDA in the second quarter of 2026 was RUB 120.6bn, up 88.5% year on year. However, EBITDA includes the gain on the sale of Auto.ru of RUB 25.7bn. Excluding this one-off gain, EBITDA would have been about RUB 94.9bn, and growth about 48.3%.
Adjusted segment EBITDA was RUB 89.1bn versus RUB 66.5bn a year earlier. The main contributors were Search and AI services – RUB 63.7bn (71.5% of adjusted segment EBITDA) and Ride-tech – RUB 35.0bn (39.2%). At the same time, E-commerce services turned positive on adjusted EBITDA for the first time – RUB 0.4bn versus a loss of RUB 10.9bn a year earlier.
EBITDA growth was partly driven by the one-off gain, but operating efficiency also improved: adjusted segment EBITDA grew 34.1% year on year. This suggests the company not only received a one-off profit but also improved its core business.
EBITDA margin rose to 31.2% from 19.2% a year earlier
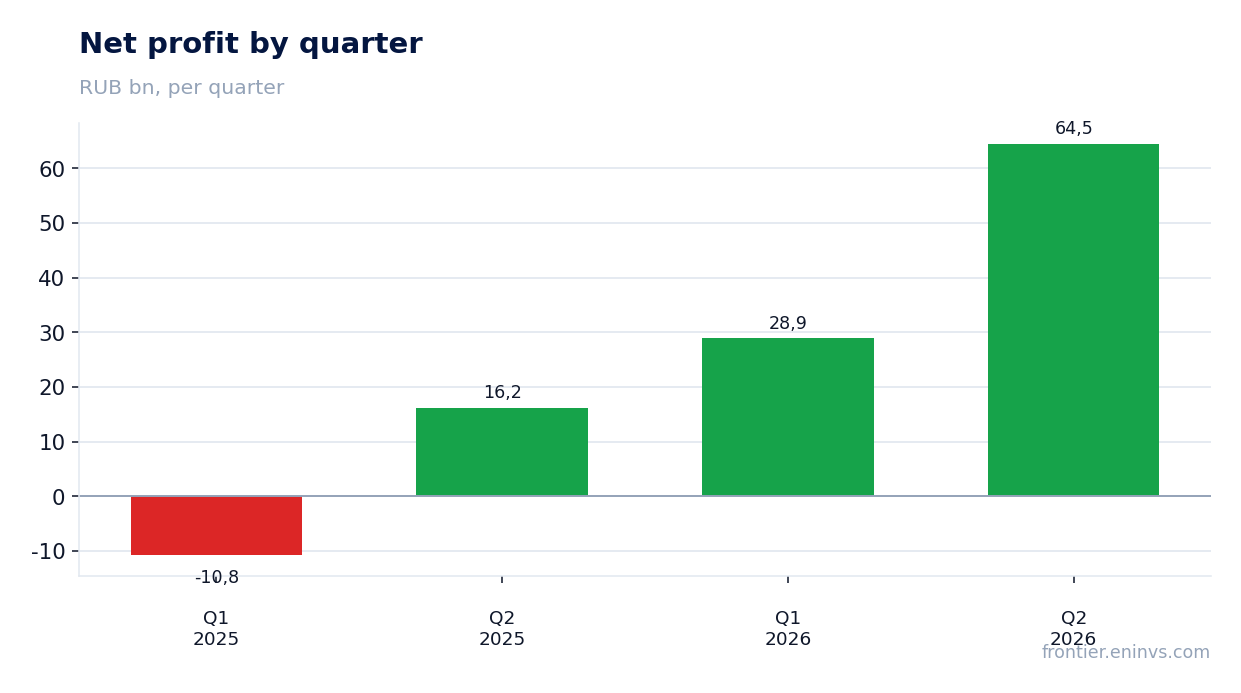
EBITDA margin in the second quarter of 2026 was 31.2%, significantly higher than 19.2% a year earlier. This margin growth is largely due to the one-off gain from the Auto.ru sale, which added about 6.7 percentage points to the margin. Excluding it, the margin would have been about 24.5%.
Operating profit rose to RUB 88.9bn from RUB 41.1bn a year earlier. The operating margin was 23.0% versus 12.4% a year earlier. The one-off gain also had an effect here.
Margin growth is a positive signal, but it is important to understand that part of it is one-off. Sustainable margin is likely closer to 24–25%, which is still above last year's 19.2%.
Net profit nearly quadrupled, but RUB 25.7bn of it was one-off
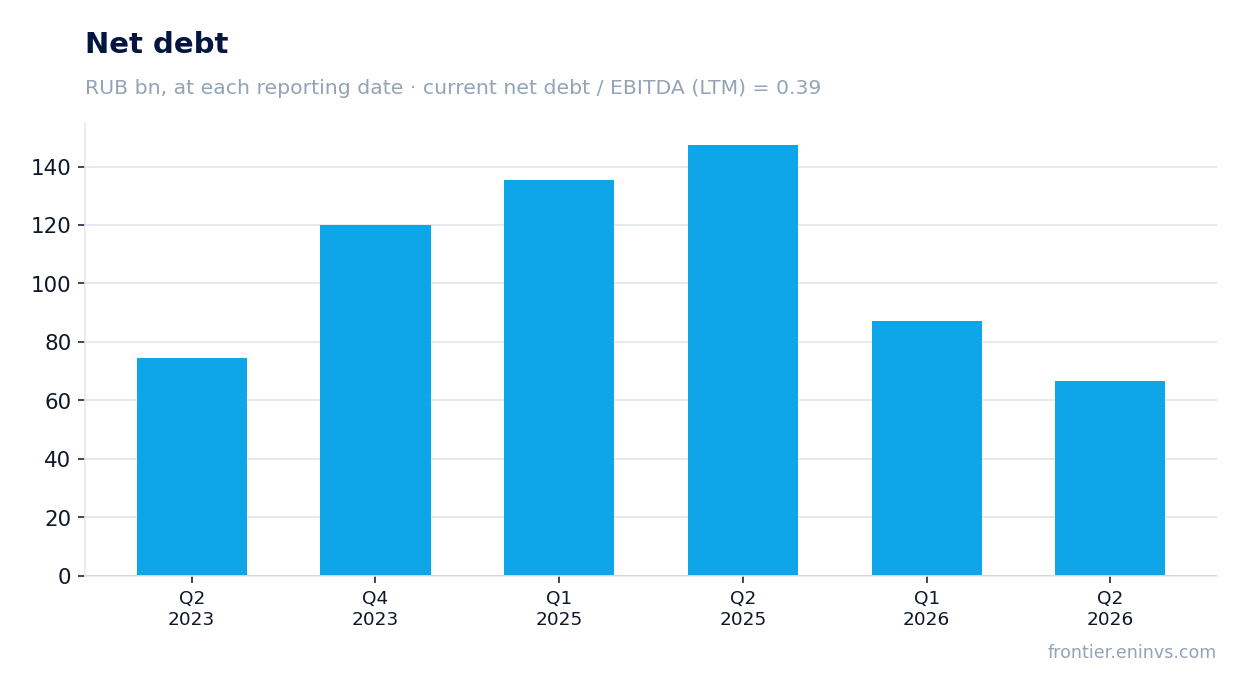
Net profit in the second quarter of 2026 was RUB 64.5bn, up 297.8% year on year. However, profit includes the gain on the sale of Auto.ru of RUB 25.7bn. Excluding this one-off gain, net profit would have been about RUB 38.8bn, and growth about 139.2%.
Profit before tax was RUB 77.1bn versus RUB 24.8bn a year earlier. Income tax expense rose to RUB 12.6bn from RUB 8.6bn. The effective tax rate fell to 16.3% from 34.5%, due to the Auto.ru sale and tax benefits for IT companies.
The one-off gain from the Auto.ru sale is the key driver of profit growth. Excluding it, profit would have grown about 2.4 times, which is also significant, but not fourfold.
Net debt fell to RUB 66.5bn from RUB 94.8bn at end-2025
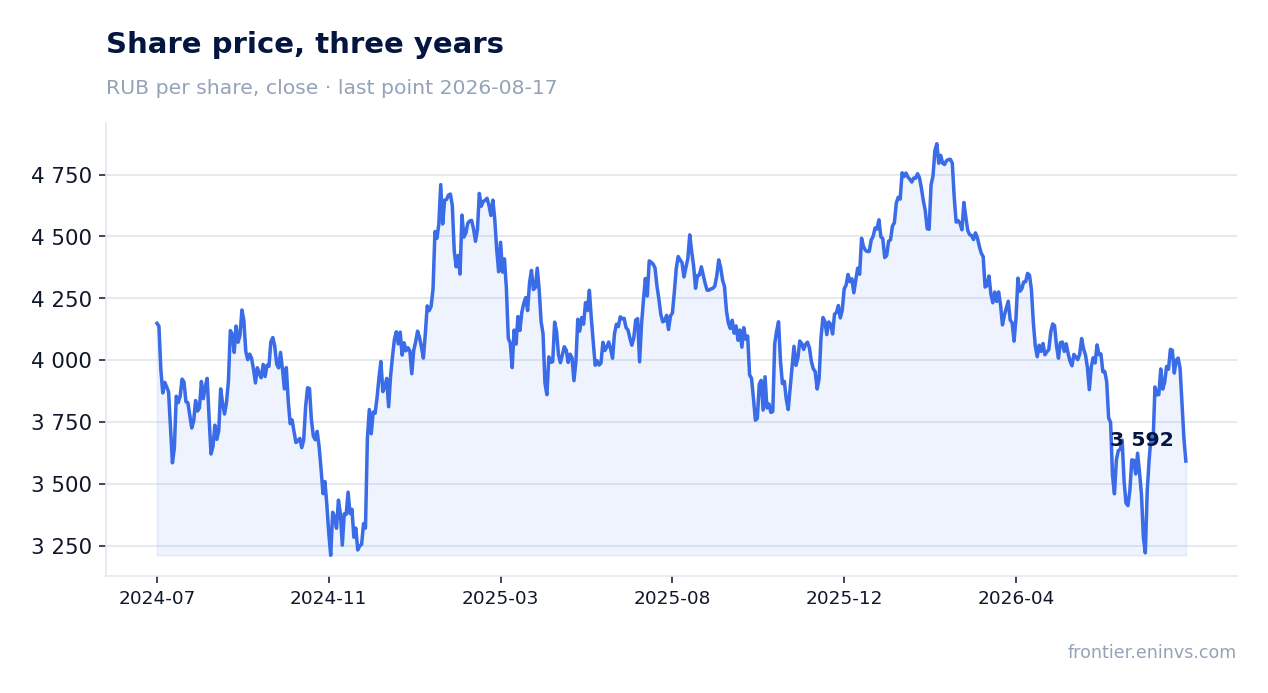
Net debt as of 30 June 2026 was RUB 66.5bn versus RUB 94.8bn as of 31 December 2025, a decrease of RUB 28.3bn. Over 12 months, net debt fell from RUB 147.5bn on 30 June 2025 to RUB 66.5bn on 30 June 2026, a decrease of RUB 81.0bn.
The reduction in net debt was due to growth in cash and equivalents to RUB 296.0bn from RUB 250.2bn at end-2025, as well as the receipt of RUB 31.5bn from the Auto.ru sale. Debt rose to RUB 277.3bn from RUB 269.7bn, but the increase was offset by a larger cash cushion.
The net debt to LTM EBITDA ratio is 0.2 – a low level. The company retains significant liquidity: available unused credit lines amount to RUB 493.2bn versus RUB 386.9bn at end-2025.
The dividend for 2026 could be RUB 354.45 per share on our estimate
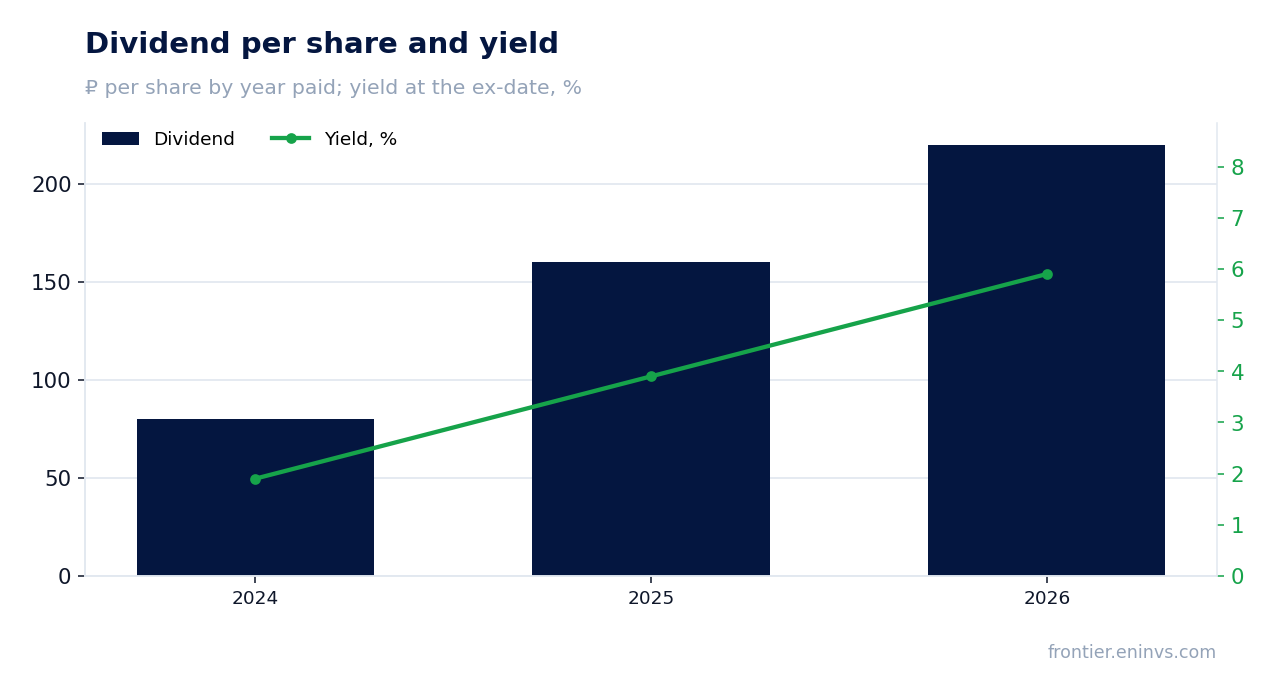
Over the last 12 months, the company paid RUB 220.0 per share, giving a current dividend yield of 6.1%. In our estimate, the dividend for the current financial year (to be paid next year) could be RUB 354.45 per share, corresponding to a yield of 9.8% on the current price. This is our estimate, based on LTM net profit increased by 10% (the share of profit paid out last year) and the number of shares. The board decides.
Dividend history: for 2024 – RUB 80.0 per share (yield 1.9% at the ex-date), for 2025 – RUB 160.0 (3.9%), for 2026 – RUB 220.0 (5.9%). The company consistently increases payments, and our estimate assumes further growth.
The dividend yield we consider fair for this name is 7.0%. The current yield of 6.1% is below fair, but the forward yield on our estimate of 6.6% is already closer to it. At the same time, the central bank key rate is 14.0%, which makes the dividend yield less attractive in absolute terms, but for a growing IT company this is normal.
The risk of a dividend cut is linked to a possible fall in net profit if one-off gains are not repeated, as well as to rising capital expenditures. However, low net debt and strong cash flow allow the company to maintain high payouts.
EV/EBITDAC of 6.6 versus a three-year average of 10.2 – the share is cheaper than its own history
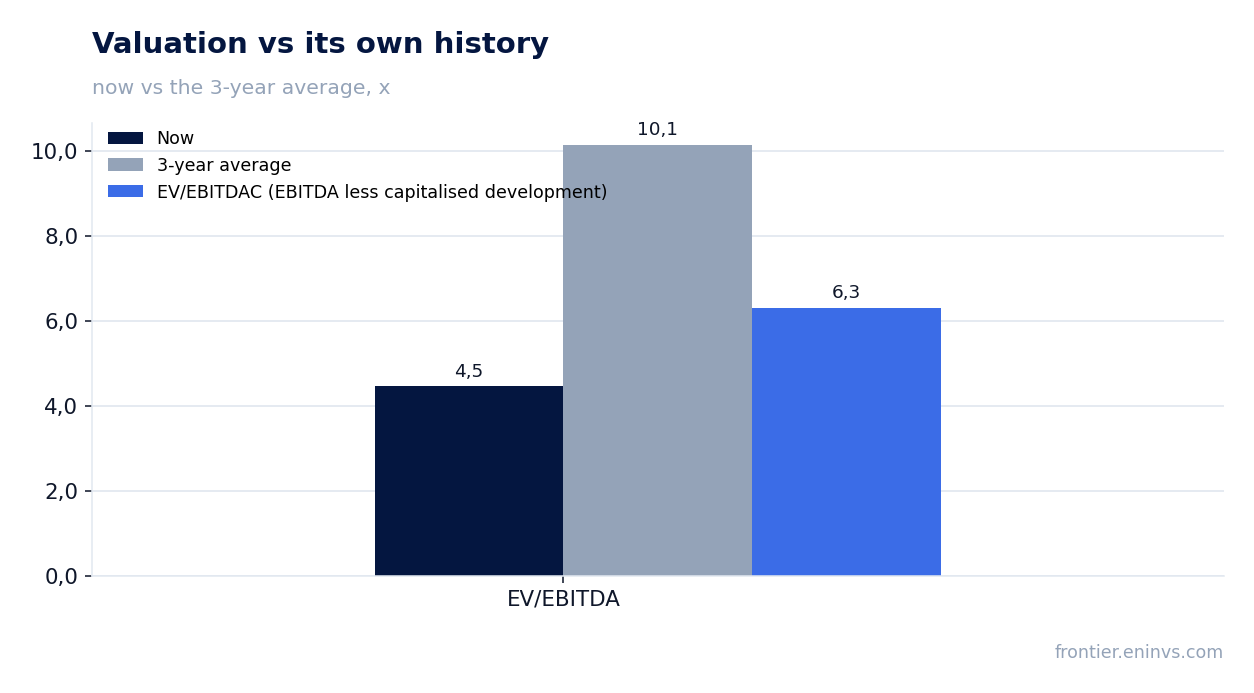
EV/EBITDAC LTM is 6.6, significantly below the three-year average of 10.2. This indicates that the share is trading cheaper than its historical valuation. EV/EBITDA LTM is 4.6, P/E LTM is 11.2. Return on equity (ROE) is 63.5%.
According to the portal's model, the upside to fair value is estimated at +64%. This is our own model, based on EBITDA growth and a target multiple, not a market consensus or a target price.
The share is held in our live model strategies: RU AI conviction (Claude), RU AI long-short (market-neutral), RU GARP + acceleration, RU Growth-potential (quality), RU Growth-stories (GARP). This is a fact, not an argument for the verdict.
Given the low multiple, high ROE and upside on the portal's model, the share looks attractive. However, the slowdown in revenue growth and the one-off nature of part of the profit require caution.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 1 430 bn ₽ |
| P/E (LTM) | 11.2 |
| EV/EBITDA (LTM) | 4.6 |
| EV/EBITDAC (EBITDA less capitalised development) | 6.6 |
| P/B | 4.87 |
| Net debt / EBITDA (LTM) | 0.20 |
| Operating cash flow (LTM) | 300 bn |
| ROE | 63.5% |
| Dividend yield (12m) | 6.1% |
| EV/EBITDA, 3-year average | 10.2 |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2024 | 80.00 | 1.9% |
| 2025 | 160.00 | 3.9% |
| 2026 | 220.00 | 5.9% |
| Our estimate, current year | 354.45 | 9.8% on the current price |
Bottom line
The Q2 2026 report showed strong results: revenue grew 16.2%, EBITDA by 88.5%, net profit by 297.8%. However, a significant part of profit and EBITDA growth was driven by the one-off gain on the Auto.ru sale of RUB 25.7bn. Excluding it, profit would have grown about 2.4 times, which is also good, but not fourfold. The company reduced net debt to RUB 66.5bn from RUB 94.8bn at end-2025 and maintains high profitability. A dividend yield of 6.1% and our estimate of the 2026 dividend at RUB 354.45 per share (yield 9.8%) make the stock interesting for income-oriented holders. Given EV/EBITDAC of 6.6 versus the three-year average of 10.2 and 64% upside on the portal's model, the share looks attractive, but the slowdown in revenue growth and the one-off nature of part of the profit are key risks.
Open the company's financial profile YDEX →
See also: market overview · valuation map · stock screeners