Zaymer MFK: profit halved, yet the 31.93 RUB per share payout continues
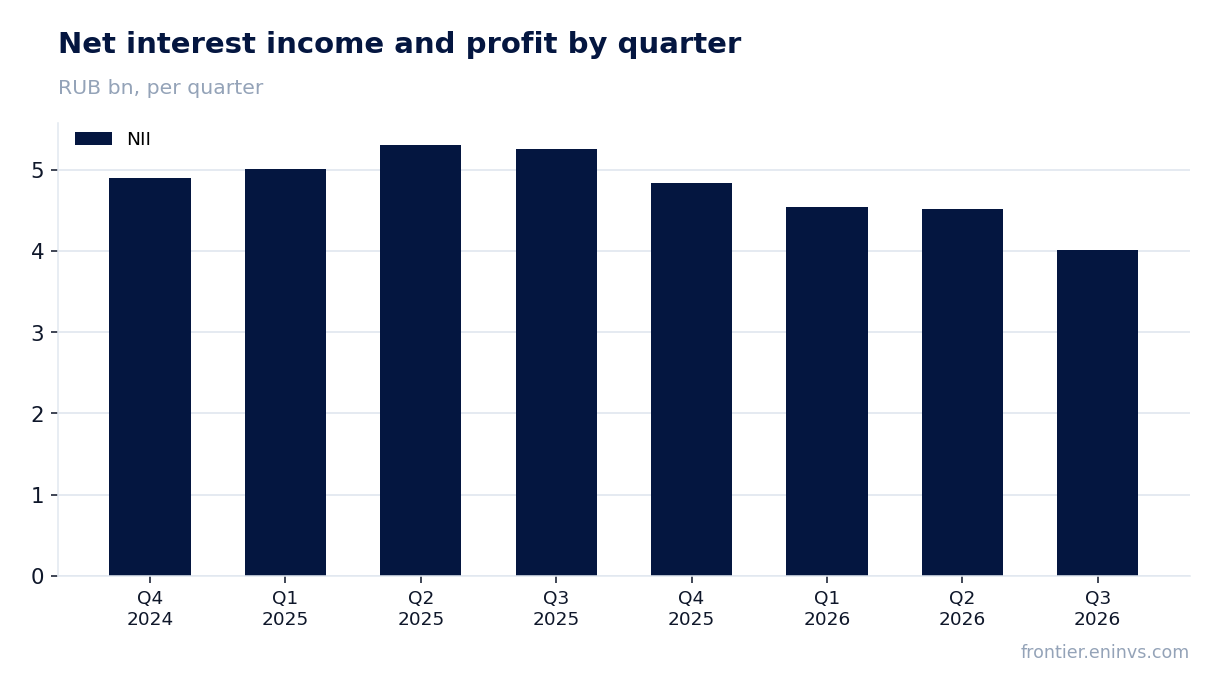
On 28 October Zaymer MFK reported third-quarter 2026 results. Net interest income came in at 4,007.5 mn RUB, down 23.8% year on year, and net profit at 715.6 mn RUB, 48.0% below the prior-year level. The top line keeps decelerating: after a 15.0% decline in the second quarter, the third quarter fell 23.8%. The stock trades at a P/E LTM of 4.8 with a 25.1% dividend yield, and the portal's model puts upside to fair value at +22%. At the current price the share looks rather attractive, but mainly on the dividend – the fundamental trend has not yet turned.
Key takeaways
— Profit fell twice as fast as revenue – the profit share of net interest income compressed from 26.2% to 17.9%
— The customer loan book shrank from 12,108.7 mn to 10,878.6 mn RUB since the start of the year
— Fee and commission income rose to 534.1 mn RUB in the quarter and partly offset the interest-income decline
— The 31.93 RUB per share dividend yields 25.1% – nearly double the 14.6% level we consider fair
— P/E LTM of 4.8 and ROE of 6.8% show the market is already pricing in further profit compression
Attractiveness
Key figures, RUB bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Net interest income | 5.26 | 4.01 | -23.8% |
| Net profit | 1.38 | 0.72 | -48.0% |
| Capex | 0.38 | 0.06 | -85.0% |
| Net margin | 26.2% | 17.9% | -8.3 pp |
Net interest income in Q3 2026 came to 4,007.5 mn RUB versus 5,260.1 mn RUB a year earlier. This is the third consecutive quarterly decline in year-on-year terms: after -1.1% in Q4 2025, the fall accelerated to -9.3% in Q1 2026, then to -15.0% in Q2 and to -23.8% in Q3.
The main cause is the shrinking loan book. Gross customer loans fell from 33,706.1 mn RUB at end-2025 to 29,804.2 mn RUB at 30 September 2026, and the number of borrowers from 1,815,138 to 1,551,394. The company issued 32,212.9 mn RUB of new loans in nine months versus 43,189.3 mn RUB a year earlier – it deliberately scaled lending down.
The average monthly principal balance over nine months of 2026 was 17,843.7 mn RUB versus 21,093.3 mn RUB a year earlier. This confirms the decline in interest income is not a one-off but a consequence of business contraction.
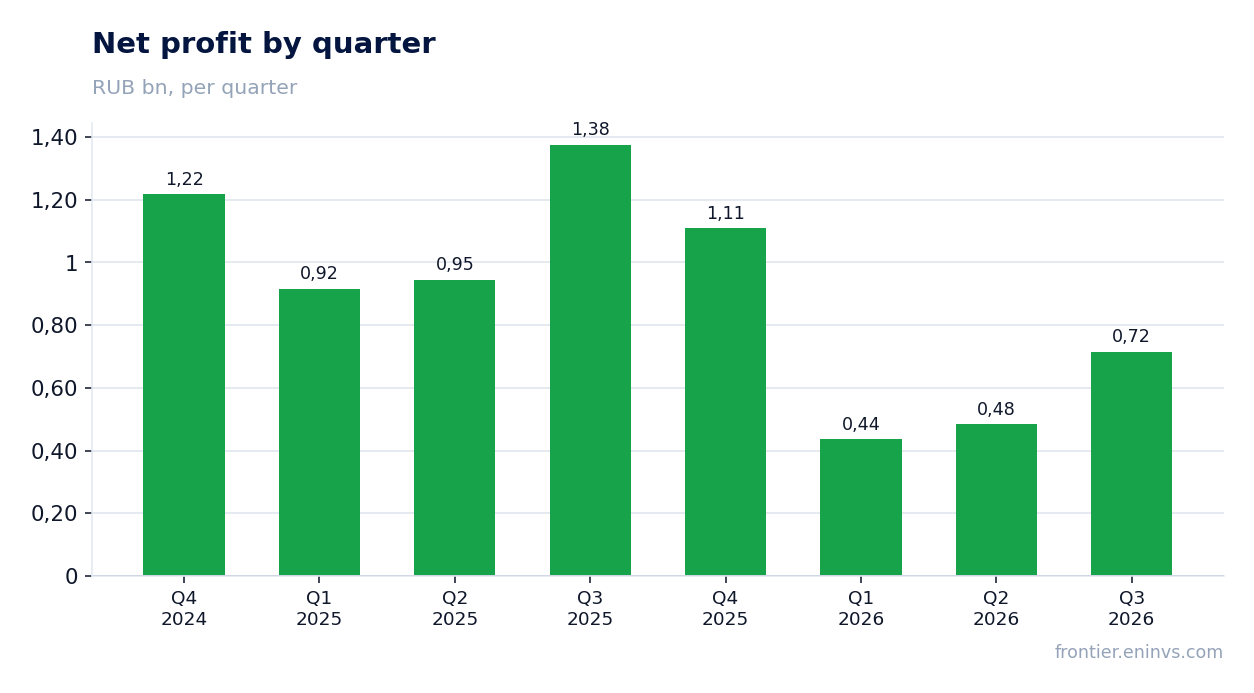
Profit fell twice as fast as revenue – the profit share of net interest income compressed from 26.2% to 17.9%
Net profit in Q3 came to 715.6 mn RUB versus 1,375.9 mn RUB a year earlier, a 48.0% decline against a 23.8% fall in net interest income. The profit share of net interest income dropped from 26.2% to 17.9%.
Several factors weighed on profit. The credit-loss impairment charge for nine months was 5,069.9 mn RUB versus 6,530.6 mn RUB a year earlier – the absolute amount fell, but the share of defaulted loans in the book remains high: 23,922.2 mn RUB out of 29,804.2 mn RUB gross, or 80.3%.
General and administrative expenses rose to 6,729.1 mn RUB from 5,278.7 mn RUB a year earlier. Personnel costs more than doubled, from 1,099.7 mn to 2,205.8 mn RUB, and depreciation from 209.3 mn to 405.8 mn RUB. Marketing expenses, by contrast, were cut from 2,756.0 mn to 2,648.4 mn RUB.
The customer loan book shrank from 12,108.7 mn to 10,878.6 mn RUB since the start of the year
Net customer loans stood at 10,878.6 mn RUB at 30 September 2026 versus 12,108.7 mn RUB at end-2025. The contraction is a direct result of issuing fewer new loans and writing off problem debt more actively.
Write-offs over nine months of 2026 were 1,777.1 mn RUB versus 2,399.0 mn RUB a year earlier. Defaulted loans make up 80.3% of the gross book, and the provision covers 74.5% of them. Even as the absolute provision falls, portfolio quality remains weak.
The company also sells distressed portfolios: the loss on loan-portfolio sales over nine months of 2026 was 373.6 mn RUB versus 710.7 mn RUB a year earlier. The smaller loss on sales is one of the few positive shifts in the report.
Fee and commission income rose to 534.1 mn RUB in the quarter and partly offset the interest-income decline
Fee and commission income in Q3 2026 was 534.1 mn RUB versus 598.9 mn RUB a year earlier. Over nine months it rose to 2,138.1 mn RUB from 1,471.9 mn RUB, but the quarterly trend is already negative.
The nine-month increase came mainly from new lines: payment and transfer commissions brought 457.4 mn RUB, a line that did not exist a year earlier. Penalty income rose to 121.0 mn RUB from 96.6 mn RUB.
Commission expenses also rose, to 592.6 mn RUB from 276.5 mn RUB over nine months. Of that, 390.3 mn RUB was payment and transfer service fees, absent a year earlier. The net effect of the new payment services on profit is still small.
The 31.93 RUB per share dividend yields 25.1% – nearly double the 14.6% level we consider fair
Over the last 12 months the company paid 31.93 RUB per share, a 25.1% yield to the current price. Our model estimates the next dividend at the same 31.93 RUB per share, so the forward yield is also 25.1%. We consider 14.6% a fair yield for this name.
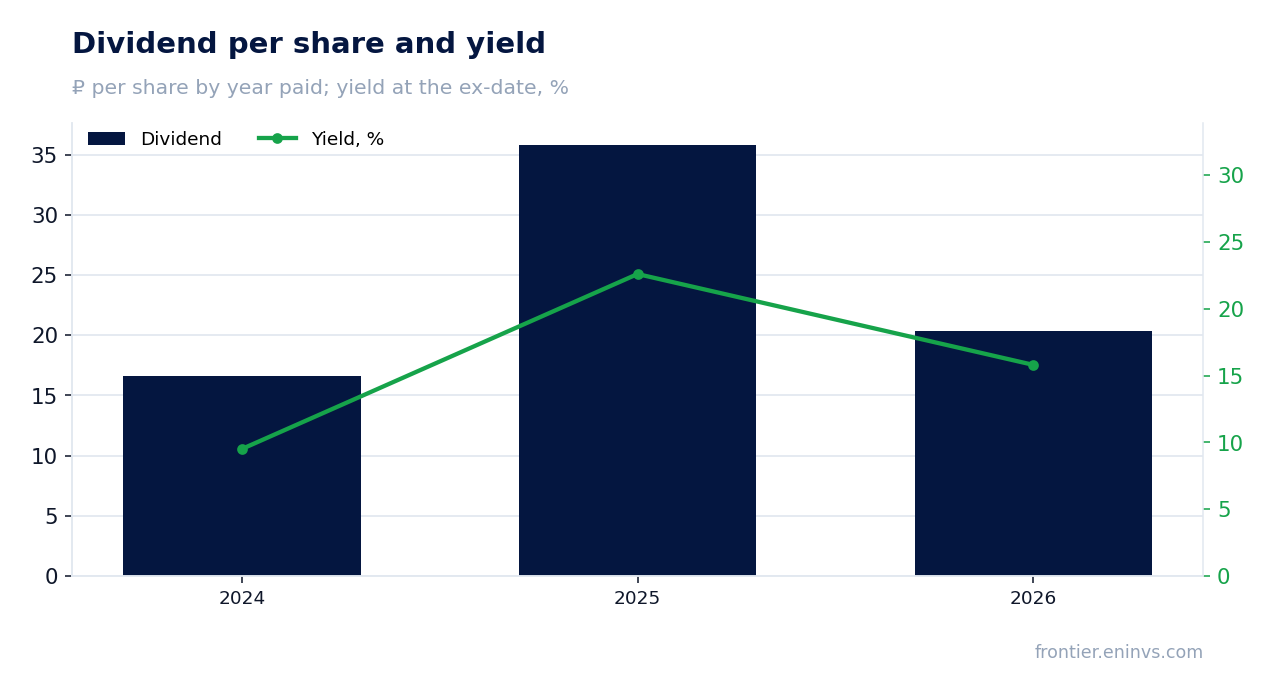
The payout history is uneven: 16.6 RUB per share for 2024 (9.5% at the ex-date price), 35.83 RUB for 2025 (22.6%), and 20.32 RUB for 2026 (15.8%). Dividends declared over nine months of 2026 were 2,032.0 mn RUB versus 1,371.0 mn RUB a year earlier, with 1,545.8 mn RUB actually paid.
The key risk to the dividend is profit. With a payout ratio of 0.61 of profit and a falling profit base, the company may cut the payout. If profit keeps declining at the same pace, the 31.93 RUB dividend could come under pressure. The 14.0% central bank key rate makes the current yield especially attractive relative to deposits.
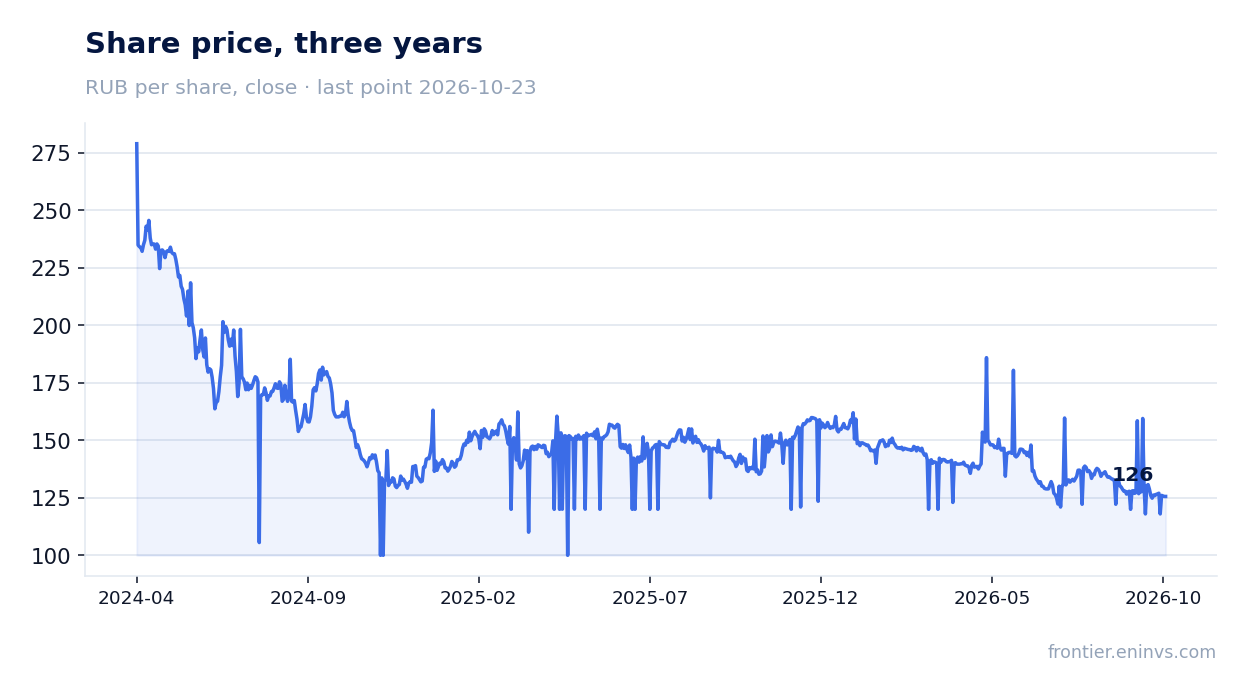
P/E LTM of 4.8 and ROE of 6.8% show the market is already pricing in further profit compression
With a market capitalisation of 13,125.0 mn RUB and trailing twelve-month profit of 2,746.1 mn RUB, the P/E LTM is 4.8. ROE is 6.8%, modest for a microfinance company. The portal's model puts upside to fair value at +22%.
The market values the company cheaply, but that reflects falling profit: 2,746.1 mn RUB over the last 12 months versus 3,237.0 mn RUB over nine months of 2025. If the current quarterly pace persists, annual profit could be even lower.
A 25.1% dividend yield against a 14.0% key rate creates a wide spread. But if profit keeps falling, the dividend may be cut, and the current yield would prove deceptive. A P/E of 4.8 looks low, but without a profit turnaround a re-rating is unlikely.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 13.1 bn ₽ |
| P/E (LTM) | 4.8 |
| P/B | 0.91 |
| ROE | 6.8% |
| Dividend yield (12m) | 25.1% |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2024 | 16.60 | 9.5% |
| 2025 | 35.83 | 22.6% |
| 2026 | 20.32 | 15.8% |
Bottom line
The report's strong point remains the dividend: 31.93 RUB per share yields 25.1% against a 14.0% key rate, and declared payouts over nine months rose to 2,032.0 mn RUB. But profit fell 48.0%, revenue 23.8%, and the decline has accelerated for three quarters in a row. The loan book is shrinking, quality remains weak, and personnel costs more than doubled. At a P/E LTM of 4.8 and +22% upside on the portal's model, the share looks rather attractive – but only for those willing to hold it for the dividend and accept the risk of a cut.
Open the company's financial profile ZAYM →
See also: market overview · valuation map · stock screeners