APPLIED OPTOELECTRONICS, INC.: revenue up 127.5%, yet the stock fell 21.1% after the report
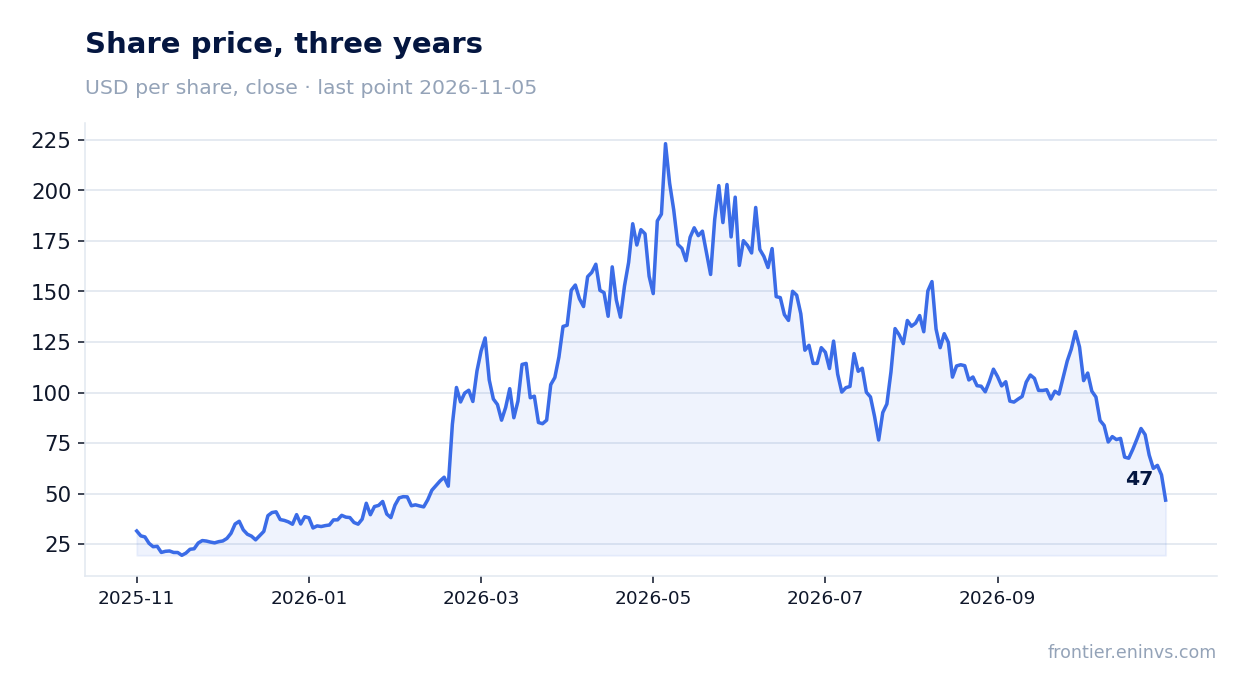
On November 5, APPLIED OPTOELECTRONICS, INC. released its third-quarter 2026 results. Revenue reached $269.9 million, up 127.5% year on year, EBITDA was $13.3 million, and net income came in at $6.3 million versus a $17.9 million loss a year earlier. Despite the return to profit and accelerating revenue growth compared with the second quarter, the market reacted with a 21.1% drop in the share price on the publication day. On our model, fair value is 62% below the current price, so the stock looks unattractive.
Key takeaways
— Revenue rose 127.5% year on year to $269.9 million, with acceleration versus the second quarter driven by the datacenter segment
— Gross margin rose to 28.2%, but the modest increase from 28.0% a year earlier does not explain the return to profit
— Net income of $6.3 million came mainly from $8.2 million of other income, not from operations
— The operating loss narrowed to $1.4 million, but the company has not yet reached operating profit
— Free cash flow remains negative: operating cash flow of minus $2.9 million alongside significant capital expenditure
— Net debt turned into a net cash position of $306.7 million, but this reflects capital raising rather than earnings
— Fourth-quarter guidance points to revenue of $385–420 million, implying further acceleration in growth
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 0.12 | 0.27 | +127.5% |
| EBITDA | -0.01 | 0.01 | to profit |
| Operating profit | -0.02 | -0.00 | — |
| Net profit | -0.02 | 0.01 | to profit |
| Operating cash flow | -0.03 | -0.00 | — |
| Capex | 0.05 | — | — |
| EBITDA margin | -9.1% | 4.9% | +14.0 pp |
| Net margin | -15.1% | 2.3% | +17.4 pp |
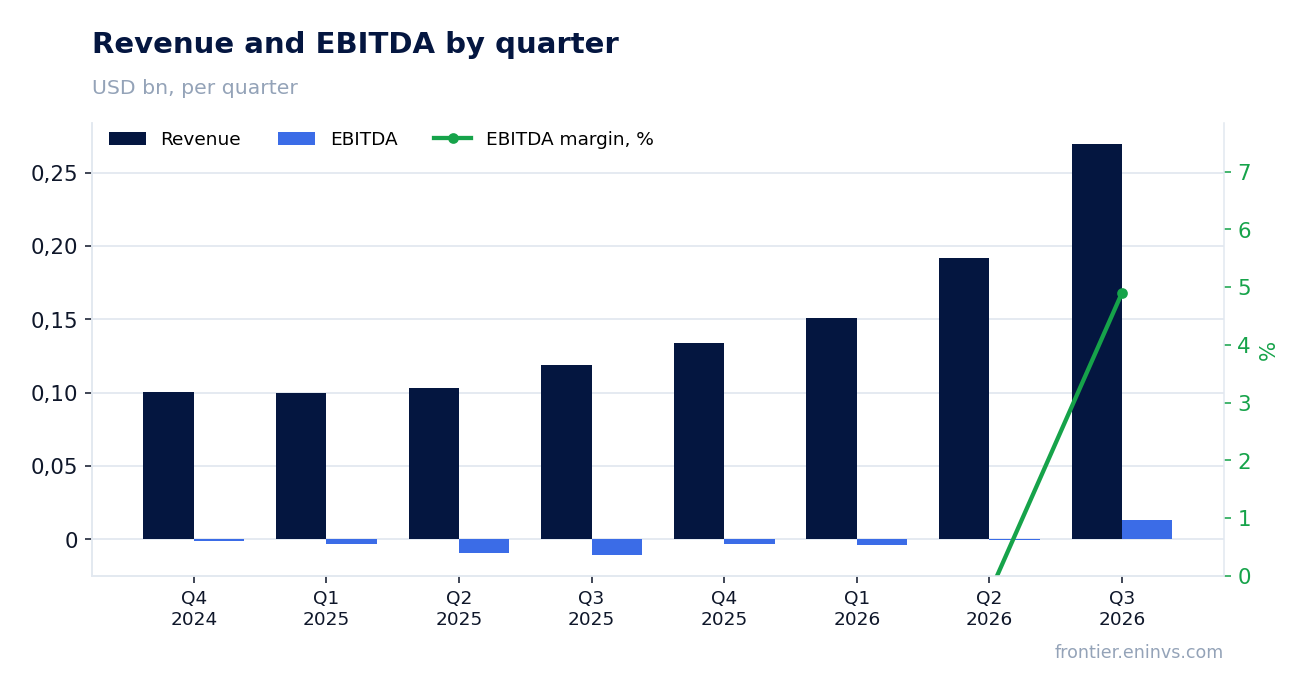
Revenue rose 127.5% year on year to $269.9 million, with acceleration versus the second quarter driven by the datacenter segment
Revenue in the third quarter of 2026 was $269.9 million, up 127.5% from $118.6 million a year earlier. Sequentially, growth accelerated from 86.4% in the second quarter. The datacenter segment was the main contributor, with revenue reaching $155.6 million versus $43.9 million a year earlier, more than tripling.
The CATV segment also showed strong dynamics: revenue rose to $110.9 million from $70.6 million a year earlier. Telecom remained insignificant at $2.7 million. Thus, growth is concentrated in the two key segments tied to artificial intelligence and broadband access.
The company confirmed it had secured a multi-year strategic agreement with a Tier 1 hyperscale customer, providing longer-term revenue visibility. Fourth-quarter guidance of $385–420 million implies further acceleration in growth.
Gross margin rose to 28.2%, but the modest increase from 28.0% a year earlier does not explain the return to profit
Gross margin in the reported quarter was 28.2% versus 28.0% a year earlier and 27.7% in the second quarter of 2026. The 0.2 percentage point year-on-year improvement is too small to explain the swing from loss to profit. Gross profit rose to $76.2 million from $33.3 million, but that is a consequence of revenue growth, not efficiency gains.
Operating expenses increased to $77.6 million from $51.5 million a year earlier, including research and development costs of $38.1 million and general and administrative expenses of $31.6 million. As a result, the operating loss narrowed to $1.4 million from $18.2 million, but the company has not yet reached operating profit.
Adjusted EBITDA as reported by the company was $28.5 million, above our $13.3 million estimate, because the company excludes stock-based compensation and other items. We take a conservative approach and use EBITDA of $13.3 million.
Net income of $6.3 million came mainly from $8.2 million of other income, not from operations
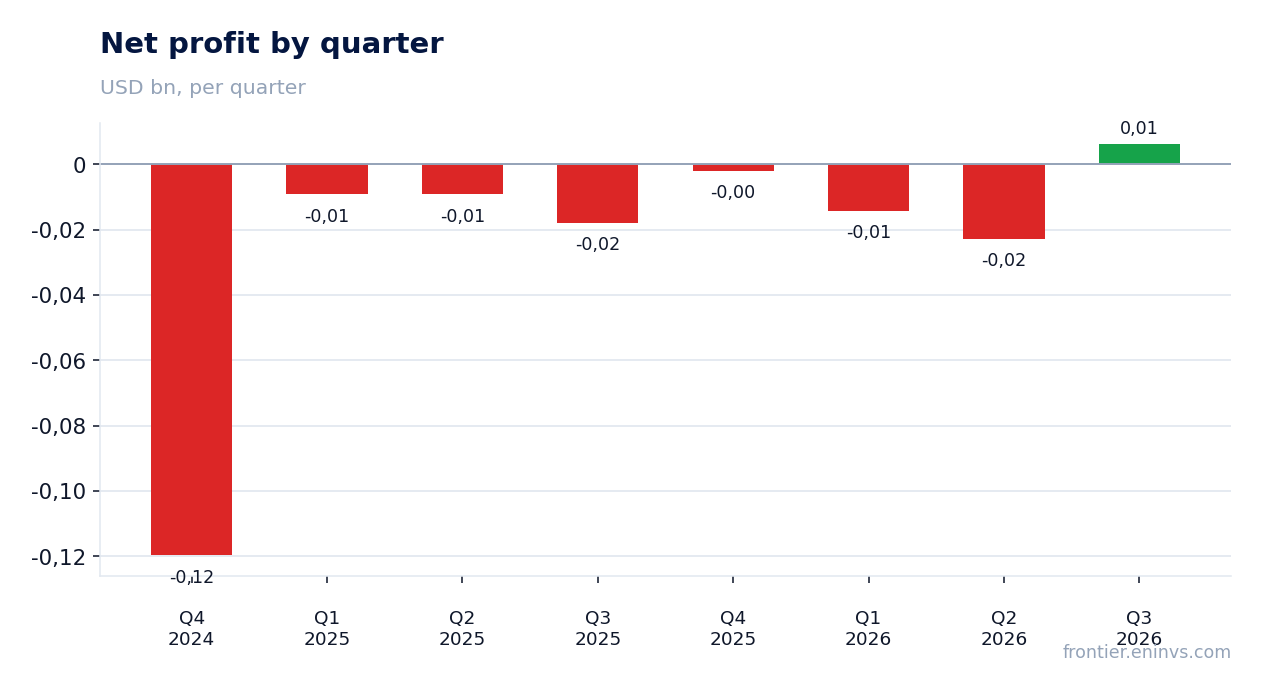
Net income in the third quarter was $6.3 million versus a $17.9 million loss a year earlier. However, the operating loss remained at $1.4 million, and profit was generated by $8.2 million of other income and $3.1 million of interest income. Without these items, the company would have remained in loss.
The net margin was 2.3% versus negative 15.1% a year earlier. The improvement is largely due to one-off factors rather than sustainable operating efficiency gains. Non-GAAP net income as reported by the company was $14.8 million, but it also excludes a number of expenses.
For sustainable profitability, the company needs to achieve positive operating profit rather than rely on other income.
The operating loss narrowed to $1.4 million, but the company has not yet reached operating profit
The operating loss in the third quarter of 2026 was $1.4 million versus $18.2 million a year earlier. The reduction came from revenue growth outpacing operating expense growth. Nevertheless, the company remains loss-making at the operating level.
Research and development expenses rose to $38.1 million from $21.3 million, reflecting investment in new products including 800G and 1.6T. Sales and marketing expenses declined to $7.9 million from $9.9 million, while general and administrative expenses rose to $31.6 million from $20.3 million.
Reaching operating profit is the key question for confirming the sustainability of the business model. Fourth-quarter guidance implies further revenue growth, which could improve the operating result.
Free cash flow remains negative: operating cash flow of minus $2.9 million alongside significant capital expenditure
Operating cash flow in the third quarter of 2026 was negative at minus $2.9 million. Over the trailing twelve months, operating cash flow was also negative at minus $106.2 million. The company does not yet generate sustainable cash flow from operations.
Capital expenditure remains high: $285.6 million in the second quarter and $58.2 million in the first. The company did not disclose the exact figure for the third quarter, but given capacity expansion it remains significant. This puts pressure on free cash flow.
The company is expanding manufacturing capacity: by the end of 2026 it plans to install equipment to produce over 500,000 units of 800G and 1.6T per month, and over 1 million units by the end of 2027. This requires further investment.
Net debt turned into a net cash position of $306.7 million, but this reflects capital raising rather than earnings
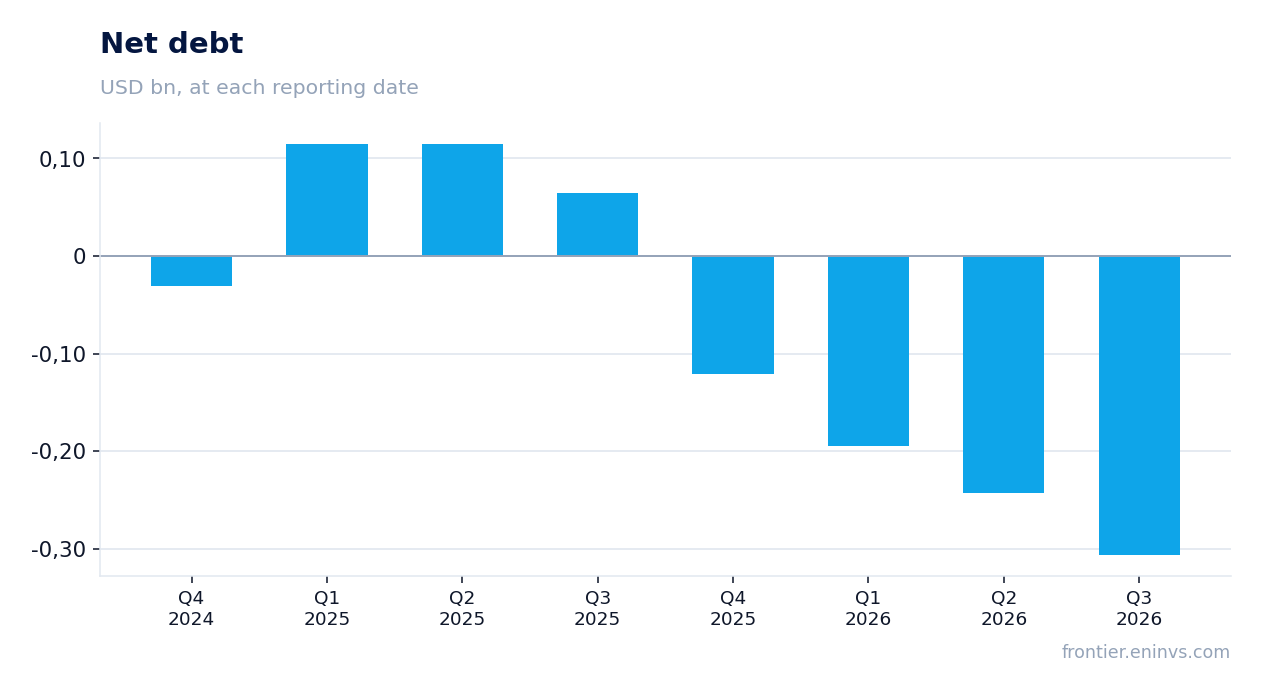
As of September 30, 2026, net debt was negative at minus $306.7 million, meaning the company has a net cash position. A year earlier, on September 30, 2025, net debt was $0.1 billion, and on June 30, 2026, it was minus $0.2 billion. The change over 12 months was minus $0.4 billion.
The improvement in the debt position came from capital raising: shareholders' equity rose to $2.24 billion from $0.73 billion at the end of 2025, and cash increased to $621.5 million. This provides financial stability but does not indicate an ability to generate profit.
Interest expense was $1.2 million, and interest income was $3.1 million. Net debt is negative, which reduces risks, but the company still depends on external financing to sustain growth.
Fourth-quarter guidance points to revenue of $385–420 million, implying further acceleration in growth
The company guides fourth-quarter 2026 revenue to a range of $385–420 million. That is well above $134.3 million in the fourth quarter of 2025, implying growth of 2.9–3.1 times. Such guidance points to further acceleration compared with the third quarter.
Guidance for non-GAAP gross margin is 29.5–31%, and for non-GAAP net income $45.9–60.4 million, or $0.48–0.63 per share. The company expects revenue growth and margin improvement to drive a substantial increase in profit.
However, meeting the guidance depends on expanding manufacturing capacity and timely deliveries. The company noted that its US capacity expansion may take longer due to electrical power issues.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 3.96 bn USD |
| P/B | 5.39 |
| Operating cash flow (LTM) | -0.11 bn |
| ROE | 0.4% |
Bottom line
The strong points of the report were revenue growth of 127.5% and a return to net profit, as well as an improvement in the debt position to a net cash position of $306.7 million. However, profit was largely supported by other income, the operating loss persists, and cash flow remains negative. Fourth-quarter guidance promises further acceleration, but its execution carries capacity expansion risks. On our model, fair value is 62% below the current price, making the stock unattractive to buy at current levels.
Open the company's financial profile AAOI →
See also: market overview · valuation map · stock screeners