AMGEN INC: revenue up 8.8%, but the margin came from lower amortisation, not operations
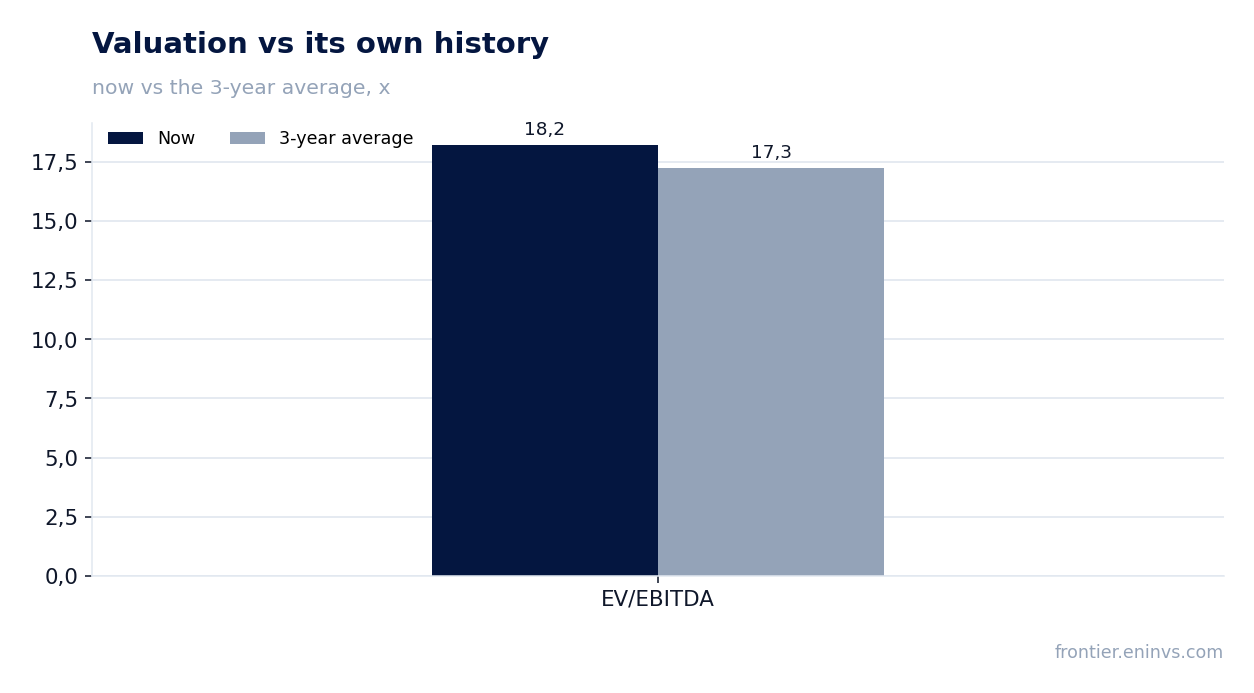
On 3 November AMGEN INC reported third-quarter 2026 results. Revenue reached $10.4 billion (+8.8% year on year), GAAP operating profit was $3.7 billion and operating cash flow $4.2 billion. Growth decelerated from +9.5% in the second quarter, and the 9.9 pp jump in the operating margin came from lower amortisation of acquired assets rather than from operations. At an EV/EBITDA of 18.2 against its own three-year average of 17.3 the share is more expensive than its own history, so at the current price it looks neutral.
Key takeaways
— Revenue grew 8.8%, but growth decelerated from 9.5% in the second quarter
— The GAAP margin rose 9.9 pp on lower amortisation, not on cost savings
— Prolia and XGEVA are losing sales to biosimilars while Repatha and UPLIZNA grow fast
— Free cash flow fell to $3.7 billion on working capital
— Net debt at 2.85 EBITDA is a moderate load, but the direction of debt is not disclosed
— The dividend rose 6% to $2.52 per share, a 2.15% yield
— EV/EBITDA of 18.2 is 6% above its own three-year average of 17.3
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 9.56 | 10.4 | +8.8% |
| EBITDA | 3.83 | — | — |
| Operating profit | 2.53 | 3.70 | +46.5% |
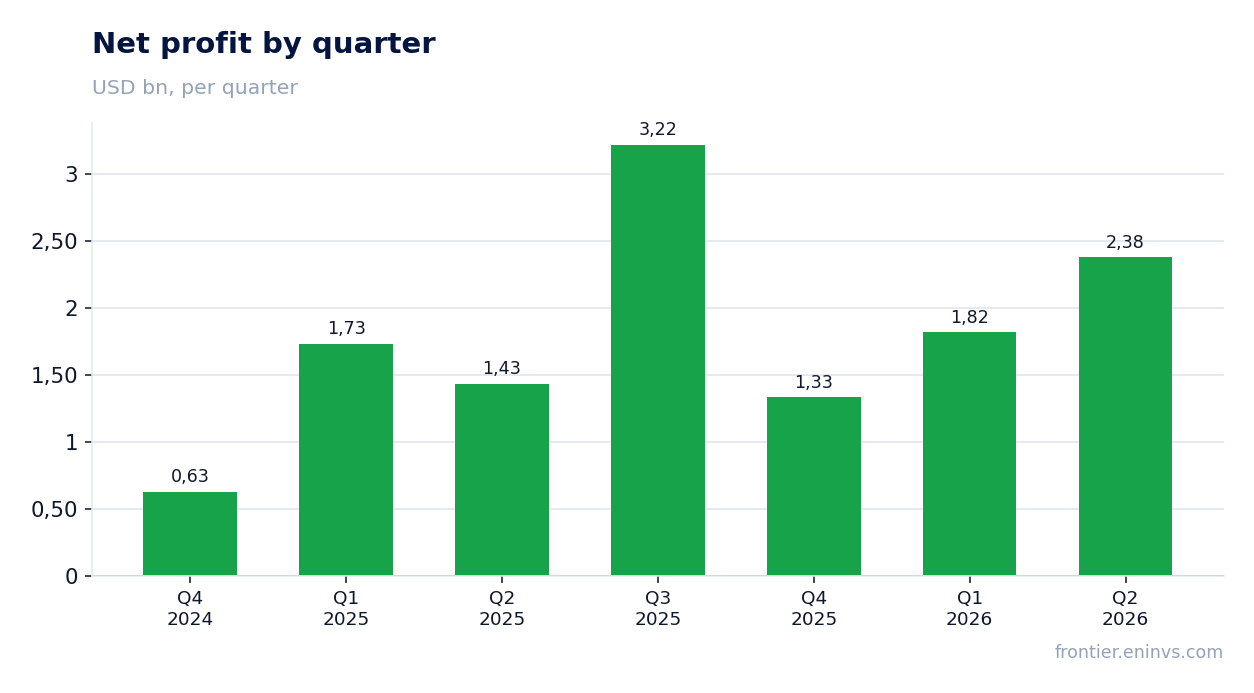
| Net profit | 3.22 | — | — |
| Operating cash flow | 4.68 | 4.20 | -10.3% |
| Capex | 0.44 | — | — |
| EBITDA margin | 40.1% | — | — |
| Net margin | 33.7% | — | — |
Revenue grew 8.8%, but growth decelerated from 9.5% in the second quarter
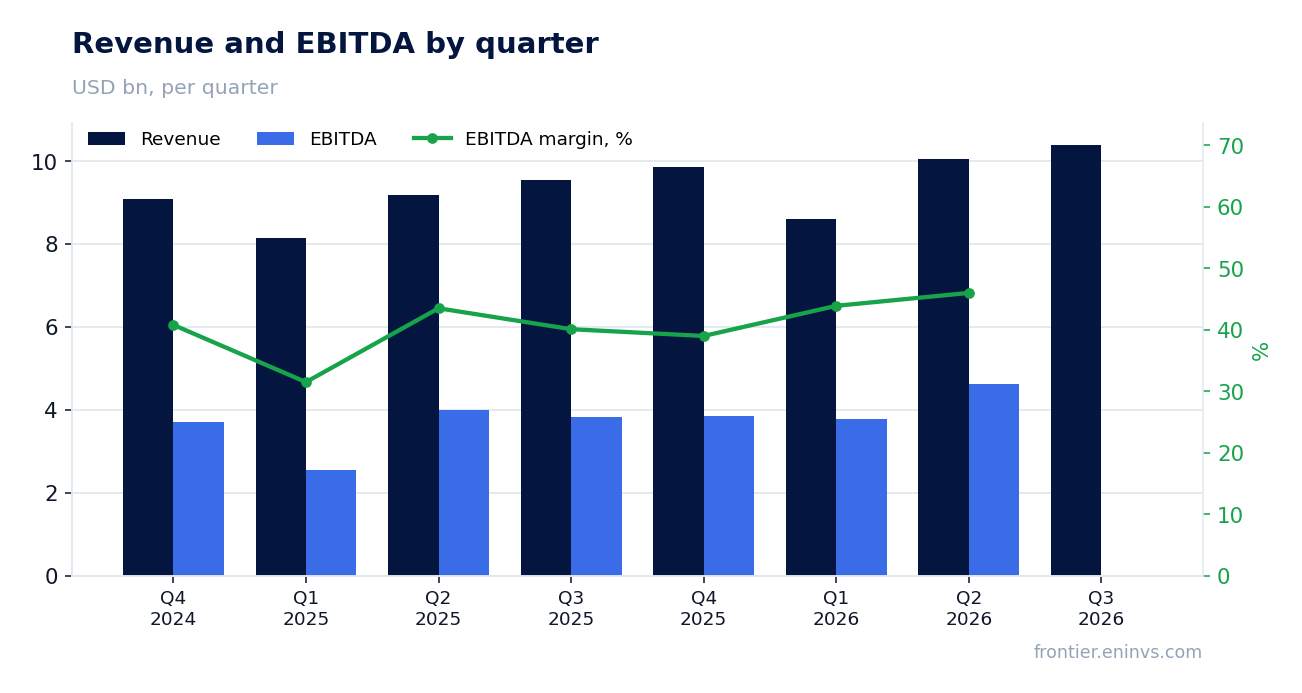
In the third quarter of 2026 AMGEN INC revenue reached $10.4 billion, up 8.8% year on year. Growth in the second quarter was 9.5%, so the pace decelerated. Product sales rose 8% to $9.9 billion, driven by volume rather than price.
Seventeen products delivered double-digit sales growth, and seventeen are annualising above $1 billion on third-quarter sales. That points to a broad base of growth rather than a single drug. Still, the overall pace is below the prior quarter, and that is the main signal in the report.
The GAAP margin rose 9.9 pp on lower amortisation, not on cost savings
GAAP operating profit was $3.7 billion and the operating margin 37.5% against 27.6% a year earlier. The 9.9 pp gain looks impressive, but its source is accounting: cost of sales fell 10% to $2.8 billion, mainly on lower amortisation of acquired assets and lower manufacturing costs.
At the same time R&D rose 11% to $2.1 billion and SG&A fell 2% to $1.7 billion. The company did not economise on development; the margin was lifted by lower amortisation. On a non-GAAP basis the margin rose only 0.2 pp to 47.3%, which is a fairer picture of operating dynamics.
Prolia and XGEVA are losing sales to biosimilars while Repatha and UPLIZNA grow fast
Prolia sales fell 45% to $632 million and XGEVA 47% to $288 million as biosimilars launched globally. This is the largest negative of the quarter: the two drugs together lost about $750 million of sales year on year. Otezla fell 18% to $481 million and TEPEZZA 6% to $526 million.
Other products offset the decline. Repatha added 37% to $1,085 million, EVENITY 39% to $751 million, TEZSPIRE 43% to $538 million and UPLIZNA 191% to $451 million. IMDELLTRA rose 128% to $406 million. This set delivered the overall 8.8% revenue growth.
Free cash flow fell to $3.7 billion on working capital
Third-quarter operating cash flow was $4.2 billion against $4.7 billion a year earlier. Free cash flow fell to $3.7 billion from $4.2 billion, which the company attributes to working capital: the third quarter of 2025 benefited from the timing of rebates and collections. Capital expenditure rose to $0.6 billion from $0.4 billion.
Over the last twelve months operating cash flow was $12.0 billion on revenue of $38.9 billion. Cash generation therefore remains the base for dividends and debt service even though the quarter was weaker than last year's. For full-year 2026 the company plans capital expenditure of about $2.6 billion.
Net debt at 2.85 EBITDA is a moderate load, but the direction of debt is not disclosed
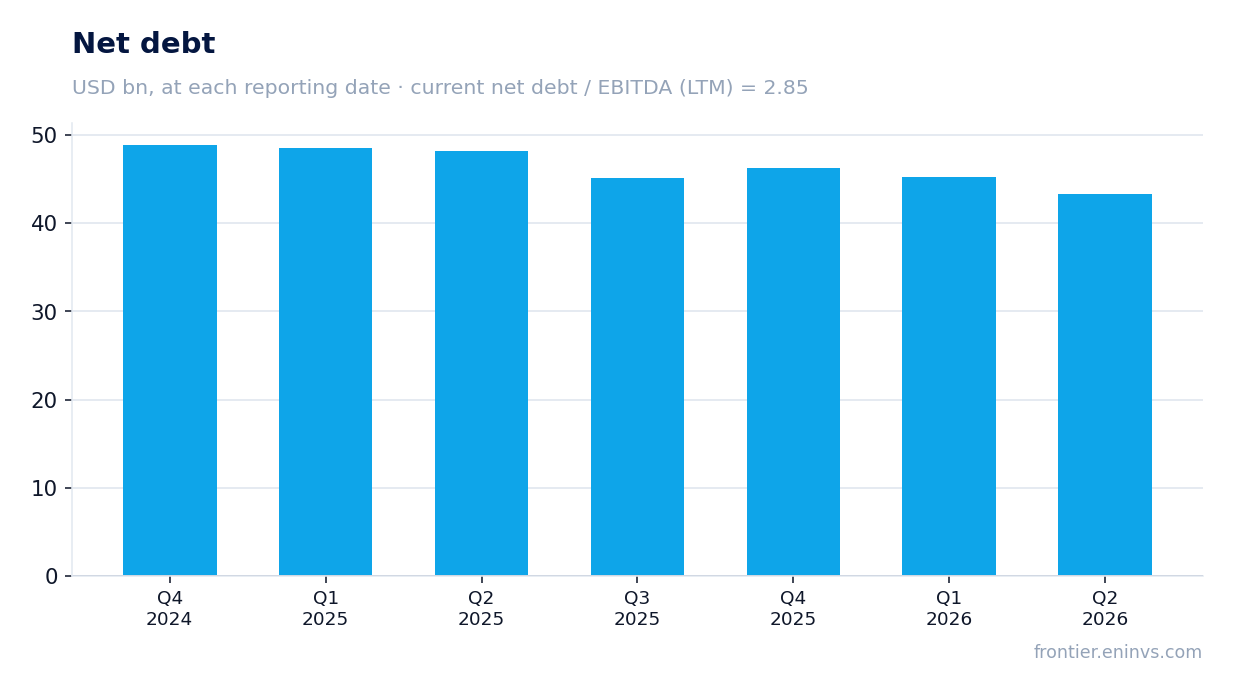
Net debt at the latest annual balance sheet was $46.3 billion, and net debt to trailing-twelve-month EBITDA was 2.85. That is a level the company services without strain: trailing EBITDA is $16.3 billion. At 30 September 2026 cash was $13.2 billion and debt $54.0 billion.
The direction of debt is not in the facts, so it cannot be said that leverage rose or fell. Only the level can be stated: 2.85 EBITDA is moderate but not conservative for a company paying dividends and running a buyback of up to $3 billion. Interest expense is not broken out in the release.
The dividend rose 6% to $2.52 per share, a 2.15% yield
For the third quarter of 2026 the company declared a dividend of $2.52 per share, 6% above a year earlier. It was paid on 11 September. The trailing-twelve-month yield is 2.15%, modest for the market but stable for a large biotech.
Our estimate for the full-year 2026 dividend is about $10 per share, based on four quarterly payments at the current growth rate. That is roughly 45% of guided non-GAAP EPS of $22.90–23.70, so the payout remains moderate. The risk to the payment is profit pressure from Prolia and XGEVA biosimilars, but trailing cash flow of $12.0 billion covers the dividend with room.
EV/EBITDA of 18.2 is 6% above its own three-year average of 17.3
The trailing-twelve-month EV/EBITDA is 18.2 against its own three-year average of 17.3, 6% above. The trailing P/E is 28.6. The market values the company above its three-year average despite decelerating revenue growth.
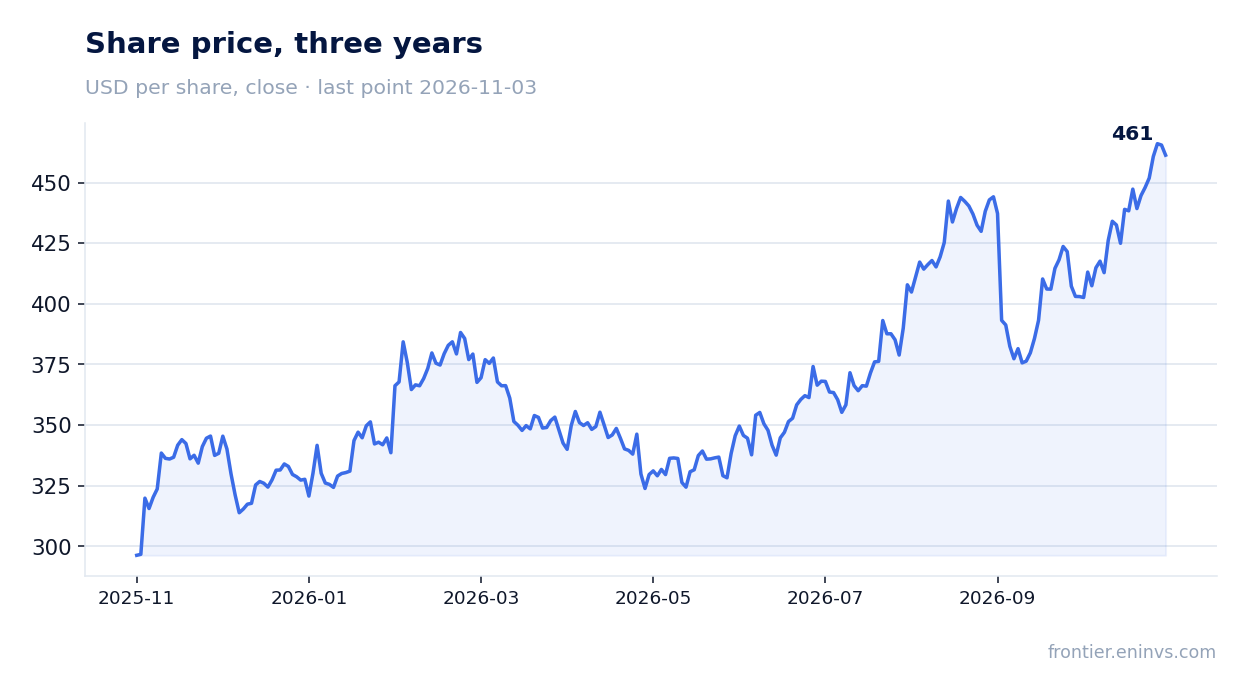
Our fair-value model puts the upside at +16% to the current price. That calculation rests on EBITDA growth and a target multiple, and it diverges from the market price, which already prices in a recovery. The share fell 0.9% on the release day and 0.9% from the release to 3 November.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 250 bn USD |
| P/E (LTM) | 28.6 |
| EV/EBITDA (LTM) | 18.2 |
| P/B | 28.88 |
| Net debt / EBITDA (LTM) | 2.85 |
| Operating cash flow (LTM) | 12.0 bn |
| ROE | 91.0% |
| Dividend yield (12m) | 2.2% |
| EV/EBITDA, 3-year average | 17.3 |
Bottom line
The quarter's strength remains its broad growth base: Repatha, EVENITY, TEZSPIRE and UPLIZNA together added more than Prolia and XGEVA lost. But the 9.9 pp margin jump is accounting-driven, from amortisation, not operational. Free cash flow fell to $3.7 billion, which matters more than the headline margin. At EV/EBITDA of 18.2 against its own average of 17.3 the share is above its history, and at the current price it is neutral: a 2.15% dividend yield and moderate debt do not provide enough cushion to offset decelerating growth.
Open the company's financial profile AMGN →
See also: market overview · valuation map · stock screeners