American Tower: revenue up 2.5% but net income down 14.4% on unrealized investment losses
On October 27, American Tower released its third-quarter 2026 results. Revenue rose 2.5% to $2,785.4 million, adjusted EBITDA grew 0.9% to $1,832 million, while net income fell 14.4% to $780.8 million. The profit decline stems not from operations but from unrealized losses on equity investments of $71.5 million versus gains of $10.9 million a year earlier. Given steady cash flow, declining net debt and dividend yield, the stock looks rather attractive than neutral.
Key takeaways
— Revenue grew 2.5% but the pace decelerated from 4.7% a quarter earlier
— The 14.4% net income decline is due to paper investment losses, not operations
— Adjusted EBITDA added just 0.9%, margin slipped to 65.8%
— Free cash flow rose 0.2% to $986 million on lower capex
— Net debt fell $7.5 billion over the quarter to $35.7 billion
— The $1.79 per share dividend grew 5.3% and yields about 4%
— The company raised its 2026 outlook for the third time, mainly on data centers
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 2.72 | 2.79 | +2.5% |
| EBITDA | 1.76 | 1.79 | +1.8% |
| Operating profit | 1.23 | 1.27 | +2.9% |
| Net profit | 0.91 | 0.78 | -14.4% |
| Operating cash flow | 1.46 | 1.39 | -4.6% |
| Capex | 0.47 | 0.40 | -14.6% |
| EBITDA margin | 64.6% | 64.2% | -0.4 pp |
| Net margin | 33.6% | 28.0% | -5.6 pp |
Revenue grew 2.5% but the pace decelerated from 4.7% a quarter earlier
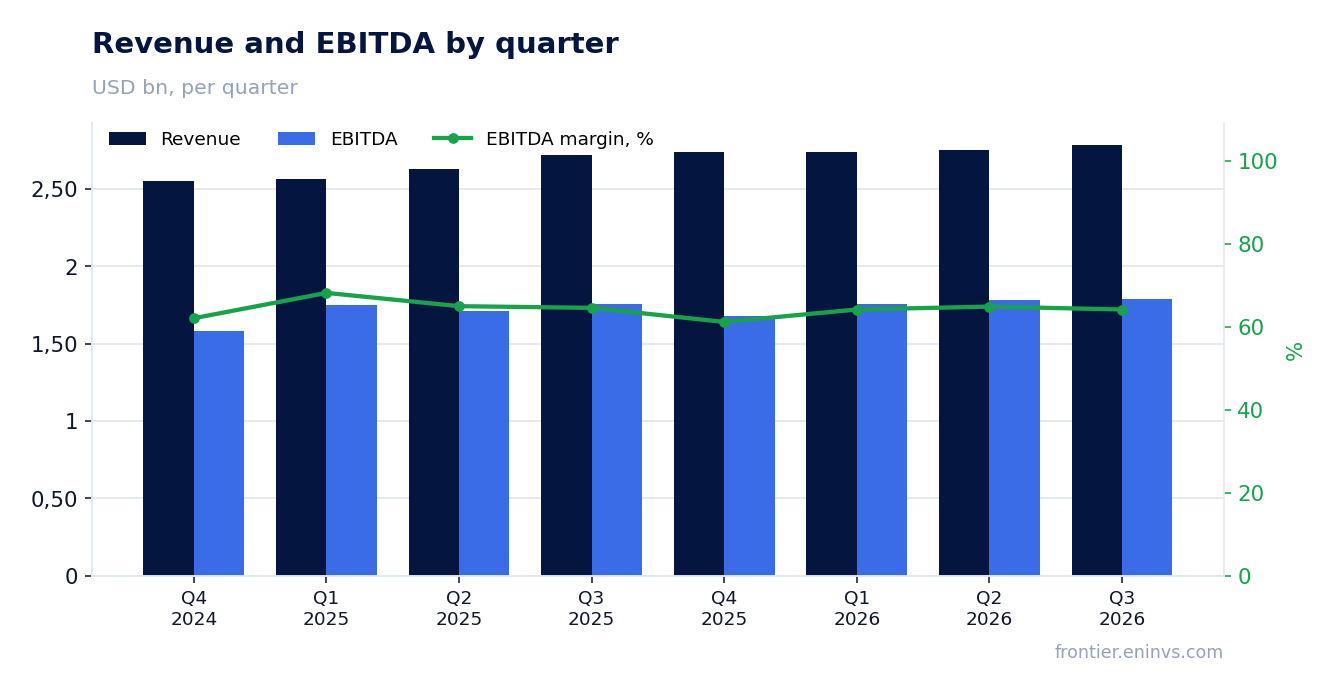
Revenue in the third quarter of 2026 was $2,785.4 million, up 2.5% year on year. A quarter earlier growth was 4.7%, so the dynamics decelerated. The slowdown is partly due to a decrease in non-cash straight-line revenue: in the reported quarter it was minus $24.0 million versus plus $27.7 million a year earlier.
The main contribution came from the data center segment, where revenue grew 16.3% in cash terms. Organic tenant billings growth was 1.1%, reflecting the maturity of the tower portfolio. The U.S. & Canada segment is forecast to see a 3.0% revenue decline for the year, again due to straight-line revenue.
For the investor, what matters is not the pace itself but its sustainability. A deceleration to 2.5% while data centers keep growing and the tower business remains stable looks more like normalization than a warning sign. However, if the slowdown continues, it will limit future dividend growth.
The 14.4% net income decline is due to paper investment losses, not operations
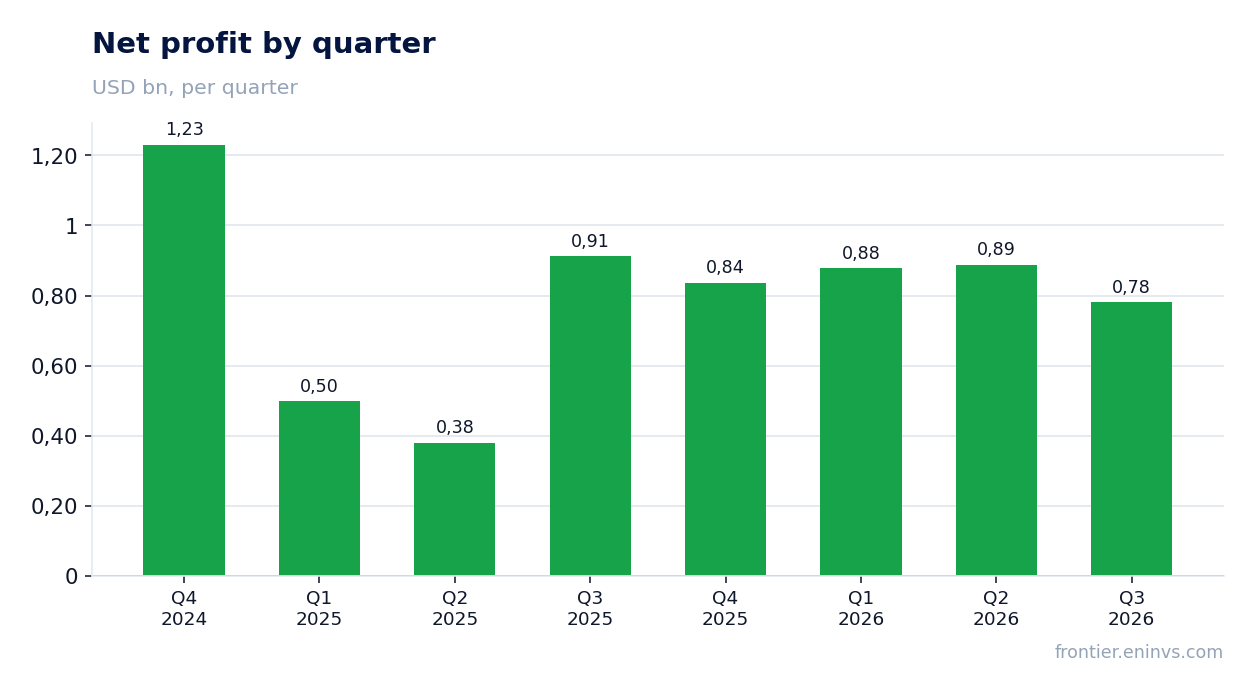
Net income in the reported quarter was $780.8 million, down 14.4% year on year. The release explicitly states that the dynamics were affected by unrealized losses on equity investments of $71.5 million versus unrealized gains of $10.9 million a year earlier. These are paper, non-cash items unrelated to operations.
Operating profit, meanwhile, rose to $1,269.0 million from $1,233.3 million a year earlier. Adjusted EBITDA increased 0.9% to $1,832 million. So the operating business continued to grow, and the profit decline is explained solely by financial items.
The net margin fell to 28.0% from 33.6% a year earlier, but that is a consequence of the same one-off factors. Without them, profit would have been higher. To assess business sustainability, it is more important to look at EBITDA and cash flow, which remain stable.
Adjusted EBITDA added just 0.9%, margin slipped to 65.8%
Adjusted EBITDA in the third quarter of 2026 was $1,832 million, up 0.9% year on year. Growth is modest and lags revenue growth. The EBITDA margin slipped to 65.8% from 64.6% a year earlier, according to the release. The margin decline is partly due to a decrease in non-cash straight-line revenue, net, of $31.7 million versus plus $18.3 million a year earlier.
Adjusted EBITDA is a key metric for a REIT as it reflects the ability to generate cash flow to pay dividends. Growth of just 0.9% amid cost inflation means the company is not yet fully translating revenue growth into profit. However, management expects Adjusted EBITDA to grow 2.0% for the full year.
Importantly, the margin remains very high – above 65%. This is typical of the tower business with high operating efficiency. A 1.2 percentage point decline does not change the picture dramatically but warrants monitoring.
Free cash flow rose 0.2% to $986 million on lower capex
Operating cash flow in the third quarter was $1,392.8 million, down 4.6% year on year. However, capital expenditures fell 14.6% to $407 million, including $9.1 million of finance lease payments. As a result, free cash flow rose 0.2% to $986 million.
The capex decline reflects investment discipline. The company confirmed its full-year capex guidance of $1,765–1,875 million, including $695 million for data center development. This means capital expenditures may rise in the fourth quarter, putting pressure on free cash flow.
Nevertheless, the ability to generate almost $1 billion of free cash flow per quarter amid high leverage is an important support for the dividend. AFFO per share was $2.87, up 3.2% year on year.
Net debt fell $7.5 billion over the quarter to $35.7 billion
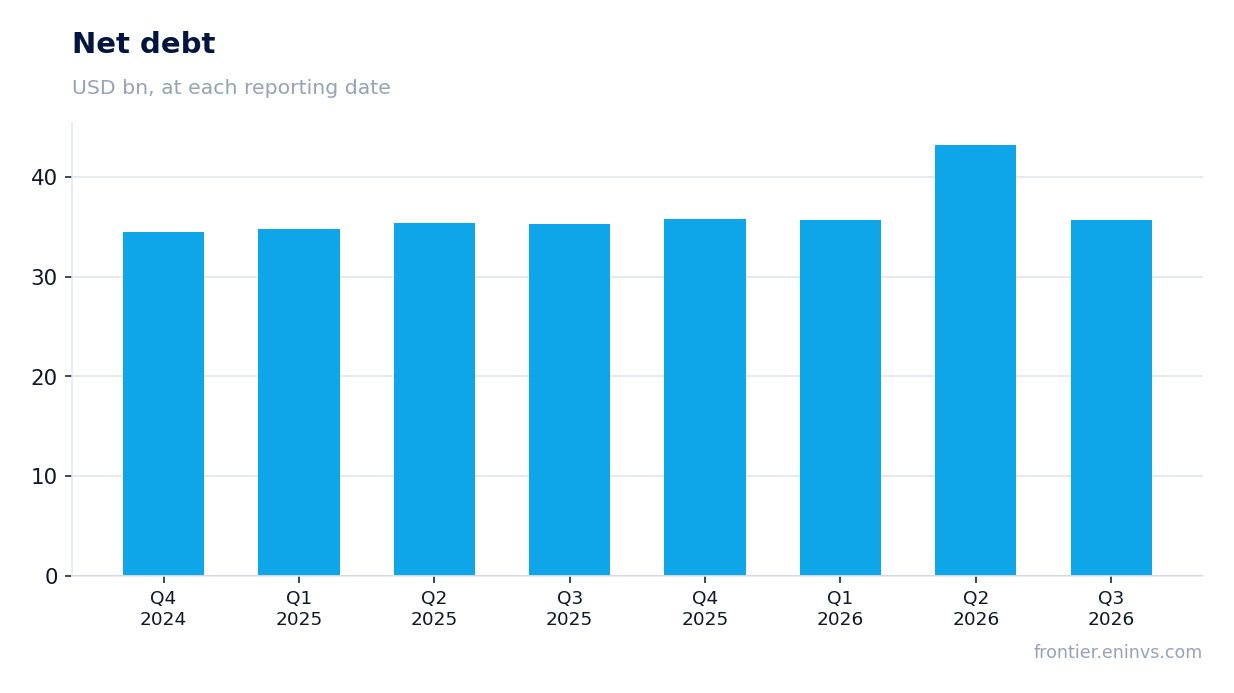
Net debt as of September 30, 2026 was $35.7 billion. Compared with June 30, 2026, it decreased by $7.5 billion. Over the year, from September 30, 2025, net debt increased by $0.4 billion. The quarterly decline is due to debt repayment and refinancing: in September the company repaid $600 million at 1.450% and issued new notes for $1.6 billion.
The net debt / adjusted EBITDA ratio for the quarter is 4.9x. This is a moderate level for an infrastructure REIT, though higher than some peers. The company has significant liquidity – $10.6 billion, including $1.9 billion of cash and $8.7 billion available under credit facilities.
The quarterly debt reduction is a positive signal, but the annual dynamics show that debt remains stable. For the investor, it is important that the company refinances debt amid rising rates, which could increase interest expenses in the future.
The $1.79 per share dividend grew 5.3% and yields about 4%
For the third quarter of 2026, the company declared a dividend of $1.79 per share, up 5.3% year on year. Total dividends amounted to $831 million. At the current share price, the dividend yield is about 4%. This is above the average yield in recent years and competitive compared to the yield on 10-year U.S. Treasuries.
Our estimate for the 2026 dividend is about $7.16 per share, based on four quarterly payments. This corresponds to a payout ratio of about 65% of AFFO per share, which the company forecasts at $11.04–11.16. This payout level is sustainable and leaves room for growth.
The risk of a dividend cut is linked to a possible slowdown in AFFO growth, for example, due to rising interest expenses or slower organic growth. However, current free cash flow and the AFFO forecast support the dividend. The company is also actively buying back shares: $315 million during the quarter, and after the reporting date the board authorized an additional $2.0 billion buyback.
The company raised its 2026 outlook for the third time, mainly on data centers
American Tower raised its 2026 property revenue guidance by $55 million at the midpoint to $10,785–10,865 million. This is the third upward revision this year. The main reason is the outperformance of the data center segment, whose revenue is forecast to grow 16.1% to $1,218–1,228 million. Adjusted EBITDA guidance remained unchanged at $7,248–7,303 million.
Net income and earnings per share guidance was lowered by $30 million due to unrealized losses on equity investments. AFFO per share guidance was raised by $0.02 to $11.04–11.16. This reflects management's confidence in cash flow.
The guidance raise is a positive signal, but it should be noted that growth is mainly driven by data centers, not the core tower business. Organic tenant billings growth in the U.S. & Canada is expected at about 0.5%, close to zero. This limits long-term growth potential.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Operating cash flow (LTM) | 5.71 bn |
| ROE | 28.8% |
Bottom line
American Tower delivered stable operating results: revenue grew 2.5%, adjusted EBITDA rose 0.9%, and free cash flow remained around $1 billion. The 14.4% net income decline was caused by paper investment losses and does not reflect a deterioration in the business. The company reduced net debt by $7.5 billion over the quarter and raised its full-year guidance. The $1.79 per share dividend with a yield of about 4% looks sustainable. The question for the holder is the ability to accelerate organic growth, which is currently just 1.1%.
Open the company's financial profile AMT →
See also: market overview · valuation map · stock screeners