American Express: revenue up 92.6% but profit only 27.9% – growth is eating the margin
American Express reported third-quarter 2026 results: revenue of 20,062 million dollars, net profit of 3,712 million, and a net margin of 18.5% versus 27.9% a year earlier. Revenue grew 92.6% year on year, an acceleration from the second quarter (+90.3%), but profit added only 27.9%, and net debt on the balance sheet at 30 September 2026 turned negative – minus 41,788 million dollars. The share looks neutral: revenue growth and a net cash position are strong, but the margin decline and the absence of EBITDA data keep the valuation from being attractive.
Key takeaways
— Third-quarter revenue grew 92.6% year on year, an acceleration from +90.3% in the second quarter
— Net profit added only 27.9%, and the margin fell from 27.9% to 18.5% – revenue growth is costing more
— Operating cash flow for the quarter was 5,384 million dollars against capex of 947 million
— Net debt at 30 September 2026 turned negative – minus 41,788 million dollars
— Return on equity of 14.1% with a net cash position – there is a buffer, but it is not in the margin
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 10.4 | 20.1 | +92.6% |
| EBITDA | 4.28 | — | — |
| Operating profit | 3.83 | — | — |
| Net profit | 2.90 | 3.71 | +27.9% |
| Operating cash flow | 6.23 | 5.38 | -13.6% |
| Capex | 0.65 | 0.95 | +44.8% |
| EBITDA margin | 41.1% | — | — |
| Net margin | 27.9% | 18.5% | -9.4 pp |
Third-quarter revenue grew 92.6% year on year, an acceleration from +90.3% in the second quarter
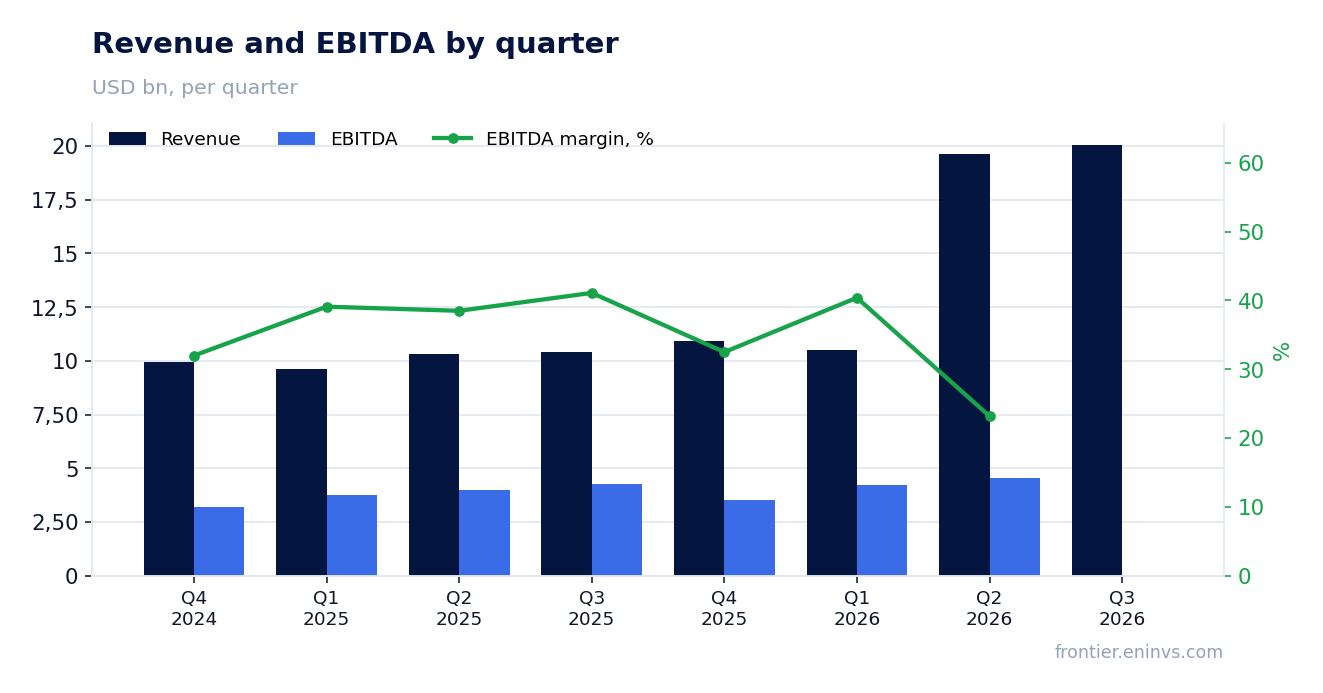
Third-quarter 2026 revenue was 20,062 million dollars, 92.6% more than a year earlier. In the second quarter growth was 90.3%, so the pace accelerated. This is the second consecutive quarter of roughly 90% growth, whereas in the first quarter of 2026 revenue grew only 9.3%.
Such a jump does not look like the organic dynamics of a payments company: doubling revenue in a year requires an explanation that the provided facts do not contain. We record the fact of acceleration and its scale, but do not attribute a cause that cannot be confirmed.
Net profit added only 27.9%, and the margin fell from 27.9% to 18.5% – revenue growth is costing more
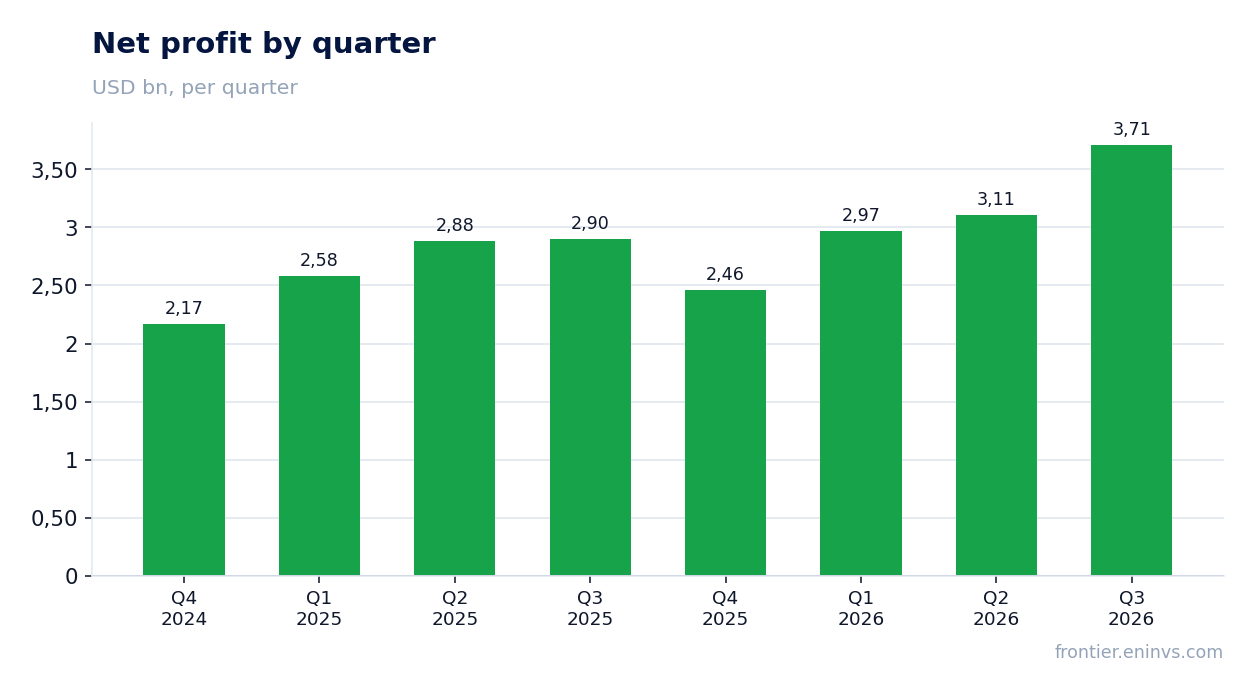
Third-quarter 2026 net profit was 3,712 million dollars, 27.9% more than a year earlier. With revenue up 92.6%, profit grew three times slower than revenue.
The net margin fell to 18.5% from 27.9% a year earlier. The reason is that costs are growing faster than revenue; which lines drive this does not follow from the facts. For a holder this is the main signal of the report: the scale of the business is increasing, but each unit of revenue brings noticeably less profit.
Operating cash flow for the quarter was 5,384 million dollars against capex of 947 million
Third-quarter 2026 operating cash flow was 5,384 million dollars, capital expenditures – 947 million. Free cash flow therefore remains positive and exceeds 4.4 billion dollars.
Over the trailing twelve months operating cash flow was 17,626 million dollars. This is a stable base for payouts and investment, and it does not depend on one-off profit items.
Net debt at 30 September 2026 turned negative – minus 41,788 million dollars
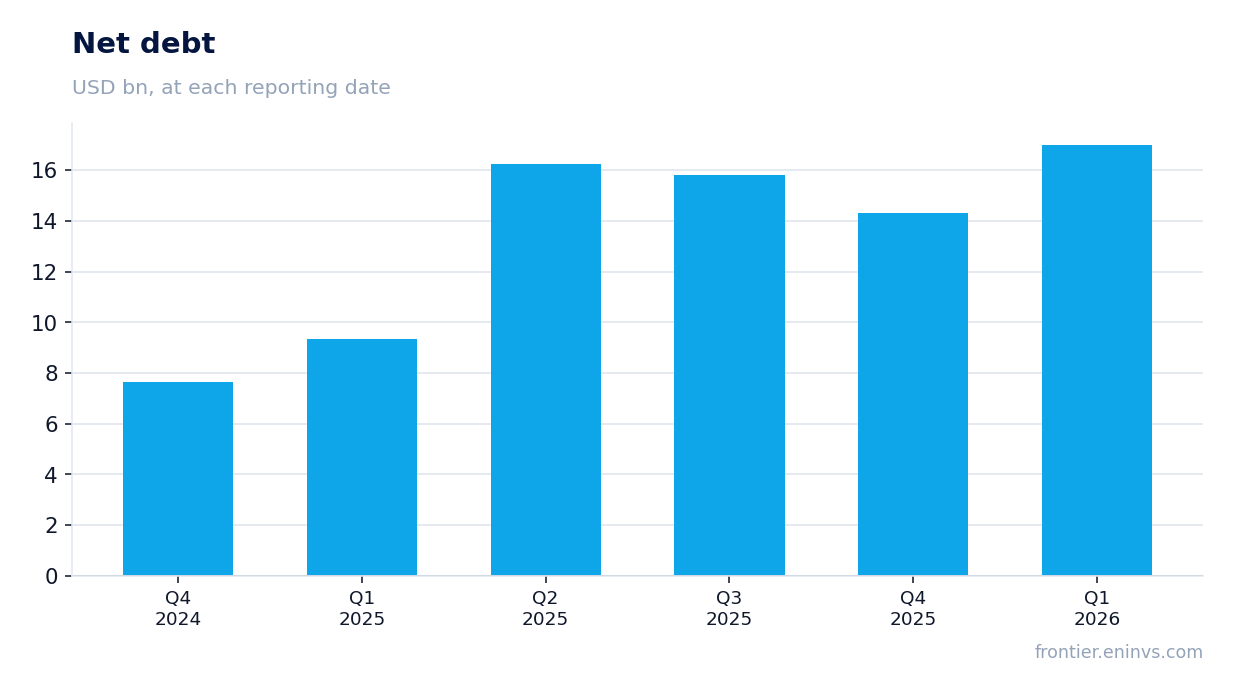
At 30 September 2026 net debt was minus 41,788 million dollars, meaning cash exceeds debt obligations. At 30 June 2026 net debt was positive – 15.6 billion dollars; the change over the quarter was minus 57.4 billion.
A year earlier, at 30 September 2025, net debt was 15.8 billion dollars; the change over 12 months was minus 57.6 billion. The move into a net cash position is a strength of the balance sheet, but it does not offset the margin decline.
Return on equity of 14.1% with a net cash position – there is a buffer, but it is not in the margin
Return on equity is 14.1%. With negative net debt (minus 41,788 million dollars) the company does not depend on debt financing, which reduces balance-sheet risk.
However, the return on equity itself is not high for a payments business, and its source is not the margin, which fell to 18.5%. Until the margin recovers, return on equity is unlikely to rise noticeably.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Operating cash flow (LTM) | 17.6 bn |
| ROE | 14.1% |
Bottom line
The strong side of the report is revenue: 20,062 million dollars and 92.6% year-on-year growth, accelerating from the second quarter. The weak side is profit: 3,712 million dollars, up only 27.9%, with the margin down to 18.5%. The net cash position (minus 41,788 million dollars) and operating cash flow (5,384 million for the quarter) provide a buffer but do not resolve the margin question. The verdict is neutral: the share looks neither attractive nor unattractive until there is clarity on the causes of the margin decline and the sustainability of revenue growth.
Open the company's financial profile AXP →
See also: market overview · valuation map · stock screeners