nVent Electric plc: revenue up 43.7%, yet the market met the report with an 8.8% share-price drop
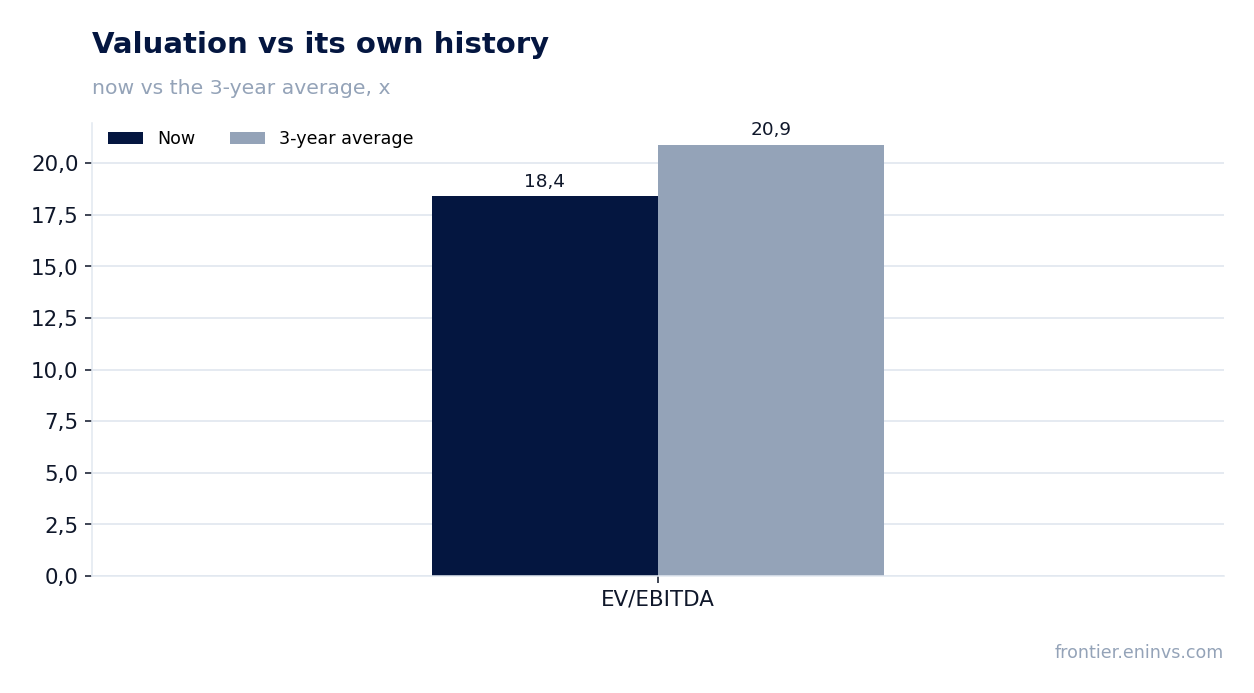
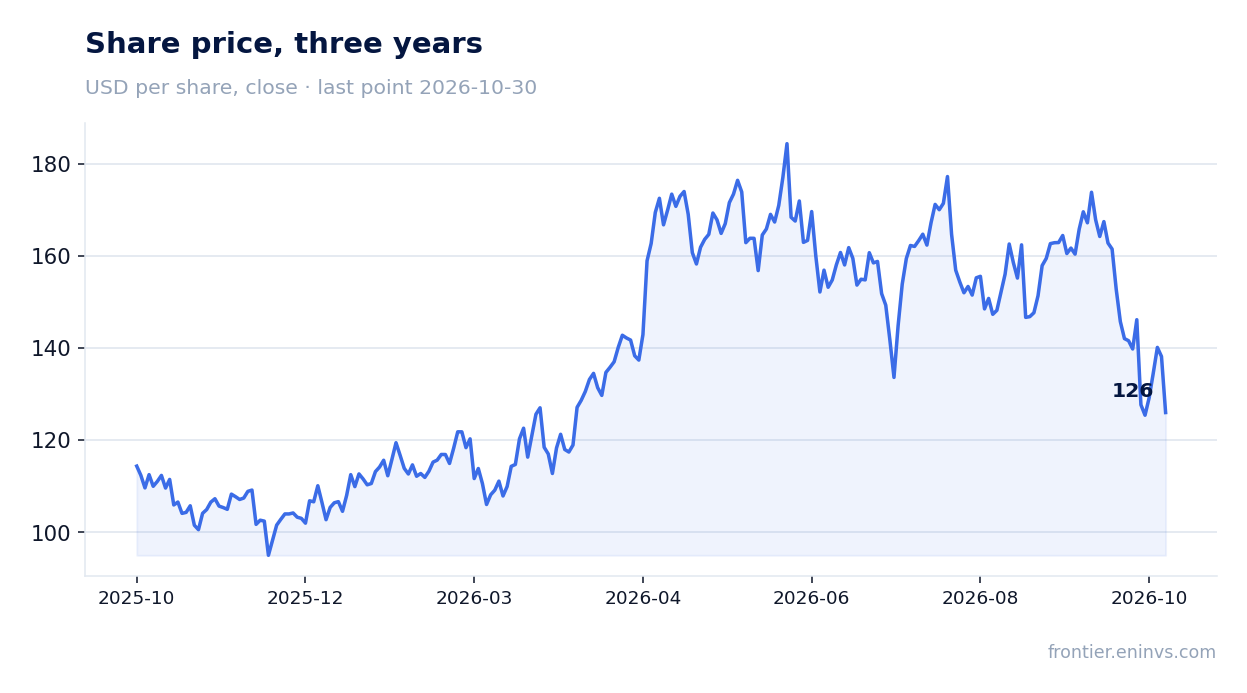
On 30 October nVent Electric plc reported results for the third quarter of 2026. Revenue reached USD 1,514.9 million, up 43.7% year on year, EBITDA came in at USD 336.5 million (+49.6%) and net profit at USD 202.4 million (+67.0%). The EBITDA margin rose to 22.2% from 21.3% a year earlier, while revenue growth decelerated from 52.8% in the second quarter. Despite the strong operating figures, the shares lost 8.8% on the release day and were still down 8.8% by 30 October. With an EV/EBITDA of 18.4 against its own three-year average of 20.9 and a portal-model upside of +32%, the share looks attractive, but the deceleration and the market reaction call for caution.
Key takeaways
— Revenue rose 43.7% year on year, but growth decelerated from 52.8% in the second quarter
— EBITDA grew 49.6%, outpacing revenue, and the margin rose to 22.2%
— Net profit increased 67.0%, with a net margin of 13.4%
— Free cash flow for the quarter reached USD 265.8 million on capex of USD 37.0 million
— Net debt fell from USD 1.4 billion on 30 June to USD 1.1 billion on 30 September
— The EV/EBITDA multiple of 18.4 is below its own three-year average of 20.9
— The dividend yield of 0.67% is modest, but the payout remains conservative
Attractiveness
Key figures, USD bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 1.05 | 1.51 | +43.7% |
| EBITDA | 0.23 | 0.34 | +49.6% |
| Operating profit | 0.17 | 0.28 | +69.8% |
| Net profit | 0.12 | 0.20 | +67.0% |
| Operating cash flow | 0.22 | 0.30 | +37.9% |
| Capex | 0.02 | 0.04 | +98.9% |
| EBITDA margin | 21.3% | 22.2% | +0.9 pp |
| Net margin | 11.5% | 13.4% | +1.9 pp |
Revenue rose 43.7% year on year, but growth decelerated from 52.8% in the second quarter
In the third quarter of 2026 nVent Electric plc reported revenue of USD 1,514.9 million, up 43.7% year on year. That is a strong result, but it is slower than the 52.8% growth seen in the second quarter. The deceleration was the first signal the market reacted to, sending the shares down 8.8% on the release day.
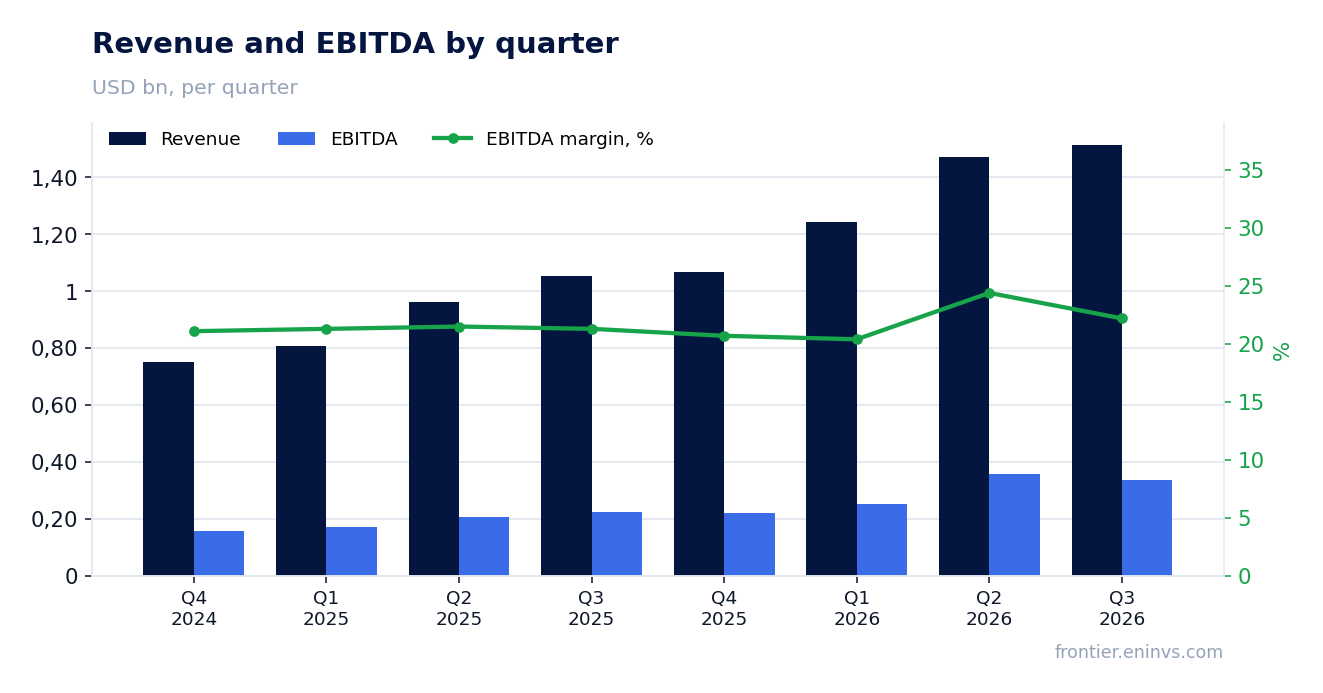
The growth appears to be driven by organic expansion and possibly acquisitions, but the facts provided do not break down the drivers. We can only state the overall trend: quarterly revenue has risen consistently from USD 1,242.0 million in the first quarter to USD 1,471.3 million in the second and USD 1,514.9 million in the third. This points to sustained demand, but the year-on-year growth rate is slowing.
For an investor, it matters that the deceleration is occurring from high absolute levels. Even at 43.7% growth, the company is posting one of the strongest rates in its history, and the question is whether it will hold in the next quarter.
EBITDA grew 49.6%, outpacing revenue, and the margin rose to 22.2%
EBITDA for the third quarter of 2026 came in at USD 336.5 million, up 49.6% year on year. This outpaced revenue growth, lifting the EBITDA margin to 22.2% from 21.3% a year earlier. The 0.9 percentage point improvement suggests the company managed to pass on some rising costs or benefited from operating leverage.
Operating profit reached USD 282.3 million, also confirming positive momentum. However, the facts do not provide a breakdown by cost line, so we cannot name the specific item that drove the margin gain. What matters is that profit growth is not accompanied by a deterioration in quality: the margin is expanding, not contracting.
Margin resilience is a key argument for the investment case. If the company keeps profitability above 22% in the next quarter, it will confirm its ability to generate profit even as revenue growth slows.
Net profit increased 67.0%, with a net margin of 13.4%
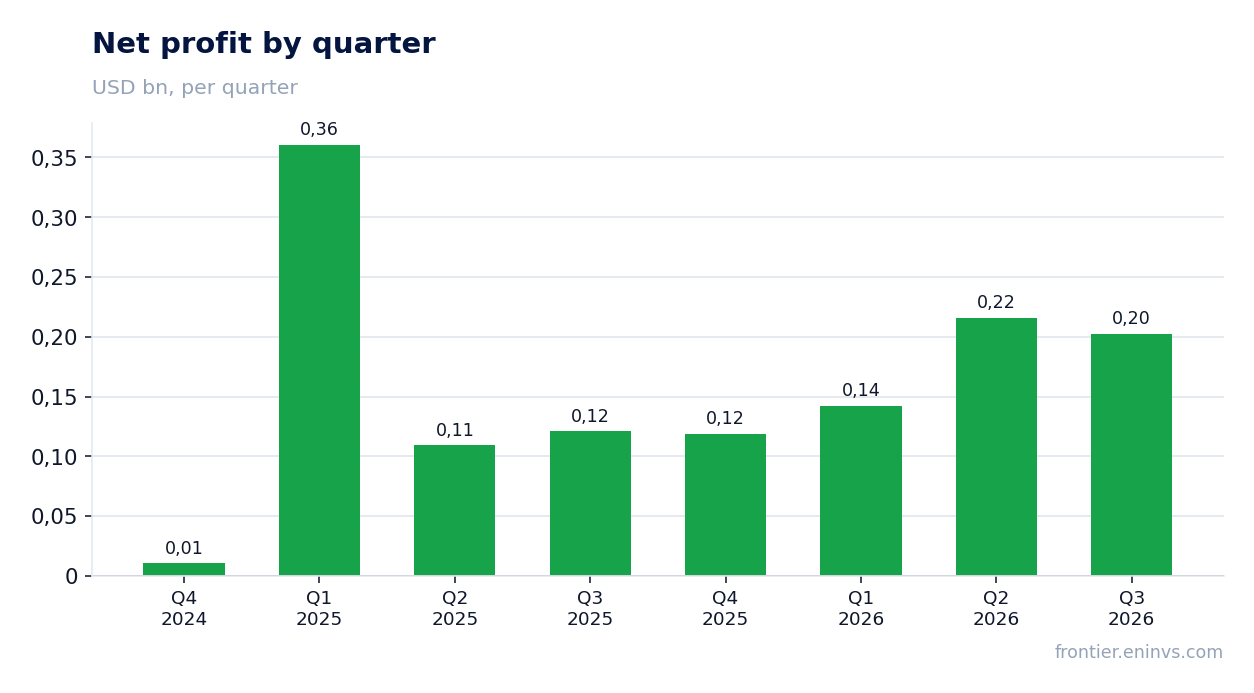
Net profit for the third quarter of 2026 reached USD 202.4 million, up 67.0% year on year. The net margin rose to 13.4% from 11.5% a year earlier. This faster growth relative to EBITDA (49.6%) points to lower pressure below the operating line – possibly from reduced interest expenses or tax effects, but the exact cause is not disclosed in the facts.
Net profit growing almost twice as fast as revenue is a strong signal, but it may be partly due to one-off factors. The data provided do not mention asset sales or other non-recurring items, so we cannot isolate their contribution. Nevertheless, the net profit level of USD 202.4 million looks organic for the current scale of the business.
For shareholders, what matters is not only absolute growth but the sustainability of the net margin. If it stays above 13% in the next quarter, it will reinforce confidence in earnings quality.
Free cash flow for the quarter reached USD 265.8 million on capex of USD 37.0 million
Operating cash flow for the third quarter of 2026 was USD 302.8 million, with capital expenditures of USD 37.0 million. That gives free cash flow of USD 265.8 million, which covers net profit (USD 202.4 million) with room to spare. The gap is explained by non-cash items, primarily depreciation, which is included in EBITDA but does not require a cash outflow.
Capex remains moderate at about 2.4% of revenue, which for an industrial company with growing revenue indicates low capital intensity. This allows a significant portion of cash flow to be directed toward debt reduction and dividends. During the quarter the company reduced net debt by USD 0.4 billion, from USD 1.4 billion on 30 June to USD 1.1 billion on 30 September.
Strong cash flow is an important argument for the resilience of the business. It also creates a buffer for further deleveraging, which is especially valuable amid market uncertainty.
Net debt fell from USD 1.4 billion on 30 June to USD 1.1 billion on 30 September
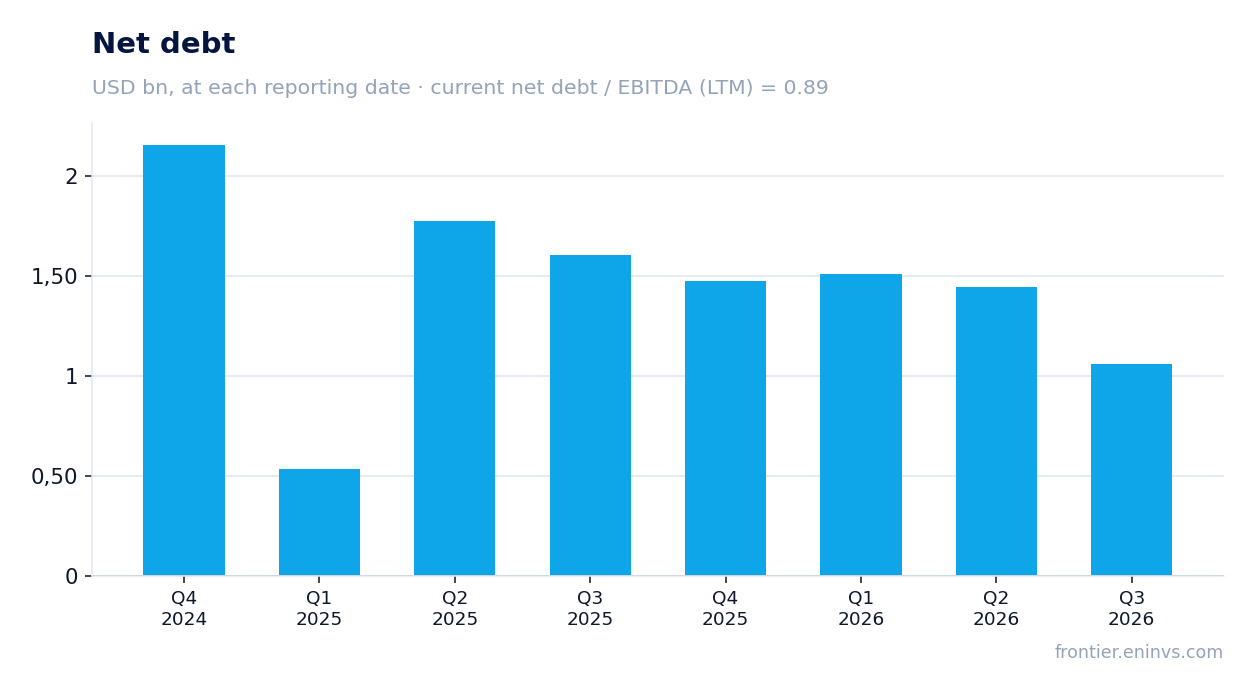
As of 30 September 2026, nVent Electric plc's net debt stood at USD 1.1 billion, down from USD 1.4 billion on 30 June. The USD 0.4 billion reduction came from strong operating cash flow, part of which was used to repay obligations. A year earlier, on 30 September 2025, net debt was USD 1.6 billion, so over 12 months it has fallen by USD 0.5 billion.
The net debt to EBITDA ratio for the trailing twelve months is 0.89, indicating low leverage. This level leaves the company room to manoeuvre – both for further acquisitions and for returning capital to shareholders. However, the facts do not provide an earlier value for this ratio, so we cannot say whether it has risen or fallen.
Low debt also reduces interest expenses, which partly explains the faster growth in net profit. In the next quarter the company may continue to reduce debt if it maintains its current cash flow.
The EV/EBITDA multiple of 18.4 is below its own three-year average of 20.9
The current EV/EBITDA multiple (trailing twelve months) is 18.4, which is 12% below its own three-year average of 20.9. This means the shares are trading cheaper than usual relative to their history. The lower multiple may reflect the deceleration in revenue growth that the market has begun to price in.
For comparison, the trailing P/E is 30.1 – a fairly high level, but it reflects strong profit growth. The EV/EBITDA ratio is more indicative for companies with debt, and its current value below the historical average creates room for a re-rating if the company proves the sustainability of growth.
On the portal's model, which estimates fair value through EBITDA growth and a target multiple, the upside for the shares is +32%. This is our own estimate, not a market consensus, and it points to the attractiveness of the stock at the current price.
The dividend yield of 0.67% is modest, but the payout remains conservative
nVent Electric plc's dividend yield over the trailing twelve months is 0.67%. This is a modest level, explained by the high share price and relatively small payout. The company is not a dividend story in the classic sense: its main value for shareholders is created through business and profit growth.
Nevertheless, the dividend is covered by profit with a large margin. With net profit of USD 679.5 million over the trailing twelve months and a market capitalisation of USD 20.5 billion, dividend payments amount to about USD 136 million, implying a payout ratio below 20%. This leaves the company free to reinvest and reduce debt.
Our estimate for the current year's dividend is based on a conservative payout and growing profit. However, the exact amount depends on the board's decision and may be adjusted. For an investor, the dividend here is a pleasant addition rather than the main source of income.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 20.5 bn USD |
| P/E (LTM) | 30.1 |
| EV/EBITDA (LTM) | 18.4 |
| P/B | 5.48 |
| Net debt / EBITDA (LTM) | 0.89 |
| Operating cash flow (LTM) | 0.77 bn |
| ROE | 20.0% |
| Dividend yield (12m) | 0.7% |
| EV/EBITDA, 3-year average | 20.9 |
Bottom line
nVent Electric plc delivered a strong quarter: revenue rose 43.7%, EBITDA 49.6% and net profit 67.0%, with the EBITDA margin reaching 22.2%. Free cash flow of USD 265.8 million allowed net debt to fall to USD 1.1 billion, and the EV/EBITDA multiple of 18.4 is below its own three-year average of 20.9. However, the deceleration in revenue growth relative to the second quarter and the 8.8% share-price drop on the release day indicate the market expected more. On the portal's model the upside is +32%, which outweighs concerns about the slowdown. The verdict is 'attractive': the stock trades below its historical valuation, generates strong cash flow and carries low leverage, but to confirm its growth status the company must sustain its pace and margin in the next quarter.
Open the company's financial profile NVT →
See also: market overview · valuation map · stock screeners