UZ_UNIVERSAL: profit fell 38.4% even as revenue rose 21.6% — margin returned to normal after an exceptional quarter
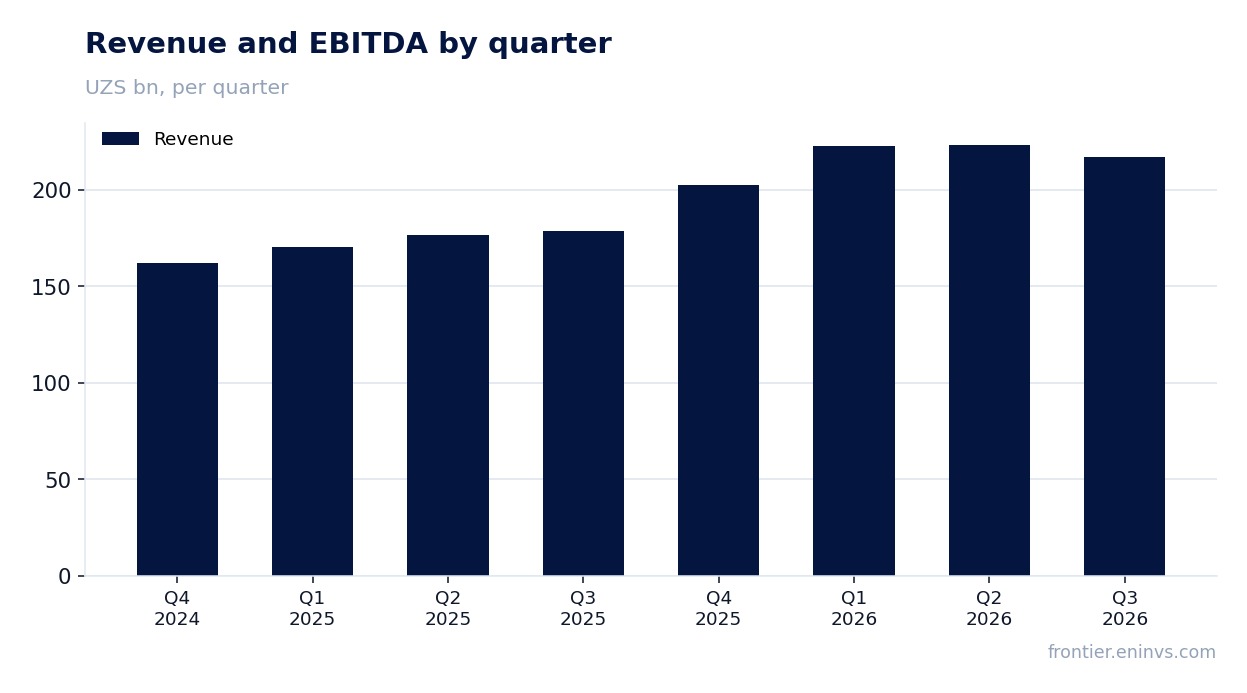
UZ_UNIVERSAL's third-quarter 2026 report showed revenue of 217.3 bn soums (+21.6% year on year) and net profit of 39.6 bn soums (–38.4% year on year). Net margin fell to 18.2% from 35.9% a year earlier, largely because the prior-year base was exceptionally high. At the current price the share looks rather attractive: P/E LTM 6.05, dividend yield 4.43%, and the portal's model implies 12% upside to fair value.
Key takeaways
— Revenue rose 21.6% year on year, but this is a deceleration from 26.6% a quarter earlier
— Net profit fell 38.4% due to a high prior-year base, not because the business deteriorated
— Net margin declined to 18.2% from 35.9%, returning to a more sustainable level
— Operating profit of 45.1 bn soums produced a 20.8% margin — above the fourth quarter of 2025
— A 4.43% dividend yield with a P/E of 6.05 makes the share interesting for income
— The portal's model implies 12% upside to fair value
Attractiveness
Key figures, UZS bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 179 | 217 | +21.6% |
| Operating profit | — | 45.1 | — |
| Net profit | 64.3 | 39.6 | -38.4% |
| Net margin | 35.9% | 18.2% | -17.7 pp |
Revenue rose 21.6% year on year, but this is a deceleration from 26.6% a quarter earlier
In the third quarter of 2026, revenue reached 217.3 bn soums, up 21.6% year on year. This continues the growth trend, but the pace has slowed: in the previous quarter growth was 26.6%. The deceleration may reflect a high base effect as well as possible demand saturation.
Compared with the fourth quarter of 2024 (162.2 bn soums), revenue is up 34%. However, quarterly dynamics are uneven: after a peak of 223.5 bn soums in the second quarter of 2026, revenue fell to 217.3 bn soums. This could be seasonal, but the report does not specify the reasons.
For the investor, the key point is that the company maintains double-digit growth, but the slowdown from 26.6% to 21.6% is a signal to watch in the next report. If the deceleration continues, it could limit profit growth going forward.
Net profit fell 38.4% due to a high prior-year base, not because the business deteriorated
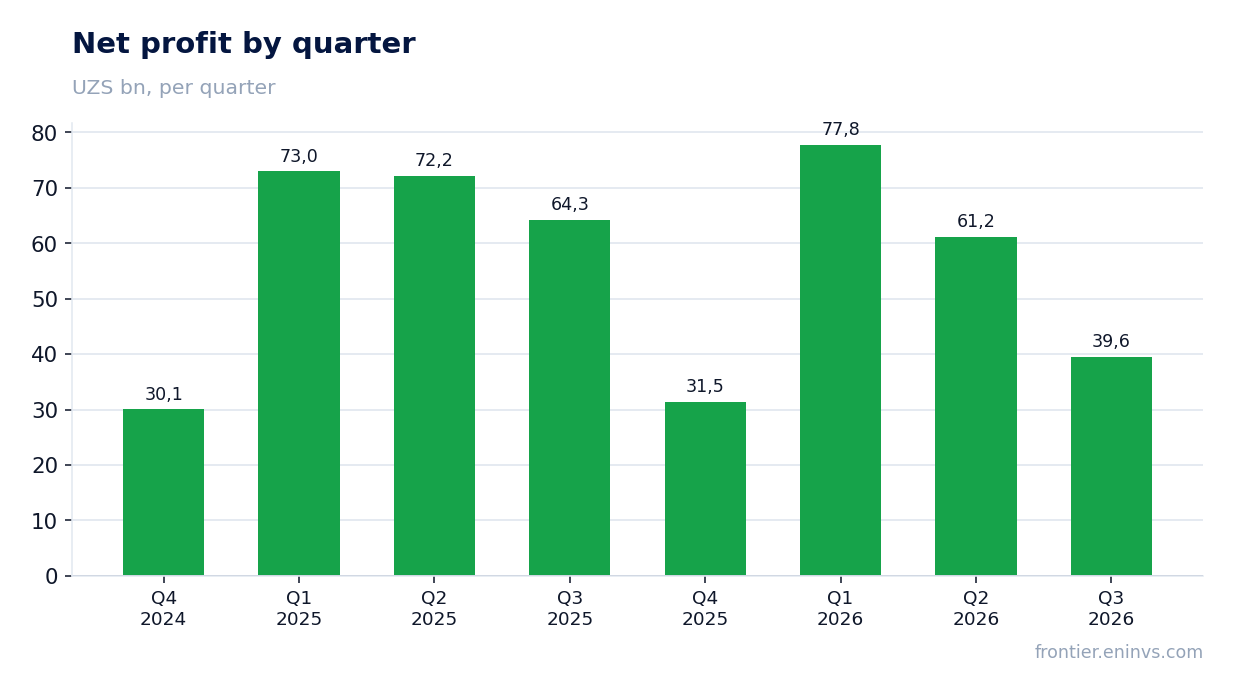
Net profit in the third quarter of 2026 was 39.6 bn soums, down 38.4% year on year. A year earlier, profit was 64.3 bn soums — an exceptionally high level. The decline is mainly due to the base effect, not a deterioration in operations.
Operating profit in the reporting quarter was 45.1 bn soums, higher than in the fourth quarter of 2025 (39.7 bn soums). This indicates the business remains profitable at the operating level. The gap between operating and net profit may be due to taxes or one-off items, but details are not disclosed in the report.
It is worth noting that in the first quarter of 2026 profit was 77.8 bn soums, and in the second quarter — 61.2 bn soums. The current 39.6 bn soums continues the decline from peak levels earlier in the year. This may indicate a normalization of profit after a period of high performance.
Net margin declined to 18.2% from 35.9%, returning to a more sustainable level
Net margin in the third quarter of 2026 was 18.2%, compared with 35.9% a year earlier. This decline reflects both revenue growth and profit fall. In absolute terms, profit decreased while revenue increased, leading to margin compression.
For comparison: in the fourth quarter of 2025, net profit was 31.5 bn soums on revenue of 202.4 bn soums, implying a margin of about 15.5%. Thus, the current 18.2% is higher than at the end of 2025 but significantly below the peak levels of early 2026, when margin exceeded 30%.
The margin decline may be due to rising costs or a change in revenue structure, but the report does not specify the factors. For the investor, it is important that profitability remains in double digits and the company can generate profit even at a lower margin.
Operating profit of 45.1 bn soums produced a 20.8% margin — above the fourth quarter of 2025
Operating profit in the third quarter of 2026 was 45.1 bn soums, corresponding to an operating margin of 20.8%. This is higher than in the fourth quarter of 2025, when operating profit was 39.7 bn soums on revenue of 202.4 bn soums (margin 19.6%).
The year-on-year increase in operating margin may be due to cost control or business mix improvement. However, the report does not provide a breakdown of expenses, so the exact reasons are not disclosed.
Operating profit is an important metric as it reflects the efficiency of core operations before financial and tax factors. The current level of 45.1 bn soums confirms that the company remains profitable at the operating level despite the decline in net profit.
A 4.43% dividend yield with a P/E of 6.05 makes the share interesting for income
The dividend yield over the last 12 months is 4.43%. This is a moderate level that may attract income-oriented investors. At the same time, the P/E LTM is 6.05, indicating a low valuation on earnings.
It is worth considering that dividend payments may be unstable, as the company's profit is subject to fluctuations. In the third quarter of 2026, net profit declined, which could affect future dividends if the trend continues.
Nevertheless, the current yield of 4.43% exceeds many risk-free rates, making the share attractive for conservative investors. However, the dividend decision depends on the company's financial policy and its profit.
The portal's model implies 12% upside to fair value
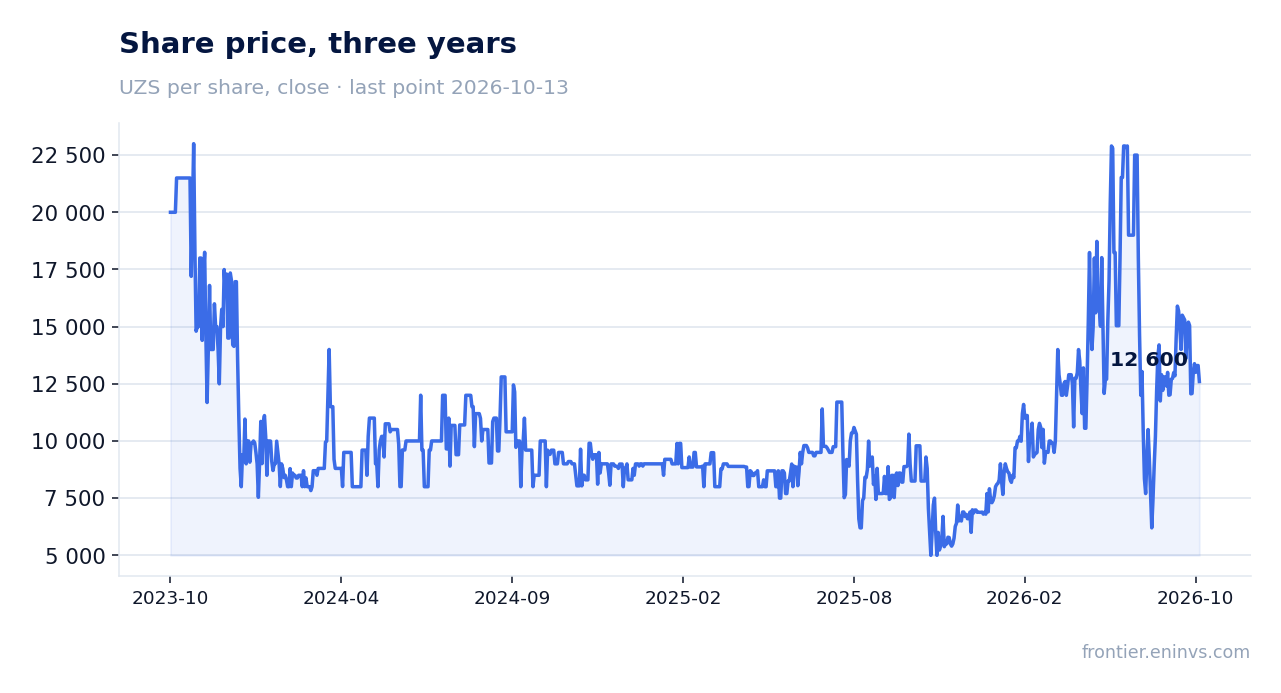
According to the portal's model, the upside to fair value is +12%. This is the portal's own estimate based on annualised earnings and market capitalisation, not a market consensus forecast.
The model takes into account current earnings and multiples, and its result suggests the share may be undervalued. However, this is just one estimate and does not guarantee future growth.
For the investor, it is important to weigh this estimate against risks: slowing revenue and declining profit could lead to a downward revision of fair value. Nevertheless, the current 12% upside looks moderately attractive.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 1 270 bn UZS |
| P/E (LTM) | 6.0 |
| P/B | 2.10 |
| ROE | 5.8% |
| Dividend yield (12m) | 4.4% |
Bottom line
UZ_UNIVERSAL's revenue rose 21.6% year on year, but the pace slowed compared with the previous quarter. Net profit fell 38.4% due to a high prior-year base, and margin declined to 18.2% — a return to a more sustainable level after an exceptional period. Operating profit of 45.1 bn soums remains solid, while a 4.43% dividend yield and a P/E of 6.05 make the share attractive for income-oriented investors. The portal's model implies 12% upside to fair value. The key question for a holder is whether the company can maintain profit at current levels and preserve dividends.
Open the company's financial profile UNIVERSAL →
See also: market overview · valuation map · stock screeners