UZ_UZEX: 9M 2026 profit up 34.5%, but it grows slower than revenue and needs almost no cash
UZ_UZEX's 9M 2026 report shows revenue of UZS 418,850.969 mn, operating profit of UZS 242,971.87 mn and net profit of UZS 341,732.031 mn. Revenue grew 24.0% year on year and net profit 34.5%, while the net margin rose from 75.2% to 81.6%. In the standalone first quarter of 2026, however, revenue growth decelerated to 11.8% from 17.5% a year earlier. At a P/E of 9.1 and a dividend yield of 15.8%, the share looks attractive, but the verdict rests on whether the margin above 80% holds.
Key takeaways
— 9M 2026 revenue grew 24.0%, but first-quarter growth decelerated to 11.8%
— Net profit rose 34.5% and outpaced revenue on a margin that climbed to 81.6%
— Operating profit of UZS 242,971.87 mn against net profit of UZS 341,732.031 mn means profit comes from more than operations
— A P/E of 9.1 with an ROE of 76.5% means the market pays less for profit than it earns on capital
— The 15.8% dividend yield rests on a payout covered by profit, not by cash flow
— Over the last twelve months profit of UZS 343,457.8 mn is almost equal to the 9M figure, so last year's fourth quarter was weak
Attractiveness
Key figures, UZS bn
| Metric | 9M 2025 | 9M 2026 | Change |
|---|---|---|---|
| Revenue | 338 | 419 | +24.0% |
| Operating profit | 169 | 243 | +43.9% |
| Net profit | 254 | 342 | +34.5% |
| Net margin | 75.2% | 81.6% | +6.4 pp |
9M 2026 revenue grew 24.0%, but first-quarter growth decelerated to 11.8%
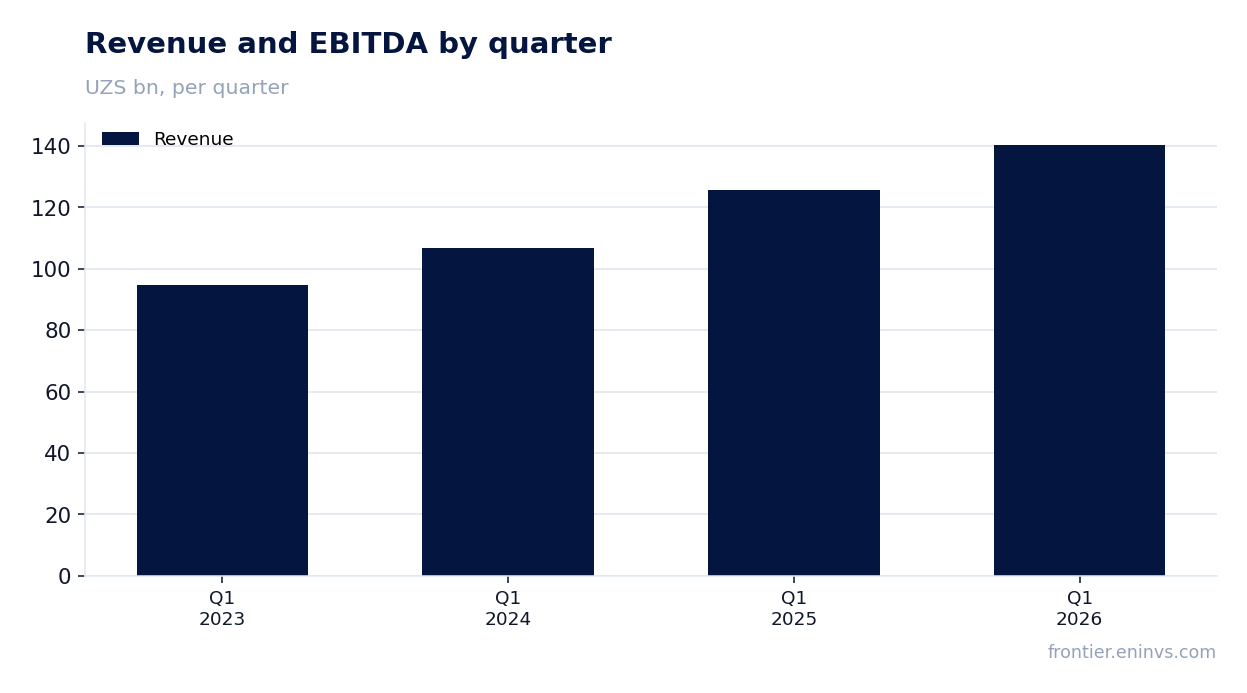
9M 2026 revenue was UZS 418,850.969 mn, 24.0% more than in the same period a year earlier. That pace is above the standalone first quarter, which means the second and third quarters added more than the first.
In the first quarter of 2026 revenue was UZS 140,383.773 mn, up 11.8% year on year. A year earlier, in the first quarter of 2025, growth was 17.5%, so the dynamics decelerated. Slower quarterly growth against a strong nine-month result is the main tension in the report.
For a holder this means the 24.0% annual pace cannot be carried into the next quarter mechanically. If quarterly growth stays near 11.8%, full-year revenue will grow more slowly than in the reported period.
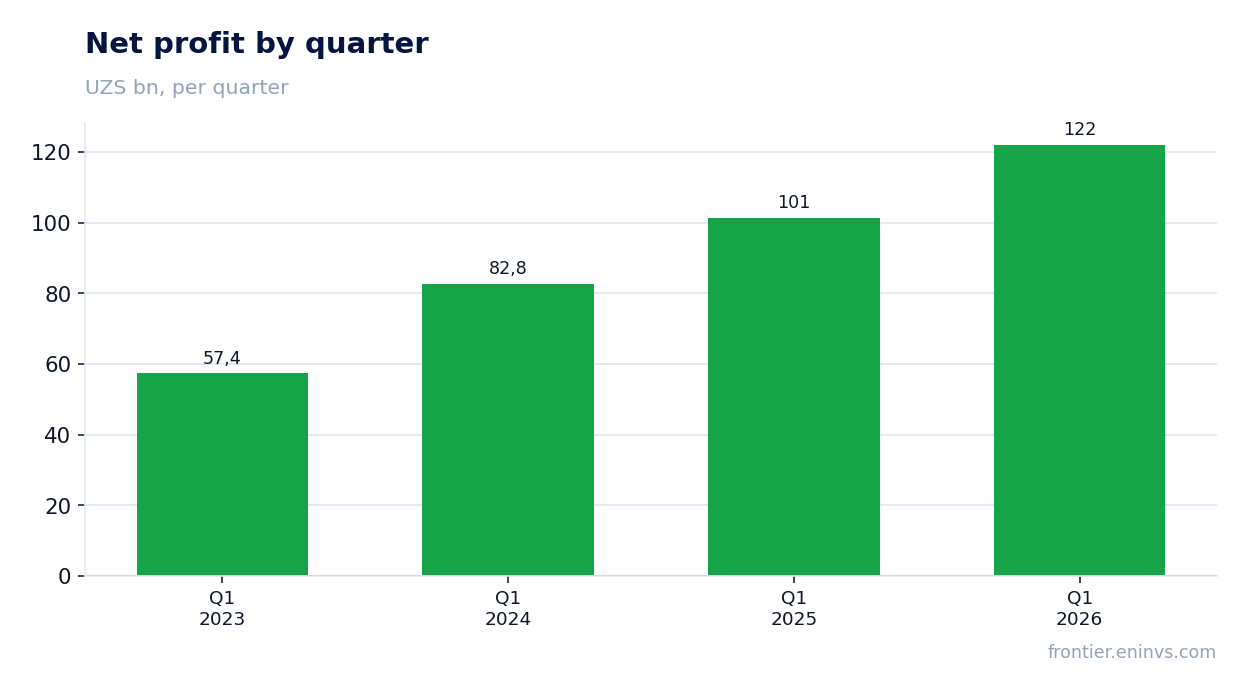
Net profit rose 34.5% and outpaced revenue on a margin that climbed to 81.6%
9M 2026 net profit was UZS 341,732.031 mn, 34.5% more year on year. The net margin rose from 75.2% to 81.6%, and that is why profit grew faster than revenue.
A margin above 80% means almost every sum of revenue reaches net profit. That structure is possible when most costs are not tied to revenue volume, so revenue growth falls almost entirely into profit.
The flip side is that an 81.6% margin leaves no cushion: any rise in costs not tied to revenue hits profit harder than at a more ordinary margin. The durability of this level, not revenue growth itself, determines next period's profit.
Operating profit of UZS 242,971.87 mn against net profit of UZS 341,732.031 mn means profit comes from more than operations
9M 2026 operating profit was UZS 242,971.87 mn and net profit UZS 341,732.031 mn. Net profit exceeds operating profit by almost UZS 99 bn, so a visible part of the result did not come from core operations.
The operating margin is 58.0% of revenue – high in itself, but well below the 81.6% net margin. The gap between them is the part of profit produced by lines below operating profit.
For judging the durability of profit this is the key point: the part below operating profit may not repeat next period. If it disappears, net profit moves toward operating profit and the growth picture becomes more modest.
A P/E of 9.1 with an ROE of 76.5% means the market pays less for profit than it earns on capital
A market cap of UZS 3,110,774.43 mn against trailing-twelve-month profit of UZS 343,457.8 mn gives a P/E of 9.1. At the same time ROE is 76.5% – capital turns into profit very quickly.
A P/E of 9.1 with an ROE of 76.5% means the market values profit at nine years' worth, while the company earns three quarters of its capital in a year. Such a gap usually says the market does not treat the profit as durable.
Comparing the P/E with its own three-year history is impossible from the facts – they contain neither an average nor past multiples. The conclusion therefore rests on the absolute level: 9.1 is a low multiple for a company with such a return on capital.
The 15.8% dividend yield rests on a payout covered by profit, not by cash flow
The trailing-twelve-month dividend yield is 15.8% on the current price. That is a very high level: more than one and a half times the key rate if it is around 10%, and it alone explains interest in the share.
The payout rests on profit: trailing-twelve-month net profit is UZS 343,457.8 mn, and a dividend of this size is covered by it. But cash flow is not disclosed in the facts, so whether there is cash rather than accounting profit behind the payment cannot be judged.
The risk to the dividend is the same margin: if part of the profit below the operating line does not repeat, the payout base shrinks. A smaller payout would come from falling net profit, not from rising debt, which the facts do not show.
Over the last twelve months profit of UZS 343,457.8 mn is almost equal to the 9M figure, so last year's fourth quarter was weak
Trailing-twelve-month profit is UZS 343,457.8 mn and revenue UZS 444,500.0 mn. 9M 2026 profit is UZS 341,732.031 mn, so almost the whole annual profit came in those nine months.
The difference between the two bases – about UZS 1.7 bn of profit and about UZS 25.6 bn of revenue – falls in the fourth quarter of 2025. That means last year's final quarter delivered very little in both revenue and profit.
For a holder this is a double signal. On one hand, the annual base for the dividend and the multiple rests on nine strong months. On the other, quarterly profit is unstable, and a weak quarter can repeat.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 3 111 bn UZS |
| P/E (LTM) | 9.1 |
| P/B | 5.02 |
| ROE | 76.5% |
| Dividend yield (12m) | 15.8% |
Bottom line
The report's strength is 34.5% profit growth at an 81.6% margin and a 76.5% ROE: the company earns on capital very quickly. The weak spot is where part of the profit comes from: net profit exceeds operating profit by almost UZS 99 bn, and that part may not repeat. Quarterly revenue growth has decelerated to 11.8%, and trailing-twelve-month profit is almost equal to the 9M figure, so last year's fourth quarter was weak. At a P/E of 9.1 and a 15.8% dividend yield the share looks attractive, but the verdict rests on the durability of the margin and on whether profit below the operating line repeats.
Open the company's financial profile UZEX →
See also: market overview · valuation map · stock screeners