Abu Dhabi Islamic Bank: profit barely grew as net interest income growth slowed to 2.1%
Abu Dhabi Islamic Bank reported third-quarter 2026 results. Net profit came in at AED 1,728.8 million, up just 0.2% year on year, while net interest income growth slowed to 2.1% year on year from 9.9% in the prior quarter. Over the trailing twelve months the bank earned AED 6,913.1 million on net interest income of AED 12,300.0 million, with the shares trading at a P/E of 11.5 and an ROE of 7.0%. The portal model puts upside to fair value at +8%, which, given the slowdown, leaves the stock rather attractive but with little margin for error.
Key takeaways
— Net interest income grew just 2.1% year on year – the weakest pace in six quarters
— Net profit added only 0.2%, with all the growth eaten by the slowdown in core income
— Over the trailing twelve months the bank earned AED 6,913.1 million on net interest income of AED 12,300.0 million
— A P/E of 11.5 and ROE of 7.0% – a valuation richer than the current profit trajectory justifies
— The portal model implies only +8% upside to fair value – a thin cushion amid the slowdown
Attractiveness
Key figures, AED bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Net profit | 1.72 | 1.73 | +0.2% |
| Capex | 0.13 | -0.10 | -179.1% |
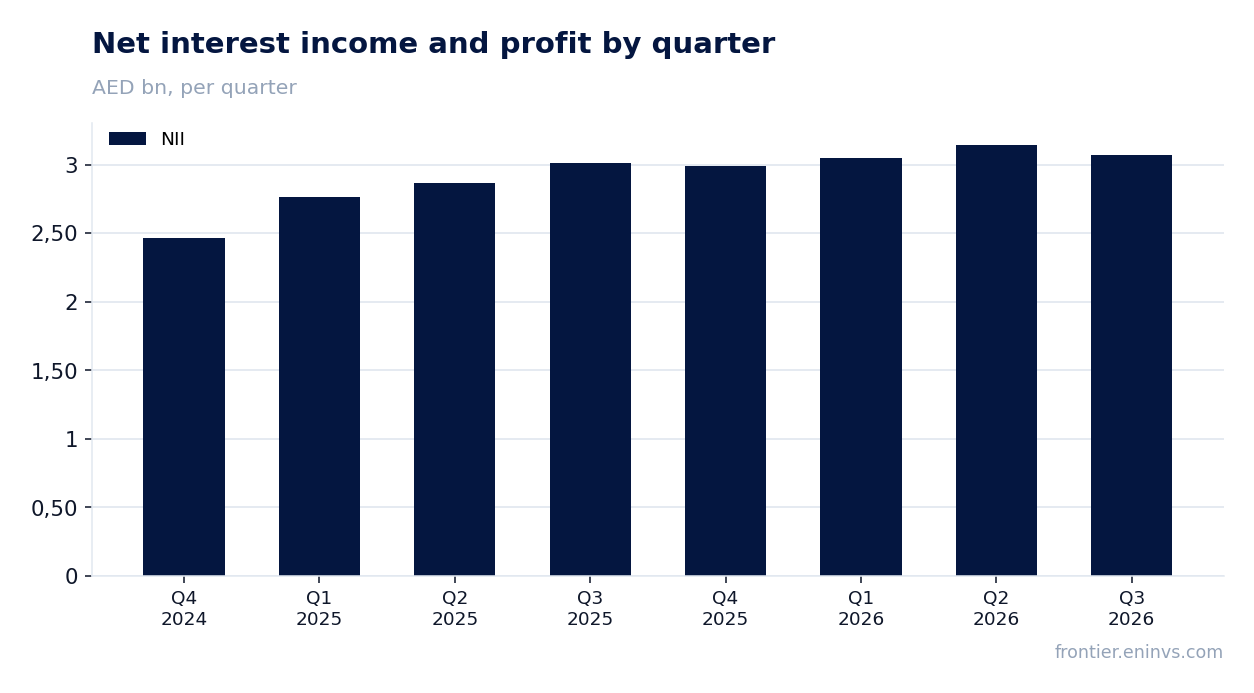
Net interest income grew just 2.1% year on year – the weakest pace in six quarters
In the third quarter of 2026 net interest income came to AED 3,073.2 million, up 2.1% on the third quarter of 2025. That is well below the 9.9% growth in the second quarter of 2026 and the 15.8% in the third quarter of 2025. The slowdown began in the first quarter of 2026, when growth was 10.1%, and continued into the second at 9.9%.
The quarterly sequence confirms the turn: after AED 3,145.2 million in the second quarter of 2026, income fell to AED 3,073.2 million in the third. That is the first quarter-on-quarter decline in net interest income since the fourth quarter of 2025, when the figure was AED 2,989.0 million. The report does not disclose the cause of the slowdown, but the change of trend matters: the bank is no longer growing its core income at the pace that drove profit in previous quarters.
Net profit added only 0.2%, with all the growth eaten by the slowdown in core income
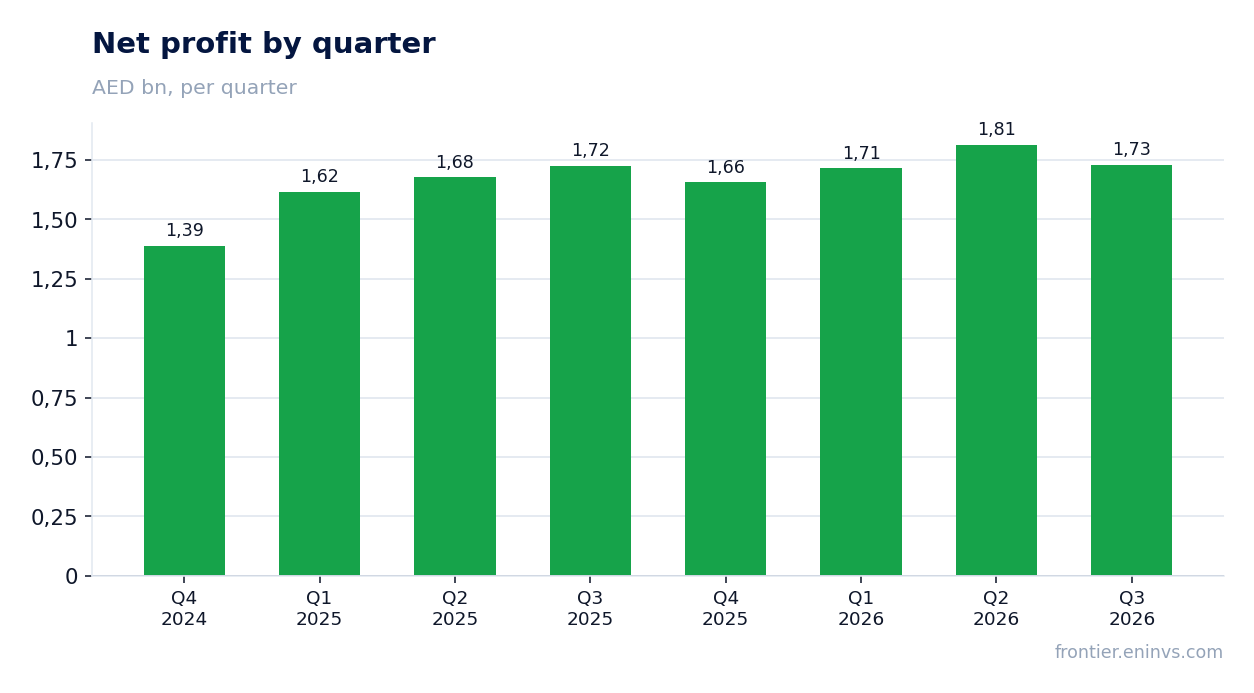
Net profit for the third quarter of 2026 was AED 1,728.8 million against AED 1,724.5 million a year earlier – growth of 0.2%. That is the smallest increase in six quarters: profit rose to AED 1,713.7 million in the first quarter of 2026 and to AED 1,813.7 million in the second, before slipping to AED 1,728.8 million in the third. The quarter-on-quarter decline from the second quarter reflects the fall in net interest income while other costs held.
Over the trailing twelve months the bank earned AED 6,913.1 million of net profit on net interest income of AED 12,300.0 million. Profit is therefore barely growing: the 0.2% year-on-year increase in the third quarter does not offset the slowdown of previous quarters. The path from here depends on whether the bank can revive net interest income growth or replace it from other sources.
Over the trailing twelve months the bank earned AED 6,913.1 million on net interest income of AED 12,300.0 million
The trailing twelve months give a fuller picture than a single quarter: profit of AED 6,913.1 million on net interest income of AED 12,300.0 million. The ratio of profit to net interest income is about 56%, reflecting a high dependence of the result on core banking income. Any slowdown in net interest income feeds almost one-for-one into profit.
That is exactly what happened in the third quarter: net interest income growth slowed to 2.1% and profit rose only 0.2%. Over the trailing twelve months quarterly profit ranged from AED 1,656.8 million in the fourth quarter of 2025 to AED 1,813.7 million in the second quarter of 2026. There is no visible sustained growth outside net interest income.
A P/E of 11.5 and ROE of 7.0% – a valuation richer than the current profit trajectory justifies
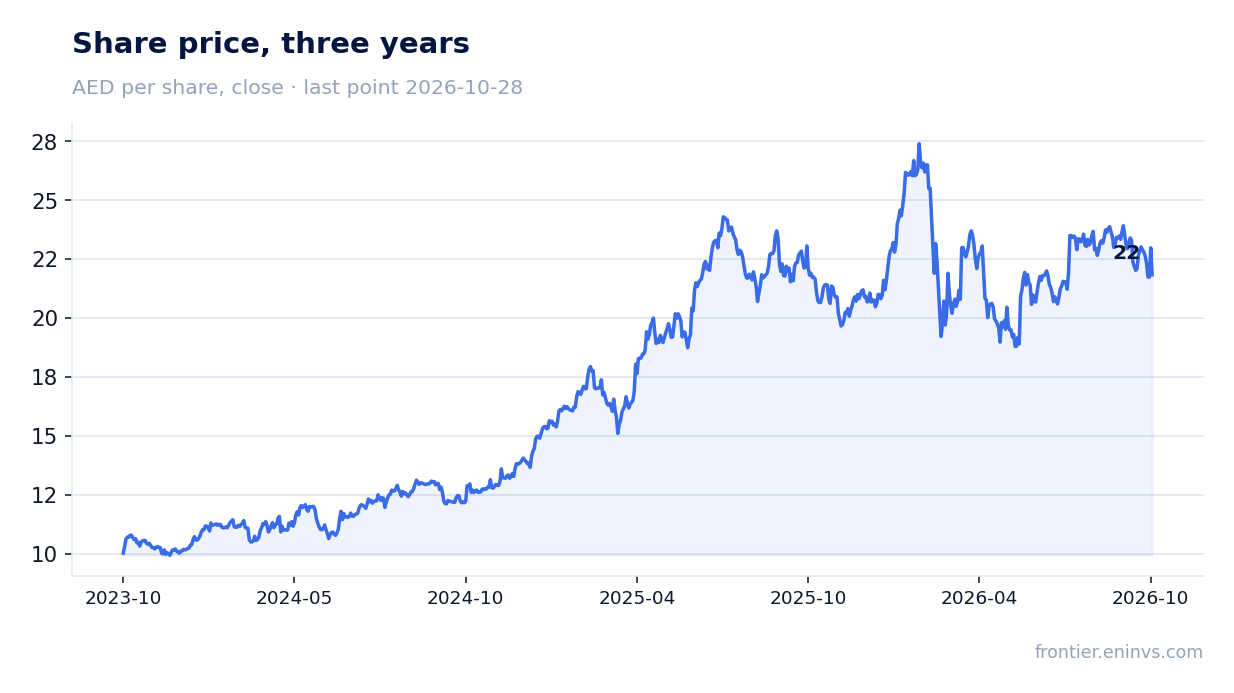
Abu Dhabi Islamic Bank shares trade at a P/E of 11.5 on trailing-twelve-month earnings, with a market capitalisation of AED 79,322.9 million. Return on equity is 7.0%, which at the current valuation leaves little room for value creation: the market is paying for profit that is barely growing. The price-to-book ratio at such an ROE looks high, although the facts do not give a direct P/B figure.
A comparison of the current multiple with its own three-year history is not possible – the facts do not include that average. But the profit trajectory speaks for itself: with net profit up 0.2% year on year and net interest income growth slowing to 2.1%, the current valuation does not look conservative. To justify a P/E of 11.5 the bank needs to revive profit growth, not merely hold it at last year's level.
The portal model implies only +8% upside to fair value – a thin cushion amid the slowdown
The portal model, which compares annualised earnings with market capitalisation, puts upside to fair value at +8%. This is our own estimate, not a market consensus or a target price. With the current profit trajectory that cushion looks thin: it does not cover the risk of a further slowdown in net interest income.
If net interest income growth stays at 2.1% or below, profit will continue to stagnate and the model will be revised downwards. To lift the valuation the bank needs to accelerate core income – then the +8% upside could increase. For now the gap between price and fair value is too small to offset the uncertainty.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 79.3 bn AED |
| P/E (LTM) | 11.5 |
| P/B | 2.45 |
| ROE | 7.0% |
Bottom line
The report's strength is the bank's ability to hold profit at last year's level – AED 1,728.8 million, up 0.2%. But all the growth comes from the inertia of previous quarters, not from new momentum: net interest income grew just 2.1%, the weakest pace in six quarters. A valuation of 11.5 times earnings at an ROE of 7.0% and portal-model upside of +8% leaves no cushion against further slowdown. The question for a holder now is whether the bank can restore core income growth – without it profit will stall and the multiple will look high.
Open the company's financial profile ADIB →
See also: market overview · valuation map · stock screeners