Emaar Properties: revenue barely grew, but profit rests on low debt and a cheap multiple
In its Q3 2026 report, Emaar Properties posted revenue of AED 13,632.5 mn and operating profit of AED 5,440.3 mn. Year on year revenue added only 2.7%, noticeably slower than the 18.2% seen in Q2. Over the trailing twelve months the company earned AED 19,189.3 mn of net profit, trades at EV/EBITDA of 4.3 against its own three-year average of 5.6, and pays a dividend yield of about 8.0%. On balance the share looks rather attractive than not.
Key takeaways
— Q3 revenue grew just 2.7%, a deceleration from 18.2% in Q2
— Operating profit of AED 5,440.3 mn on revenue of AED 13,632.5 mn implies a margin of about 40%
— Over the trailing twelve months the company earned AED 19,189.3 mn of net profit on AED 54,000.0 mn of revenue
— Net debt at end-2025 stood at AED 52.1 mn – a level, not a trend
— EV/EBITDA of 4.3 is 23% below its own three-year average of 5.6 – the share is cheaper than its history
— A dividend yield of 8.0% is well above what the risk-free rate offers
— On the portal's model the fair value of the share is 10% above the current price
Attractiveness
Key figures, AED bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 13.3 | 13.6 | +2.7% |
| EBITDA | 6.21 | — | — |
| Operating profit | 5.80 | 5.44 | -6.2% |
| Net profit | 4.37 | — | — |
| Operating cash flow | 5.12 | — | — |
| Capex | 0.36 | — | — |
| EBITDA margin | 46.8% | — | — |
| Net margin | 32.9% | — | — |
Q3 revenue grew just 2.7%, a deceleration from 18.2% in Q2
Q3 2026 revenue came in at AED 13,632.5 mn, up 2.7% year on year. In Q2 the growth rate was 18.2%, so the pace slowed more than sixfold. This is the weakest quarterly revenue increase across the five quarters for which data is available.
The slowdown is visible in absolute terms too: quarter on quarter revenue rose from AED 11,509.5 mn to AED 13,632.5 mn, but the year-on-year gain is small. For a company that showed 40.5% growth at the end of 2025, this is a marked change of picture. The reasons for the slowdown are not disclosed in the supplied facts, so we limit ourselves to stating it: growth has nearly stalled.
For a holder this is the main signal of the report. Revenue is the base for profit and dividends, and if its growth fades, future payouts may come under question. In the next report it is worth watching whether revenue returns to double-digit growth or whether 2.7% is the new normal.
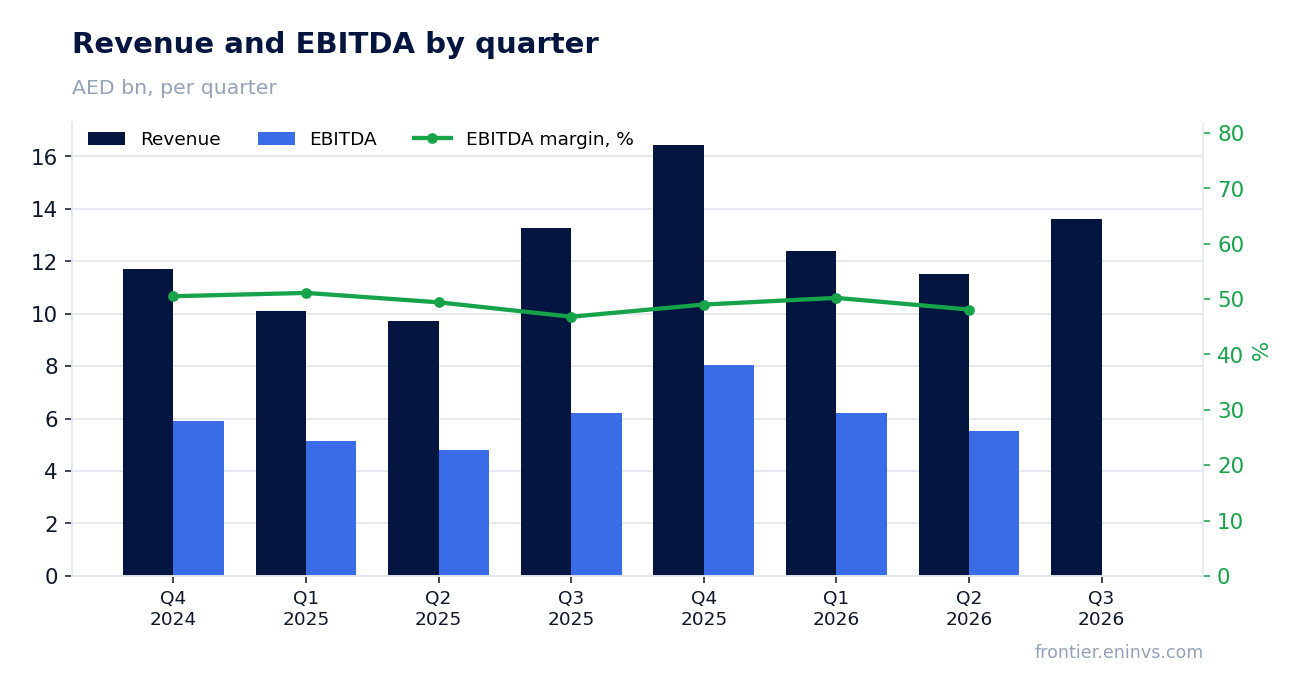
Operating profit of AED 5,440.3 mn on revenue of AED 13,632.5 mn implies a margin of about 40%
Operating profit for Q3 2026 was AED 5,440.3 mn. On revenue of AED 13,632.5 mn that implies a margin of about 40%. For a developer this is a high level, and it holds even with weak revenue growth.
The year-on-year comparison shows that absolute operating profit declined: in Q3 2025 it was AED 5,799.4 mn. So with revenue barely growing, operating profit actually shrank slightly. This means costs are rising faster than revenue, although the specific cost lines are not disclosed in the facts.
A margin of about 40% is what keeps the company among the profitable ones. But if revenue continues to stagnate while costs rise, the margin will start to compress. For now operating profit remains solid and provides the base for net profit and dividends.
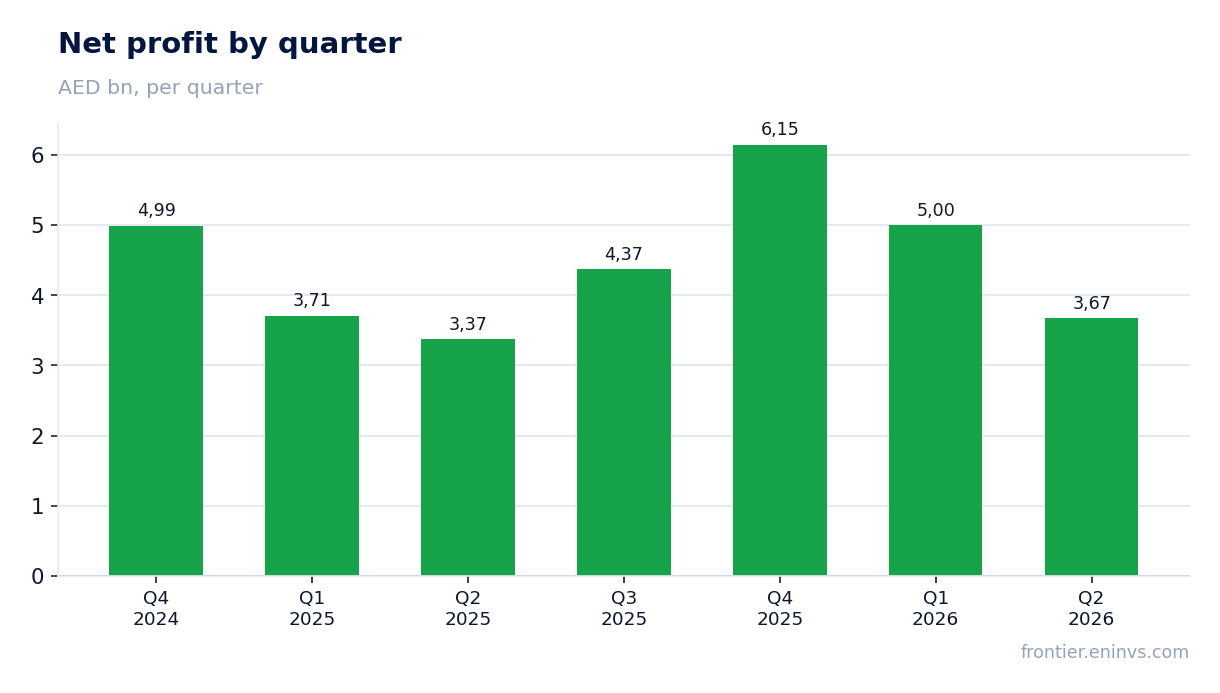
Over the trailing twelve months the company earned AED 19,189.3 mn of net profit on AED 54,000.0 mn of revenue
Over the trailing twelve months ended 30 September 2026, Emaar Properties earned AED 19,189.3 mn of net profit on revenue of AED 54,000.0 mn. The net margin is about 35.5% – a high figure that speaks to strong pricing power and cost control.
EBITDA for the same period was AED 25,534.5 mn. The gap between EBITDA and net profit – about AED 6.3 bn – covers depreciation, interest and taxes. That is a moderate burden that does not consume the bulk of the operating result.
Trailing twelve-month profit is the base for dividends. With a market capitalisation of AED 109,246.7 mn, the price-to-earnings ratio (P/E) is 5.7. That is a low multiple, reflecting either the market's doubt about the sustainability of profit or a general undervaluation of the company.
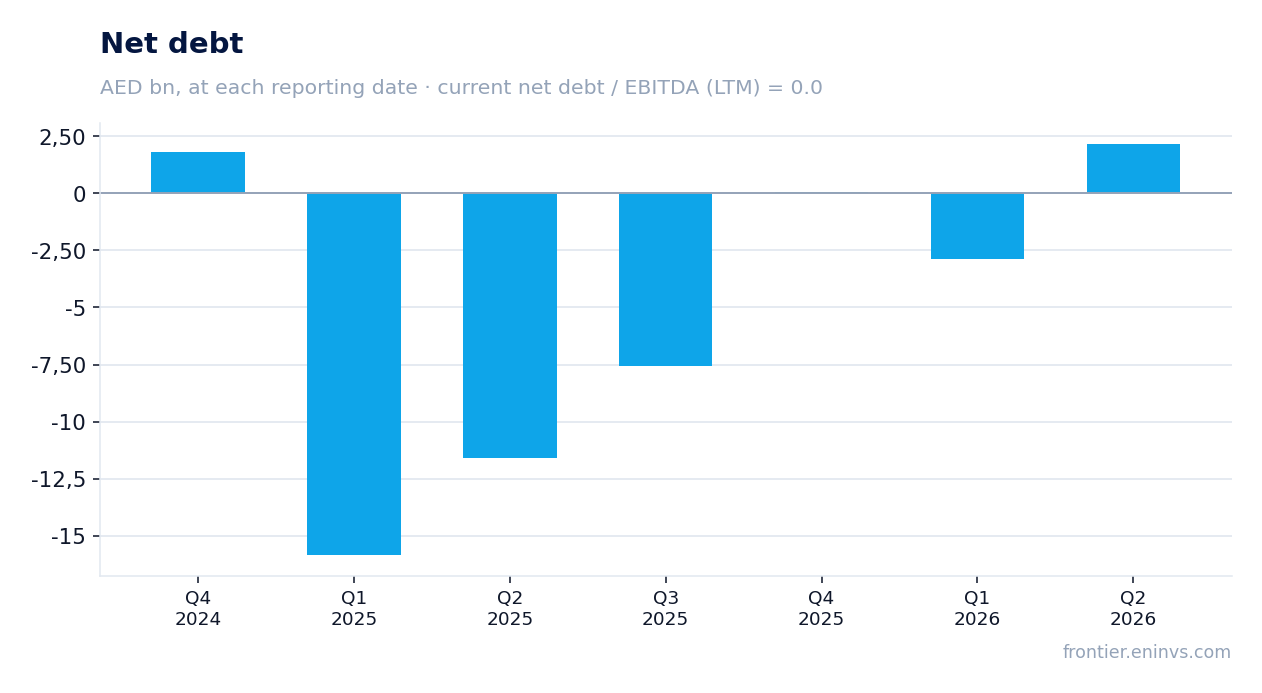
Net debt at end-2025 stood at AED 52.1 mn – a level, not a trend
At the end of 2025 Emaar Properties' net debt stood at AED 52.1 mn. That is a near-zero level for a company with a market capitalisation of AED 109.2 bn and annual EBITDA of AED 25.5 bn. The net debt to EBITDA ratio over the trailing twelve months is 0.0 – leverage is effectively absent.
The facts do not include an earlier net debt figure, so we cannot say whether it rose or fell. But the level itself shows the company does not depend on borrowed money and can direct almost all profit to dividends or development.
Low debt is a safety cushion. If revenue continues to slow, the company will have no trouble servicing its obligations. This is one reason the share can remain attractive even with weak operating growth.
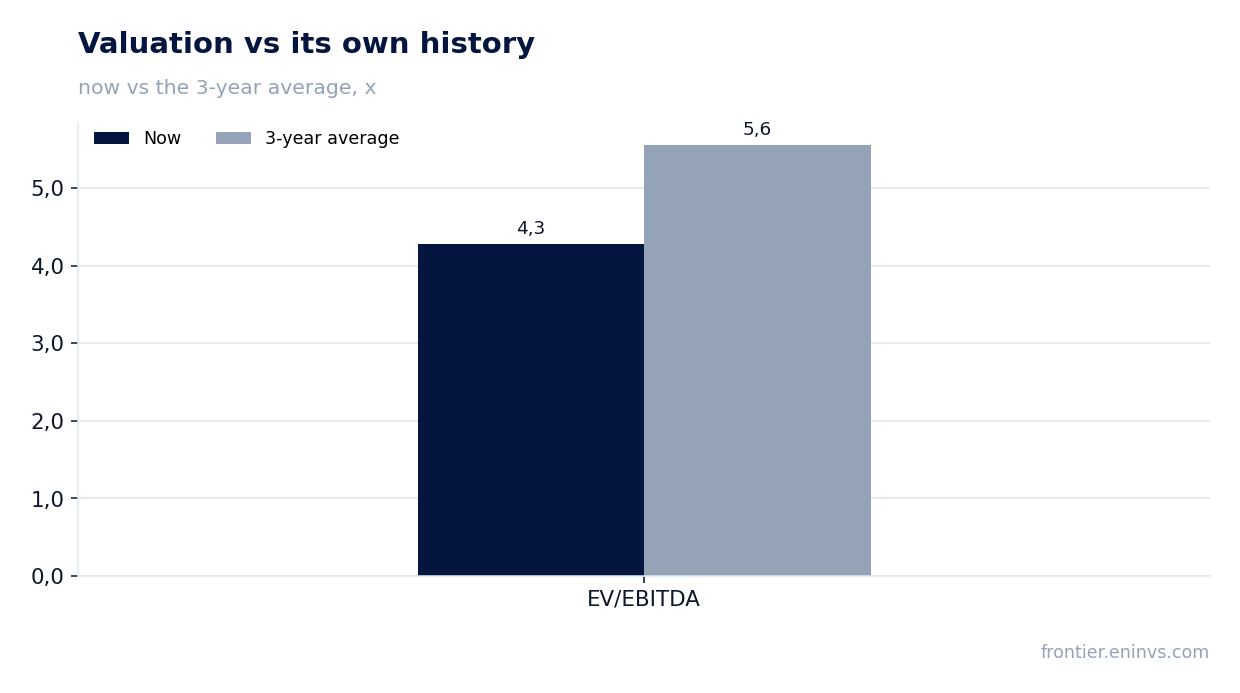
EV/EBITDA of 4.3 is 23% below its own three-year average of 5.6 – the share is cheaper than its history
On the EV/EBITDA multiple the company trades at 4.3. That is 23% below its own three-year average of 5.6. In other words, the market values current EBITDA more cheaply than it did on average over the past three years.
This valuation may be explained by the revenue slowdown: investors are pricing in the risk that profit will not grow. But if profit can be held at least at the current level, the multiple will be forced back to its historical average, which offers upside for the share price.
On the portal's model the fair value of the share is 10% above the current price. This is our own estimate, based on EBITDA growth and a target multiple, not a market consensus. It confirms that the share looks undervalued relative to its historical levels.
A dividend yield of 8.0% is well above what the risk-free rate offers
The trailing twelve-month dividend yield is 8.0%. That is a high level, well above the yield on risk-free instruments. For an income-oriented investor such a payout looks attractive.
The dividend is covered by profit: over the trailing twelve months net profit was AED 19,189.3 mn against a market capitalisation of AED 109,246.7 mn. With a payout ratio of about 45%, the dividend is covered more than twice by profit. This provides a margin of safety even if profit declines.
However, the sustainability of the dividend depends on future profit. If revenue continues to slow and costs rise, profit may fall and the company may be forced to cut payouts. For now the 8.0% yield is one of the main arguments in favour of the share.
On the portal's model the fair value of the share is 10% above the current price
Our valuation model, based on EBITDA growth and a target multiple, shows that the fair value of the share is 10% above the current market price. This is the portal's own estimate, not a market consensus or a target price.
The 10% upside is moderate, but it is supported by a low EV/EBITDA multiple (4.3 against a historical average of 5.6) and a high dividend yield (8.0%). Together this gives the investor a combination of current income and price upside.
The main risk to the model is a further slowdown in revenue. If profit starts to fall, the target multiple may prove unattainable and fair value will decline. But at current levels the share looks rather undervalued.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 109 bn AED |
| P/E (LTM) | 5.7 |
| EV/EBITDA (LTM) | 4.3 |
| P/B | 1.01 |
| Net debt / EBITDA (LTM) | 0.00 |
| ROE | 13.8% |
| Dividend yield (12m) | 8.0% |
| EV/EBITDA, 3-year average | 5.6 |
Tracked metrics of the idea
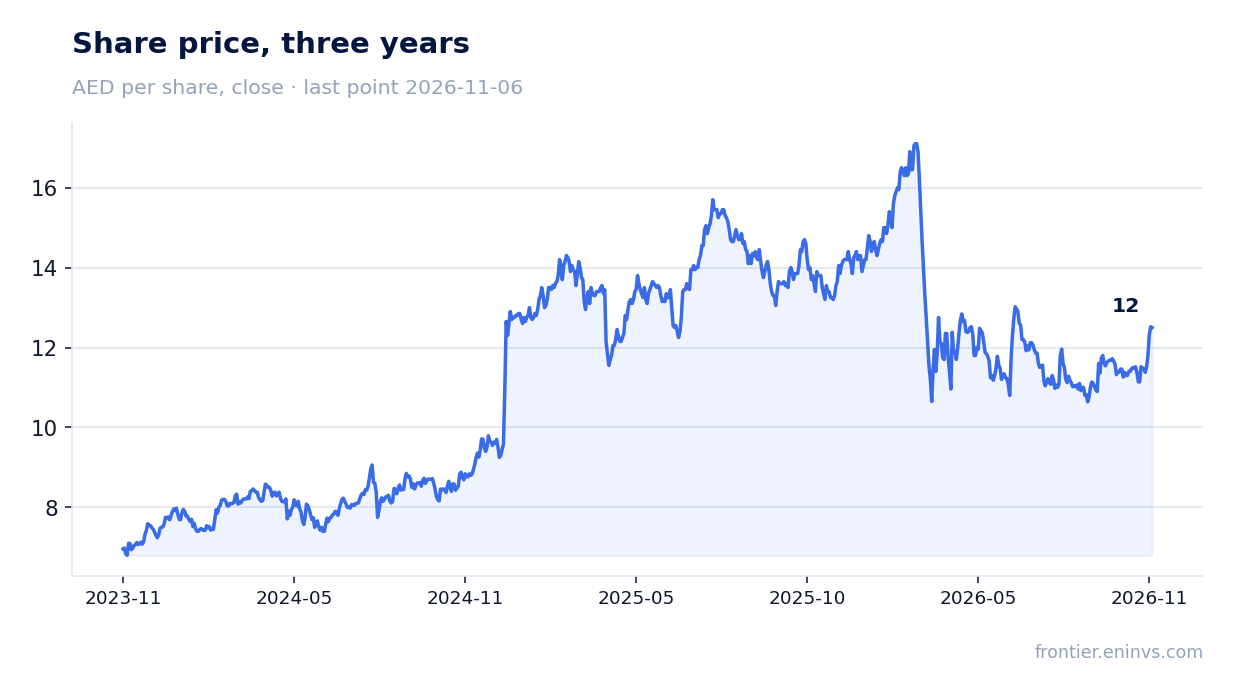
The metrics we track our idea "Emaar Properties" of 2026-07-20 by - at the idea date and now. The share price moved +12% over the period. Original write-up: https://frontier.eninvs.com/region/ae/article/emaar
Idea: at publication and now
| Metric | 2026-07-20, price 11.04 | Now, price 12.36 |
|---|---|---|
| Fundamental value created, share of market cap | +17% | +10% |
Bottom line
The strong side of the report is near-zero net debt (AED 52.1 mn) and high profitability: an operating margin of about 40% and trailing twelve-month net profit of AED 19,189.3 mn. The weak side is the sharp slowdown in revenue to 2.7% year on year and the decline in operating profit. The share trades at EV/EBITDA of 4.3 against its own three-year average of 5.6, a 23% discount to history, while the 8.0% dividend yield provides current income. On the portal's model the price upside is 10%. With these factors in mind the share looks rather attractive, but the key question is whether the company can resume revenue growth.
Open the company's financial profile EMAAR →
See also: market overview · valuation map · stock screeners