Embraer: profit nearly tripled, but a one-off $68m tax credit made most of the margin gain
On August 13, Embraer reported results for the second quarter of 2026. On the card's figures (the BRL filing to CVM translated into dollars) revenue rose 21.2% year-on-year to $2,232.2 million, EBITDA – by 45.1% to $352.6 million, and net profit tripled to $214.8 million; the company's own dollar release shows revenue of $2,235 million, +23%. Profitability rose markedly: EBITDA margin reached 15.8% versus 13.2% a year earlier, but about 3 pp of the margin came from a one-off $68m tax credit: without it and US import tariffs, Embraer's adjusted EBIT margin was 10.6% versus 10.5% a year earlier. With an EV/EBITDA multiple of 15.8 and the portal model implying 29% upside, the stock looks attractive.
Key takeaways
— Revenue grew 21.2% year-on-year, but this is a deceleration from 32.6% a quarter earlier
— EBITDA rose 45.1% and margin rose to 15.8% from 13.2%, but about 3 pp of that is a one-off tax credit
— Net profit tripled to $214.8 million, with margin reaching 9.6%
— Operating cash flow was $445.3 million with capital expenditures of $111.8 million
— Net debt fell to $0.3 billion as of June 30, 2026, from $0.9 billion a year earlier
— Net debt/EBITDA LTM stands at 0.36, indicating low leverage
— Trailing 12-month dividend yield is 1.26%; R$0.28 per share of interest on equity was declared for the second quarter
Attractiveness
Key figures, USD bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 1.84 | 2.23 | +21.2% |
| EBITDA | 0.24 | 0.35 | +45.1% |
| Operating profit | 0.18 | 0.29 | +57.4% |
| Net profit | 0.07 | 0.21 | +201.3% |
| Operating cash flow | -0.09 | 0.45 | to positive |
| Capex | 0.11 | 0.11 | -2.0% |
| EBITDA margin | 13.2% | 15.8% | +2.6 pp |
| Net margin | 3.9% | 9.6% | +5.7 pp |
Revenue grew 21.2% year-on-year, but this is a deceleration from 32.6% a quarter earlier
In the second quarter of 2026, Embraer's revenue on the card's figures reached $2,232.2 million, up 21.2% year-on-year; the company's dollar release shows $2,235 million, +23%, a record second quarter. First-quarter growth was higher, 32.6% (+31% in the release), but it came off a weak base: $1.1bn in the first quarter of 2025. Deliveries rose to 65 aircraft from 61, and the firm order backlog reached a record $34.5bn, up 16% year-on-year.
Nevertheless, the absolute revenue level remains high: over the trailing twelve months it reached $6,900.0 million. The company continues to increase turnover, although growth rates have slowed. To assess the sustainability of the trend, it is important to monitor dynamics in the next quarter.
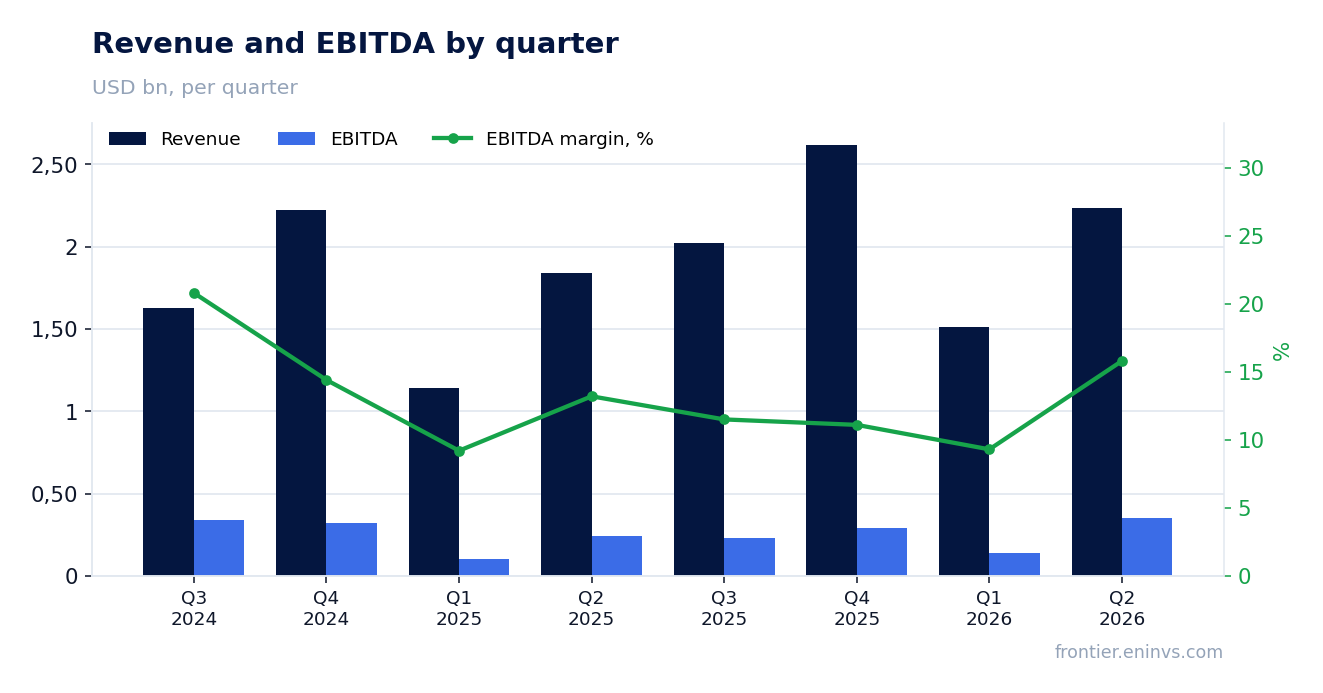
EBITDA rose 45.1%, with margin up to 15.8% from 13.2% a year earlier
EBITDA in the second quarter of 2026 rose 45.1% year-on-year to $352.6 million. The EBITDA margin increased to 15.8% from 13.2% a year earlier. Most of the gain is one-off: the company booked an extraordinary $68m tax credit, worth 300 bp of margin, and paid $8m of US import tariffs. Excluding both, adjusted EBIT margin was 10.6% versus 10.5% a year earlier.
Operating profit also rose strongly, to $287.2 million. But the tax credit sits inside operating profit, so the jump overstates the underlying improvement.
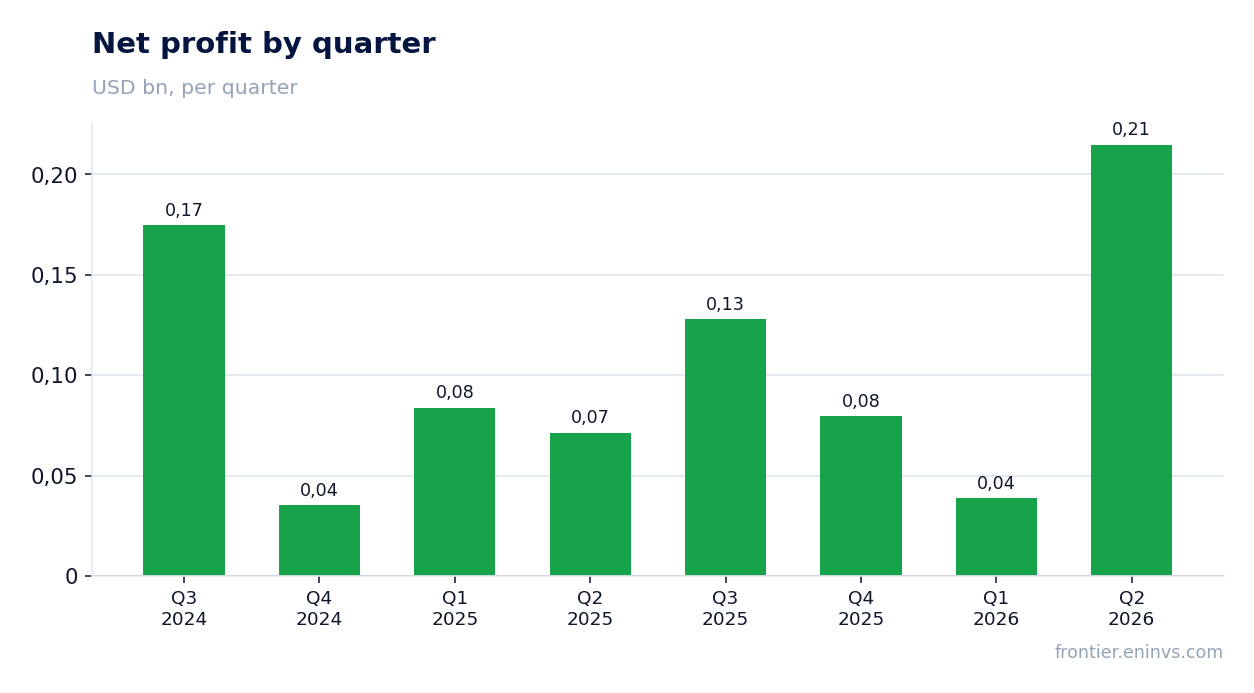
Net profit tripled to $214.8 million, with margin reaching 9.6%
Net profit in the second quarter of 2026 was $214.8 million, triple the figure a year earlier. The net margin rose to 9.6% from 3.9% a year earlier. Embraer attributes the increase to stronger operating performance and lower net financial expenses, partly offset by higher taxes; the tax credit also helped. Net income attributable to Embraer shareholders was $212.6 million versus $78.6 million.
Over the trailing twelve months, net profit reached $422.2 million. Part of the quarter is the one-off tax credit, so the sustainable run-rate is lower than this quarter suggests.
Operating cash flow was $445.3 million with capital expenditures of $111.8 million
In the second quarter of 2026, operating cash flow was $445.3 million, significantly higher than the negative value in the previous quarter. Capital expenditures amounted to $111.8 million, roughly in line with the previous year. Free cash flow was therefore positive and substantial.
Embraer attributes the strong cash flow to operating performance, pre-delivery down-payments on new sales and the same tax credit; adjusted free cash flow excluding Eve was $401 million. In the first quarter of 2026, operating cash flow was negative, which points to volatility between quarters.
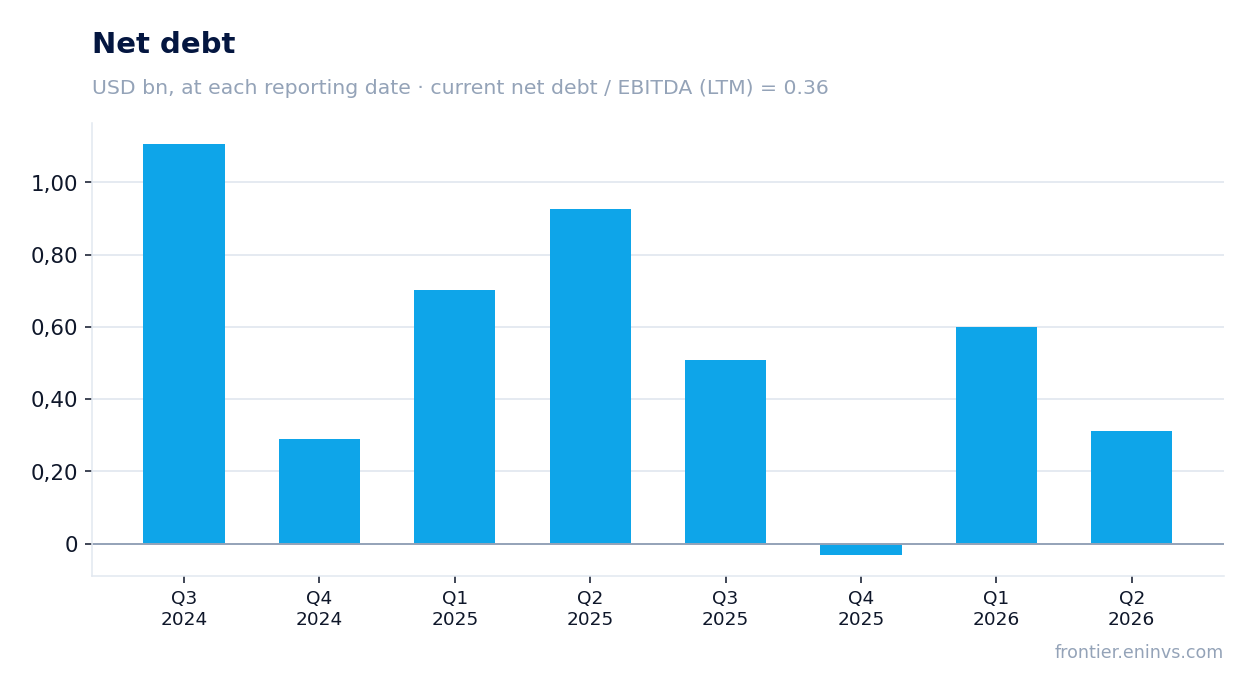
Net debt fell to $0.3 billion as of June 30, 2026, from $0.9 billion a year earlier
Embraer's net debt as of June 30, 2026, was $0.3 billion, down from $0.9 billion as of June 30, 2025. The decline over the year was $0.6 billion. In the second quarter the company also made $236 million of net loan repayments.
The net debt/EBITDA LTM ratio stands at 0.36, indicating low leverage. The company has a significant debt cushion, allowing it to fund development and pay dividends.
Net debt/EBITDA LTM stands at 0.36, indicating low leverage
The net debt/EBITDA LTM ratio at the end of the second quarter of 2026 is 0.36. This is a low level, indicating a comfortable debt burden. For comparison, many industrial companies have this ratio above 2.0.
Low leverage gives Embraer flexibility for investments in development, potential acquisitions, or returning capital to shareholders. On the company's own measure, net debt excluding Eve to adjusted EBITDA, leverage fell to 0.2x from 0.7x a year earlier.
Trailing 12-month dividend yield is 1.26%, paid through interest on equity
Embraer's dividend yield over the trailing 12 months is 1.26%. This is a low figure, especially next to Brazilian deposit rates. The company is not a dividend story, and the bulk of shareholder return comes from capital appreciation.
On June 18, Embraer declared R$200 million (R$0.28 per share) of interest on equity for the second quarter. The company intends to declare it quarterly and, if needed, top it up with a dividend to the legal minimum of 25% of net income; the money is paid once a year after shareholder approval.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 13.5 bn USD |
| P/E (LTM) | 32.0 |
| EV/EBITDA (LTM) | 15.8 |
| P/B | 3.52 |
| Net debt / EBITDA (LTM) | 0.36 |
| ROE | 22.3% |
| Dividend yield (12m) | 1.3% |
Bottom line
The report's strengths are clear: record second-quarter revenue, a record $34.5bn backlog, net profit tripled, and net debt down to $0.3 billion. But the 15.8% EBITDA margin and the profit jump owe much to a one-off tax credit: without it and tariffs, adjusted EBIT margin was 10.6% versus 10.5% a year earlier. The company did raise its 2026 adjusted EBIT margin guidance to 10.0–10.6%. With an EV/EBITDA multiple of 15.8 and 29% upside on the portal model, the stock looks attractive, but the test is the margin without one-offs in the coming quarters.
Open the company's financial profile EMBR →
See also: market overview · valuation map · stock screeners