Lupin: revenue up 10.5% but profit down 21.8% as margin slips
Lupin reported results for Q3 2026. Revenue reached INR 77,855.2 mn, up 10.5% year on year, EBITDA was INR 21,712.1 mn (+1.6%), and net profit came in at INR 11,552.6 mn (-21.8%). Revenue growth decelerated from the prior quarter, while the EBITDA margin fell to 27.9% from 30.3% a year earlier. At an EV/EBITDA of 10.7 versus its own three-year average of 17.1 the stock looks cheaper than its history, but weak profit dynamics and net debt of INR 35,567.3 mn keep us from a positive call – verdict neutral.
Key takeaways
— Revenue grew 10.5% year on year, but that is a deceleration from 33.3% a quarter earlier
— EBITDA added just 1.6%, and the margin fell to 27.9% from 30.3%
— Net profit declined 21.8%, with the net margin down to 14.8% from 21.0%
— Leverage at 0.41x LTM EBITDA is moderate, but net debt rose to INR 35.6 bn
— Dividend yield of 0.9% is modest and does not offset weak profit
— EV/EBITDA of 10.7 is below its own three-year average of 17.1 – the stock is cheaper than its history
— On the portal's model, fair value implies -11% upside
Attractiveness
Key figures, INR bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 70.5 | 77.9 | +10.5% |
| EBITDA | 21.4 | 21.7 | +1.6% |
| Operating profit | 18.2 | 14.7 | -19.2% |
| Net profit | 14.8 | 11.6 | -21.8% |
| EBITDA margin | 30.3% | 27.9% | -2.4 pp |
| Net margin | 21.0% | 14.8% | -6.2 pp |
Revenue grew 10.5% year on year, but that is a deceleration from 33.3% a quarter earlier
In Q3 2026 Lupin's revenue reached INR 77,855.2 mn, up 10.5% from a year earlier. Growth remains double-digit but is markedly slower than in the prior quarter, when revenue rose 33.3% year on year. The deceleration follows two strong quarters – Q1 2026 grew 33.3% and Q2 2026 grew 10.5%.
Compared with the same quarter a year earlier, growth slowed from 23.1% in Q3 2025 to 10.5% now. This may reflect a high base effect as well as a slowdown in key segments, but the report does not disclose the reasons. For investors, the company is still growing, but the sustainability of that growth is in question.
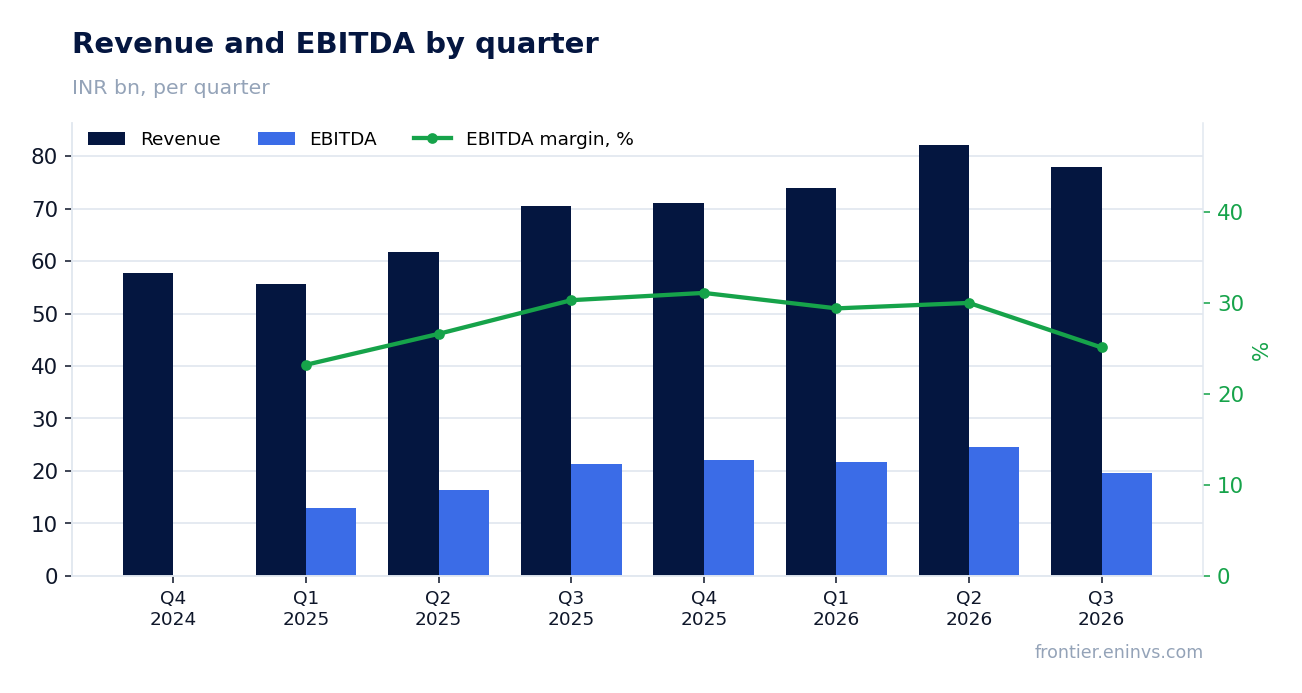
EBITDA added just 1.6%, and the margin fell to 27.9% from 30.3%
EBITDA for Q3 2026 was INR 21,712.1 mn, up only 1.6% year on year. With revenue growing 10.5%, this means costs rose faster than revenue. As a result, the EBITDA margin fell to 27.9% from 30.3% in Q3 2025.
A 2.4 percentage point margin decline is significant for a company of this scale. Operating profit also showed weak dynamics: INR 14,715.0 mn versus INR 18,208.3 mn a year earlier, a decline of 19.2%. This points to cost pressure that is not being offset by revenue growth.
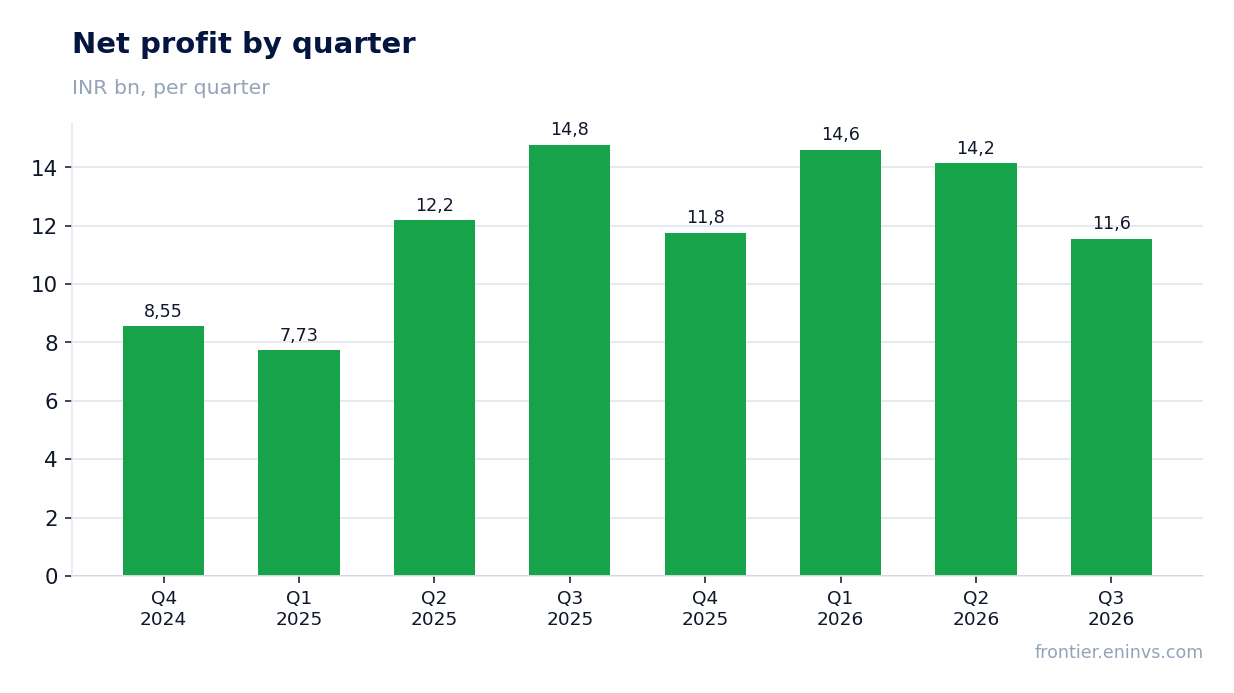
Net profit declined 21.8%, with the net margin down to 14.8% from 21.0%
Lupin's net profit for Q3 2026 was INR 11,552.6 mn, down 21.8% from a year earlier. The net margin fell to 14.8% from 21.0%. The profit decline is deeper than the operating profit drop, which may indicate higher finance costs or one-off factors, but the report does not disclose details.
Over the trailing twelve months net profit was INR 52,061.5 mn. This is the level investors can use to gauge business resilience, but the quarterly dynamics signal pressure on profitability. If the pressure persists, the annual result could be at risk.
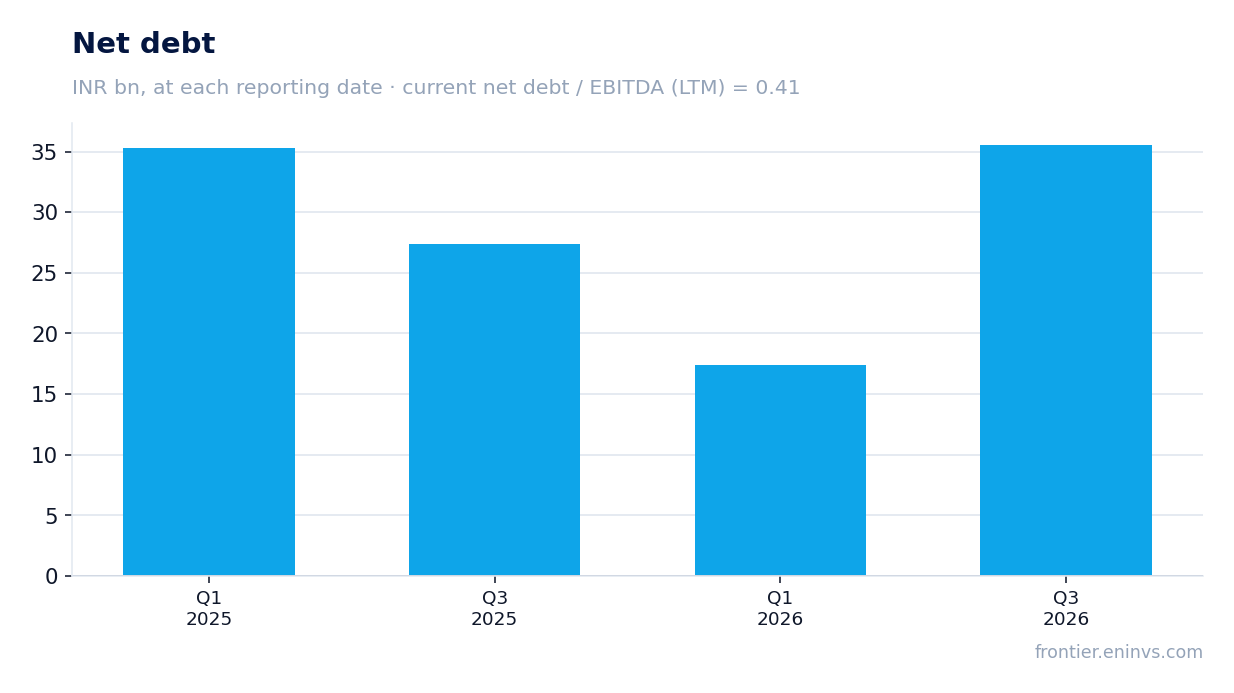
Leverage at 0.41x LTM EBITDA is moderate, but net debt rose to INR 35.6 bn
Lupin's net debt as of 30 September 2026 was INR 35,567.3 mn. This is a moderate level: the ratio of net debt to trailing twelve-month EBITDA is 0.41. Such a metric does not pose serious risks to financial stability.
However, absolute debt has risen: from INR 17,424.7 mn on 31 March 2026 to INR 35,567.3 mn on 30 September 2026, an increase of INR 18,143 mn. Over twelve months net debt rose from INR 27,382.4 mn on 30 September 2025 to INR 35,567.3 mn, an increase of INR 8,184.9 mn. The rise may be linked to investments or working capital, but the report does not detail the reasons.
Dividend yield of 0.9% is modest and does not offset weak profit
Lupin's dividend yield over the trailing twelve months is 0.9%. This is a low level that does not appeal to income-oriented investors. At the current share price, the dividend does not compensate for the risks associated with profit volatility.
The company does not disclose its dividend policy in the provided facts, so it is difficult to assess payout sustainability. However, with net profit down 21.8%, the likelihood of maintaining the dividend at the previous level decreases. For investors, the dividend is not a key attractiveness factor here.
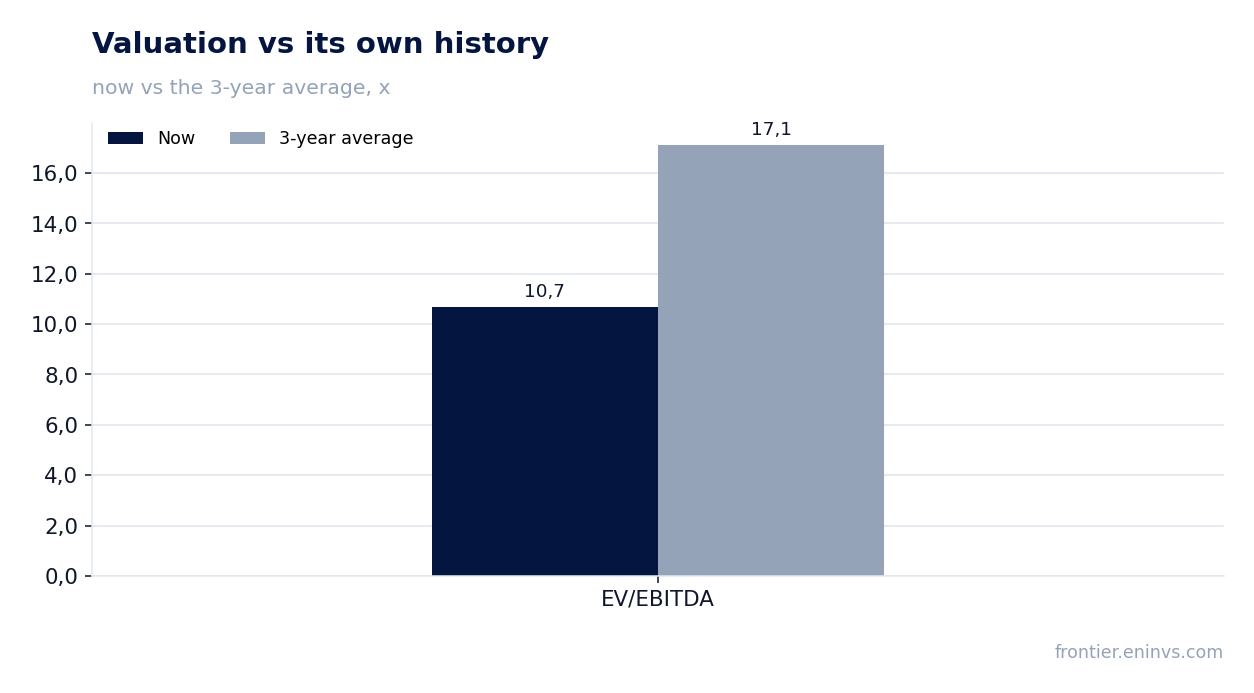
EV/EBITDA of 10.7 is below its own three-year average of 17.1 – the stock is cheaper than its history
Lupin's EV/EBITDA multiple over the trailing twelve months is 10.7. This is 38% below its own three-year average of 17.1. Thus, the stock trades cheaper than usual, which may indicate undervaluation.
However, the trailing twelve-month P/E is 17.5, which does not look low against the backdrop of slowing profit. The EV/EBITDA ratio may be depressed by a high EBITDA level that does not reflect pressure on net profit. Investors should note that a cheap valuation on this multiple does not guarantee growth if profit continues to fall.
On the portal's model, fair value implies -11% upside
According to the portal's fundamental model, Lupin's fair value implies -11% upside to the current market price. This means that, in our assessment, the stock trades above its fair value despite a low EV/EBITDA multiple relative to history.
The model incorporates EBITDA growth and a target multiple, and its result diverges from the cheapness signal on EV/EBITDA. This may be because the market is pricing in further profit deceleration. Investors should treat the model as one tool, not as a final verdict.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 909 bn INR |
| P/E (LTM) | 17.5 |
| EV/EBITDA (LTM) | 10.7 |
| P/B | 4.05 |
| Net debt / EBITDA (LTM) | 0.41 |
| ROE | 19.8% |
| Dividend yield (12m) | 0.9% |
| EV/EBITDA, 3-year average | 17.1 |
Bottom line
Lupin remains a growing company with revenue up 10.5%, but profitability is under pressure: net profit fell 21.8% and margins compressed. Leverage is moderate, but absolute debt has risen. Valuation on EV/EBITDA is below historical levels, yet the portal's model implies -11% upside. Verdict – neutral: the stock looks neither clearly attractive nor unattractive, and a turnaround in profit dynamics is needed to change the assessment.
Open the company's financial profile LUPIN →
See also: market overview · valuation map · stock screeners