Scandinavian Tobacco Group: Q2 2026 revenue fell 1.2%, but EBITDA margin rose to 21.2%
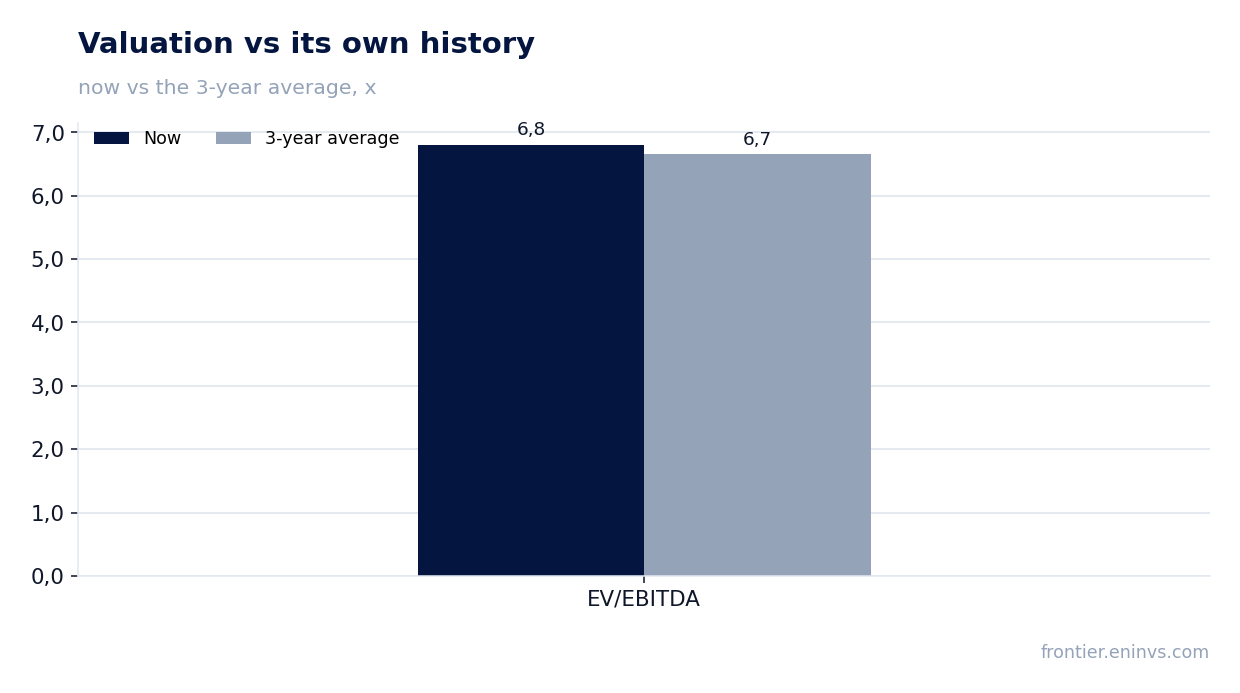
On 13 August, Scandinavian Tobacco Group reported Q2 2026 results. Revenue declined 1.2% year-on-year to DKK 2,334.0 million, EBITDA rose 0.5% to DKK 493.7 million, and net profit fell 4.4% to DKK 216.9 million. The EBITDA margin improved to 21.2% from 20.8% a year earlier. At the current price, the stock trades at 6.81 EV/EBITDA LTM versus its 3-year average of 6.66, and the dividend yield of 6.1% looks attractive, but the portal's model points to 9% downside. Verdict – neutral.
Key takeaways
— Q2 2026 revenue declined 1.2% year-on-year to DKK 2,334.0 million
— Q2 2026 EBITDA rose 0.5% to DKK 493.7 million, with margin up to 21.2%
— Q2 2026 net profit fell 4.4% to DKK 216.9 million
— Operating cash flow over the last 12 months was DKK 869.9 million, with capex of DKK 35.3 million in the quarter
— Net debt at 30 June 2026 was DKK 4.9 billion, down from DKK 5.2 billion a year earlier
— Dividend yield over the last 12 months is 6.1%
— EV/EBITDA LTM of 6.81x is slightly above the 3-year average of 6.66x
Attractiveness
Key figures, DKK bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 2.36 | 2.33 | -1.2% |
| EBITDA | 0.49 | 0.49 | +0.5% |
| Operating profit | 0.38 | 0.34 | -11.1% |
| Net profit | 0.23 | 0.22 | -4.4% |
| Operating cash flow | 0.15 | 0.30 | +97.6% |
| Capex | -0.04 | -0.04 | — |
| EBITDA margin | 20.8% | 21.2% | +0.4 pp |
| Net margin | 9.6% | 9.3% | -0.3 pp |
Q2 2026 revenue declined 1.2% year-on-year to DKK 2,334.0 million
Q2 2026 revenue was DKK 2,334.0 million, down 1.2% from the same period last year. The decline is modest but continues the trend: in Q1 2026 revenue was DKK 1,859.2 million, also below the prior-year level. The company did not disclose reasons in the provided facts, so we simply note that sales slipped slightly.
For a tobacco business, such a move could be due to demand fluctuations or currency effects, but without confirmation from the report we do not assign a cause. Importantly, the revenue decline did not lead to an EBITDA decline – meaning the company managed to offset lower sales either through pricing or cost structure.
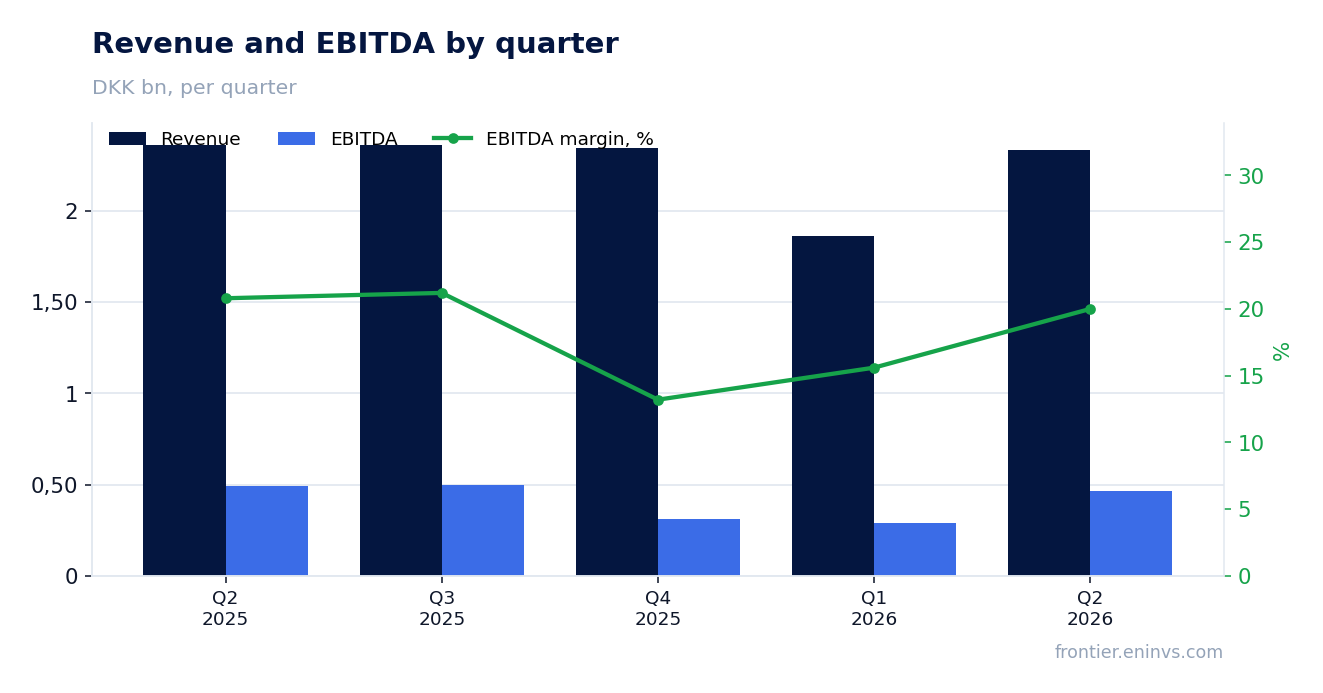
Q2 2026 EBITDA rose 0.5% to DKK 493.7 million, with margin up to 21.2%
Q2 2026 EBITDA was DKK 493.7 million, up 0.5% year-on-year. The EBITDA margin improved to 21.2% from 20.8% last year. Margin growth on declining revenue means the company cut costs or improved its sales mix.
Operating profit for the quarter was DKK 339.3 million. The operating margin was 14.5%, above the average of recent quarters. This indicates that even with a slight revenue decline, the company maintains control over expenses.
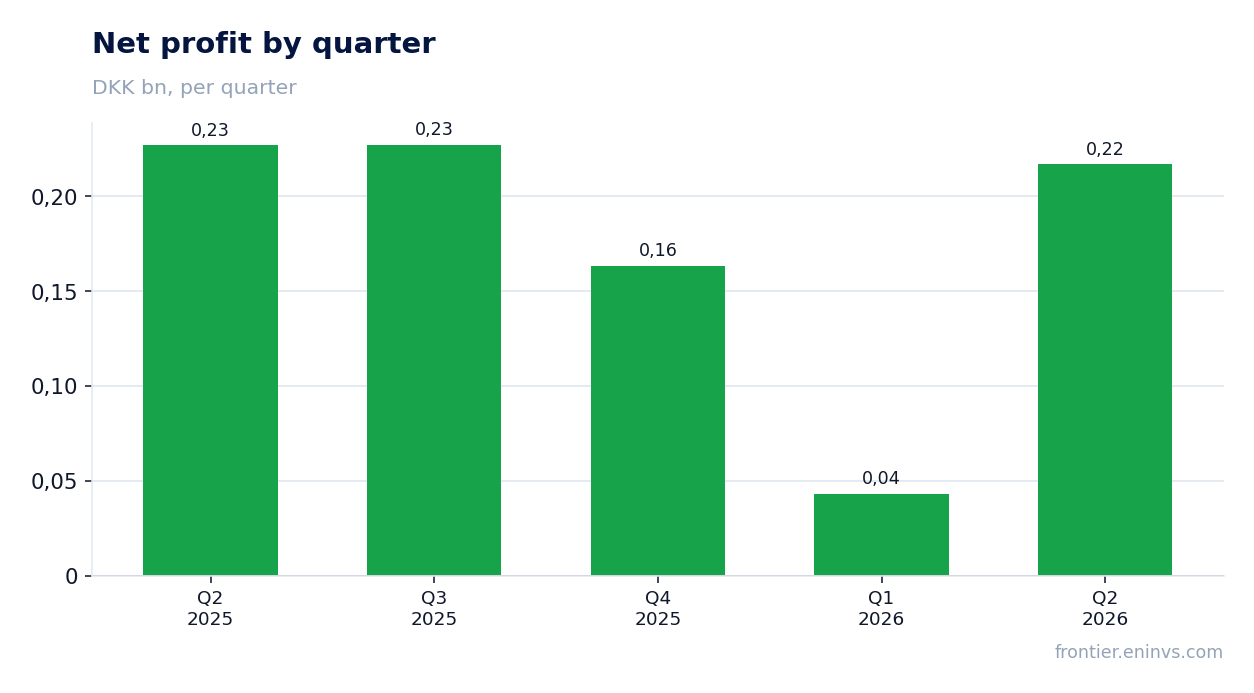
Q2 2026 net profit fell 4.4% to DKK 216.9 million
Q2 2026 net profit was DKK 216.9 million, down 4.4% year-on-year. The net margin fell to 9.3% from 9.6%. Profit declining while EBITDA grows indicates additional expenses below the operating line – possibly interest or taxes.
Over the last 12 months, net profit was DKK 651.2 million. This is the level earned over the year and is important for the dividend base. The 4.4% quarterly profit decline is not critical, but it shows that EBITDA growth does not fully flow through to net profit.
Operating cash flow over the last 12 months was DKK 869.9 million, with capex of DKK 35.3 million in the quarter
Operating cash flow over the last 12 months was DKK 869.9 million. In Q2 2026 it was DKK 295.4 million, significantly higher than DKK 149.5 million a year earlier. Such cash flow growth on declining revenue indicates improved working capital management.
Capex for the quarter was DKK 35.3 million, slightly below DKK 40.1 million a year earlier. The company invests moderately, allowing it to generate free cash flow. Over the last 12 months, capex was at a level that does not create excessive pressure on the balance sheet.
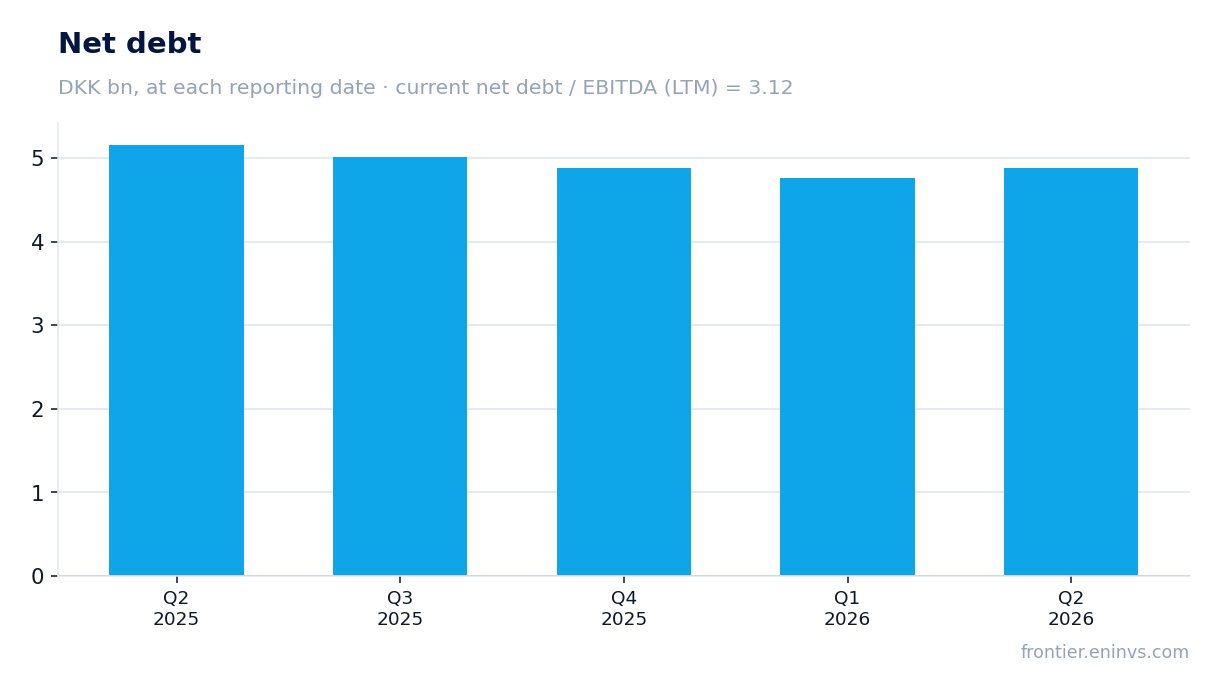
Net debt at 30 June 2026 was DKK 4.9 billion, down from DKK 5.2 billion a year earlier
Net debt at 30 June 2026 was DKK 4,880.3 million, or DKK 4.9 billion. A year earlier, at 30 June 2025, it was DKK 5,158.4 million, or DKK 5.2 billion. The 12-month reduction was DKK 0.3 billion. This is a positive signal, although debt load remains significant.
The net debt to EBITDA ratio over the last 12 months is 3.12. This is a moderate level that the company likely considers comfortable. Interest on debt probably consumes part of operating profit, explaining the net profit decline despite EBITDA growth.
Dividend yield over the last 12 months is 6.1%
The dividend yield over the last 12 months is 6.1%. This is a high level, making the stock attractive for income-oriented investors. The company pays dividends, and the current yield exceeds that of many debt instruments.
With net profit over the last 12 months of DKK 651.2 million and a market capitalisation of DKK 5,773.3 million, dividend payments represent a significant portion of profit. If profit declines, the company may be forced to cut the dividend. However, current cash flow appears sufficient to sustain payments.
EV/EBITDA LTM of 6.81x is slightly above the 3-year average of 6.66x
EV/EBITDA LTM is 6.81. The 3-year average of this multiple is 6.66. Thus, the stock trades slightly above its historical norm. This may limit upside potential if profit does not start growing faster.
P/E LTM is 8.87, which also does not look cheap for a company with declining revenue. The portal's model estimates the fair value of the share at 9% below the current market price. This is another argument for a cautious view on valuation.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 5.77 bn DKK |
| P/E (LTM) | 8.9 |
| EV/EBITDA (LTM) | 6.8 |
| P/B | 0.67 |
| Net debt / EBITDA (LTM) | 3.12 |
| Operating cash flow (LTM) | 0.87 bn |
| ROE | 10.0% |
| Dividend yield (12m) | 6.1% |
| EV/EBITDA, 3-year average | 6.7 |
Bottom line
In Q2 2026, Scandinavian Tobacco Group reported a 1.2% decline in revenue and a 4.4% drop in net profit, but EBITDA rose 0.5% and the margin improved to 21.2%. Operating cash flow over the last 12 months was DKK 869.9 million, and net debt fell to DKK 4.9 billion. The 6.1% dividend yield supports interest in the stock, but EV/EBITDA is slightly above its historical average, and the portal's model points to 9% downside. Verdict – neutral: strong cash flows and dividend are offset by weak revenue and profit dynamics, with no clear growth driver.
Open the company's financial profile STG →
See also: market overview · valuation map · stock screeners