BBAJIO: quarterly profit fell to MXN 1.78 bn even as net interest income rose to MXN 6.60 bn
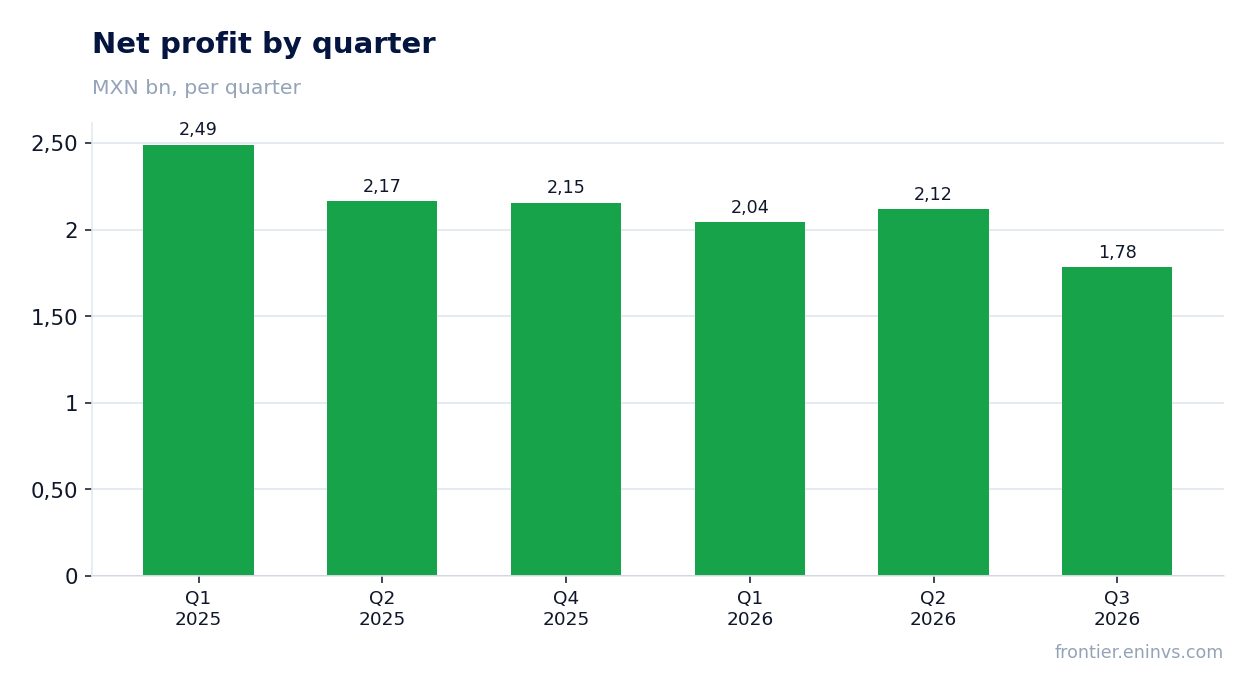
On 30 September 2026, MX_BBAJIO reported results for the third quarter of 2026. Net interest income came in at MXN 6,601.2 mn, net profit at MXN 1,781.7 mn and capital expenditures at minus MXN 1,317.1 mn. Quarterly profit was almost four times smaller than net interest income, while over the trailing twelve months the bank earned MXN 9,079.0 mn on net interest income of MXN 26,200.0 mn. At the current price the share looks rather attractive: P/E LTM 7.3, ROE 14.7%, dividend yield 8.5%, and the portal model implies 11% upside to fair value.
Key takeaways
— Net interest income rose to MXN 6,601.2 mn, but quarterly profit was only MXN 1,781.7 mn
— Over the trailing twelve months the bank earned MXN 9,079.0 mn on net interest income of MXN 26,200.0 mn
— Capital expenditures in the third quarter were minus MXN 1,317.1 mn – a return of funds, not new investment
— The 8.5% dividend yield is well above the yield we consider fair for a bank with a 14.7% ROE
— P/E LTM of 7.3 and 11% upside on the portal model leave the share on the attractive side
Attractiveness
Key figures, MXN bn
| Metric | — | Q3 2026 | Change |
|---|---|---|---|
| Net profit | — | 1.78 | — |
| Capex | — | -1.32 | — |
Net interest income rose to MXN 6,601.2 mn, but quarterly profit was only MXN 1,781.7 mn
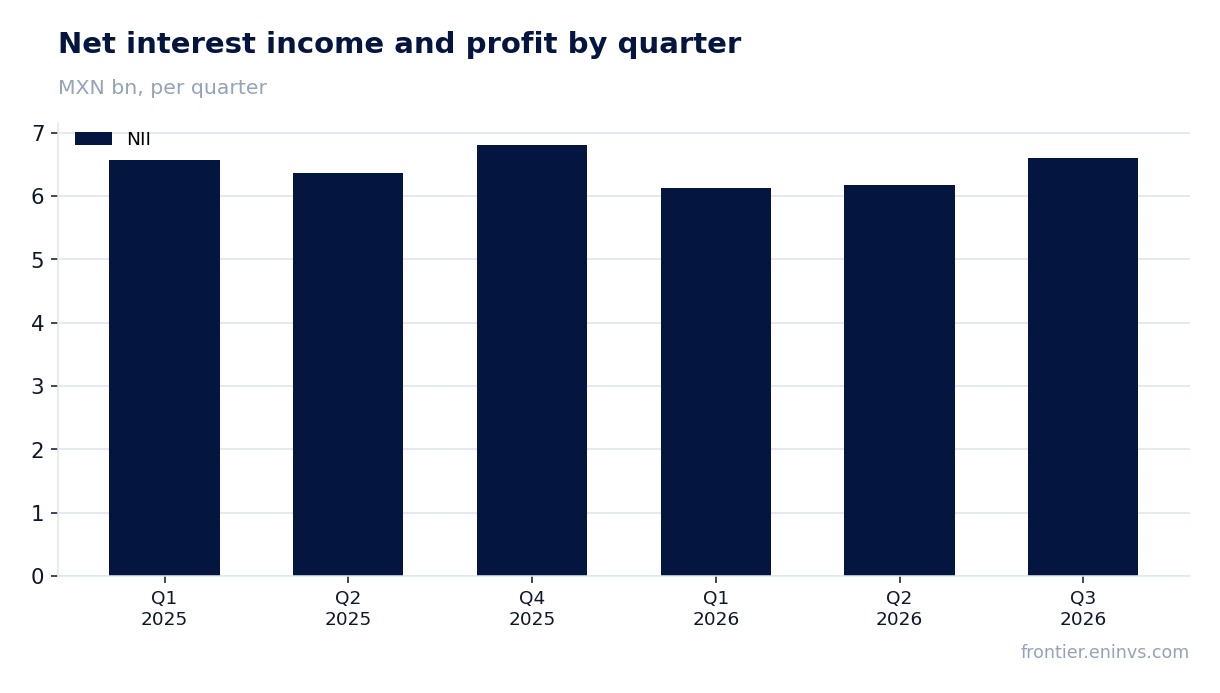
The bank's net interest income in the third quarter of 2026 was MXN 6,601.2 mn. This is the main revenue source, and it remains stable: MXN 6,172.0 mn a quarter earlier and MXN 6,356.0 mn a year earlier.
Yet net profit for the same quarter was only MXN 1,781.7 mn. A gap of almost four times between net interest income and profit means most of the income is consumed by expenses – provisions, operating costs or taxes. The facts give no breakdown, so the specific line cannot be named, but the scale of the gap speaks for itself.
For a holder this is the key question of the report: the revenue base is growing, but a smaller part of it reaches profit. Until that ratio changes, quarterly profit will remain weaker than net interest income alone would allow.
Over the trailing twelve months the bank earned MXN 9,079.0 mn on net interest income of MXN 26,200.0 mn
On a trailing basis, over the last twelve months net profit was MXN 9,079.0 mn and net interest income MXN 26,200.0 mn. This is a smoother base than a single quarter and shows the bank remains profitable.
The ratio of profit to net interest income over twelve months is about one third. That is higher than in the third quarter, where less than a quarter of income reached profit. The quarter was therefore weaker than average, and the annual picture looks better than the latest report.
This is the base for P/E LTM of 7.3 and ROE of 14.7%. Both metrics rest on twelve-month profit, not the quarter, so the valuation is not distorted by a weak third quarter.
Capital expenditures in the third quarter were minus MXN 1,317.1 mn – a return of funds, not new investment
Capital expenditures in the third quarter of 2026 are shown with a minus sign: minus MXN 1,317.1 mn. For a bank this means investment in fixed assets and infrastructure was less than the return or disposal of assets – cash came into the bank rather than leaving it.
This is a one-off or at least atypical picture: in the first quarter of 2026 capital expenditures were MXN 156.9 mn, in the second MXN 260.0 mn. The negative value in the third quarter stands out against prior periods and supports liquidity.
For a holder this is a rather neutral fact: the bank is not increasing capital investment, and the freed-up funds can go to dividends or to covering expenses. Such a flow cannot be called sustainable, but in the reporting quarter it worked in favour of the cash position.
The 8.5% dividend yield is well above the yield we consider fair for a bank with a 14.7% ROE
The dividend yield over the last twelve months is 8.5%. With a 14.7% ROE and a P/E LTM of 7.3, the bank pays holders a significant share of profit: the yield is well above what one would expect from a company earning 14.7% on capital.
Our estimate of the current-year dividend rests on trailing twelve-month profit of MXN 9,079.0 mn and on the established payout practice. If the bank keeps its current distribution share, the dividend should stay near a level that gives a yield of about 8.5% at the current price. This is our estimate, not a declared payment.
The key risk to the dividend is the weak quarter: profit in the third quarter was only MXN 1,781.7 mn. If that dynamic repeats, the annual profit base will shrink and the payment may be smaller. The 8.5% yield is the price of that risk, and it looks sufficient.
P/E LTM of 7.3 and 11% upside on the portal model leave the share on the attractive side
The share trades at a P/E LTM of 7.3 with an ROE of 14.7%. That is a low multiple for a bank earning a double-digit return on capital, and it leaves room if profit does not deteriorate.
On the portal model, the upside to fair value is 11%. This is our own estimate based on annual profit and market capitalisation, not a market consensus. It says the current price is below what the model considers justified.
The valuation rests on trailing twelve-month profit. If the third quarter marks the start of a weaker run, the profit base will shrink and the multiple will rise without any change in price. That is the main risk to the current valuation.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 66.0 bn MXN |
| P/E (LTM) | 7.3 |
| P/B | 1.38 |
| ROE | 14.7% |
| Dividend yield (12m) | 8.5% |
Bottom line
The strong side of the report is stable net interest income of MXN 6,601.2 mn and twelve-month profit of MXN 9,079.0 mn, which underpins the 7.3 P/E and 14.7% ROE. The weak spot is quarterly profit of MXN 1,781.7 mn: less than a quarter of net interest income reaches it, and that is the key question for a holder. Negative capital expenditures of minus MXN 1,317.1 mn supported the cash position, but only one-off. The 8.5% dividend yield and 11% upside on the portal model outweigh this, so the share looks rather attractive; the verdict would change if the weak quarterly profit repeats.
Open the company's financial profile BBAJIO →
See also: market overview · valuation map · stock screeners