MX_LIVERPOL: revenue accelerated to +5.5%, but net profit fell 14.5% — growth is eaten below EBITDA
For the third quarter of 2026, ended 30 September, MX_LIVERPOL reported revenue of 49,114.7 million MXN (+5.5% YoY), EBITDA of 7,476.4 million MXN (+17.4%) and net profit of 3,381.7 million MXN (–14.5%). The EBITDA margin rose to 15.2% from 13.7%, while the net margin fell to 6.9% from 8.5%. At an EV/EBITDA of 4.3 versus its own three-year average of 4.0 and a portal-model upside of +17%, the share looks rather attractive, but weakness below EBITDA and rising debt temper the assessment.
Key takeaways
— Revenue accelerated to +5.5% YoY from +1.5% a quarter earlier, the best pace since the start of 2026
— EBITDA rose 17.4% on revenue growth of 5.5%, lifting the margin to 15.2% from 13.7%
— Net profit fell 14.5% even as EBITDA grew: higher costs below EBITDA consumed the operating leverage
— Operating cash flow of 6,142.8 million MXN did not cover capital expenditure of 4,873.9 million MXN by a wide margin
— Net debt rose to 19.2 billion MXN from 18.5 billion on 30 June, but fell from 32.8 billion over 12 months
— Dividend yield of 2.9% on payouts supported by LTM profit of 18.0 billion MXN
— EV/EBITDA of 4.3 is above its own three-year average of 4.0, while the portal model implies +17% upside
Attractiveness
Key figures, MXN bn
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 46.6 | 49.1 | +5.5% |
| EBITDA | 6.37 | 7.48 | +17.4% |
| Operating profit | 4.81 | 5.32 | +10.6% |
| Net profit | 3.95 | 3.38 | -14.5% |
| Operating cash flow | 5.32 | 6.14 | +15.5% |
| Capex | — | 4.87 | — |
| EBITDA margin | 13.7% | 15.2% | +1.5 pp |
| Net margin | 8.5% | 6.9% | -1.6 pp |
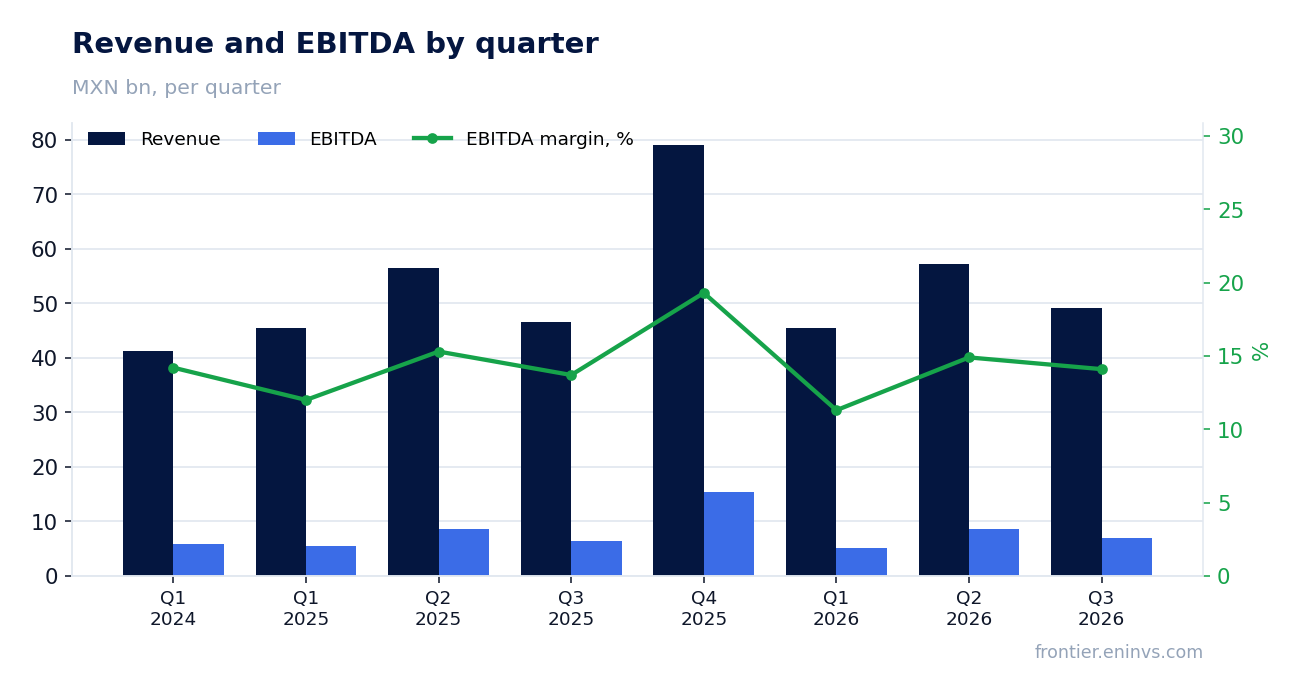
Revenue accelerated to +5.5% YoY from +1.5% a quarter earlier, the best pace since the start of 2026
In the third quarter of 2026, revenue reached 49,114.7 million MXN, up 5.5% from a year earlier. A quarter earlier growth was more modest at +1.5%, and in the first quarter revenue even declined by 0.2%. The acceleration to +5.5% is the strongest pace since the start of 2026.
The quarterly sequence shows the company moved past a weak start to the year and returned to steady growth. Second-quarter 2026 revenue was 57,290.2 million MXN, while the third quarter came in at 49,114.7 million MXN; the sequential decline reflects seasonality rather than lost demand, since year-on-year growth is intact.
For assessing durability, it matters that the acceleration came alongside EBITDA growth. If revenue holds a pace above 5% in the next report, it will confirm the company has returned to growth after a weak first quarter.
EBITDA rose 17.4% on revenue growth of 5.5%, lifting the margin to 15.2% from 13.7%
EBITDA for the third quarter of 2026 was 7,476.4 million MXN, up 17.4% from a year earlier. EBITDA growth was more than three times revenue growth, and this showed up in the margin: it rose to 15.2% from 13.7% a year earlier.
Operating profit was 5,318.2 million MXN. The gap between EBITDA and operating profit – 2,158.2 million MXN – is depreciation, and its share of revenue is moderate. The main contribution to the margin gain came not from operating leverage at the gross-profit level but from containment of costs below EBITDA.
A 1.5 percentage-point margin improvement is notable for a company with quarterly revenue of about 49 billion MXN. If the margin holds near 15%, full-year EBITDA could come in above the current trajectory.
Net profit fell 14.5% even as EBITDA grew: higher costs below EBITDA consumed the operating leverage
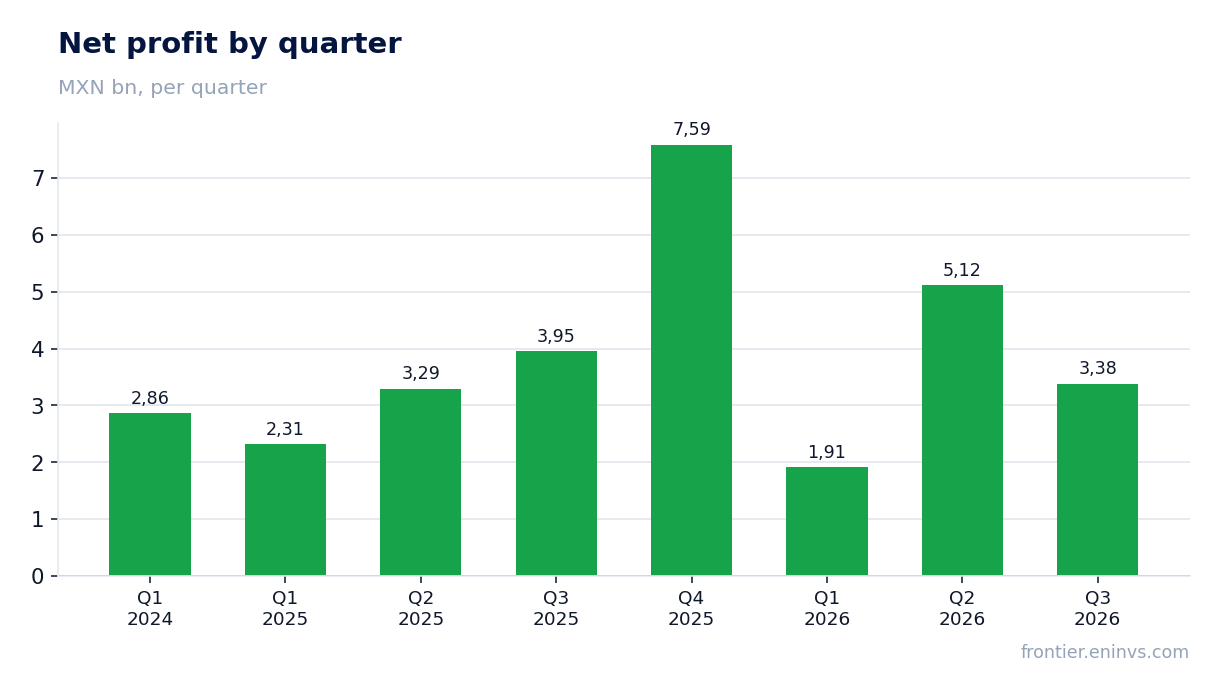
Net profit for the third quarter of 2026 was 3,381.7 million MXN, down 14.5% from a year earlier. That diverges from EBITDA growth of 17.4% and from operating profit of 5,318.2 million MXN.
The gap between operating and net profit – 1,936.4 million MXN – reflects interest, taxes and other items. With a net margin of 6.9% versus 8.5% a year earlier, pressure below the operating line intensified. The facts do not disclose the cause, but the size of the gap shows that the weak spot in the report sits there, not in operations.
For a holder this is the key question: if pressure below EBITDA persists, operating profit growth will not translate into earnings per share. The next report will show whether this was a one-off or a new norm.
Operating cash flow of 6,142.8 million MXN did not cover capital expenditure of 4,873.9 million MXN by a wide margin
Operating cash flow for the third quarter of 2026 was 6,142.8 million MXN, while capital expenditure was 4,873.9 million MXN. Free cash flow was therefore positive but modest, at about 1.3 billion MXN.
Capital expenditure rose noticeably: a quarter earlier it was 1,238.6 million MXN, and a year earlier in the third quarter it was not disclosed. Capex of 4.9 billion MXN – almost 10% of revenue – means the company is investing in maintaining and expanding capacity.
This matters for the dividend: at this level of capital expenditure, free cash flow remains modest, and payouts rely on profit rather than cash flow. If capex stays high, the dividend will be sensitive to any slowdown in operating cash flow.
Net debt rose to 19.2 billion MXN from 18.5 billion on 30 June, but fell from 32.8 billion over 12 months
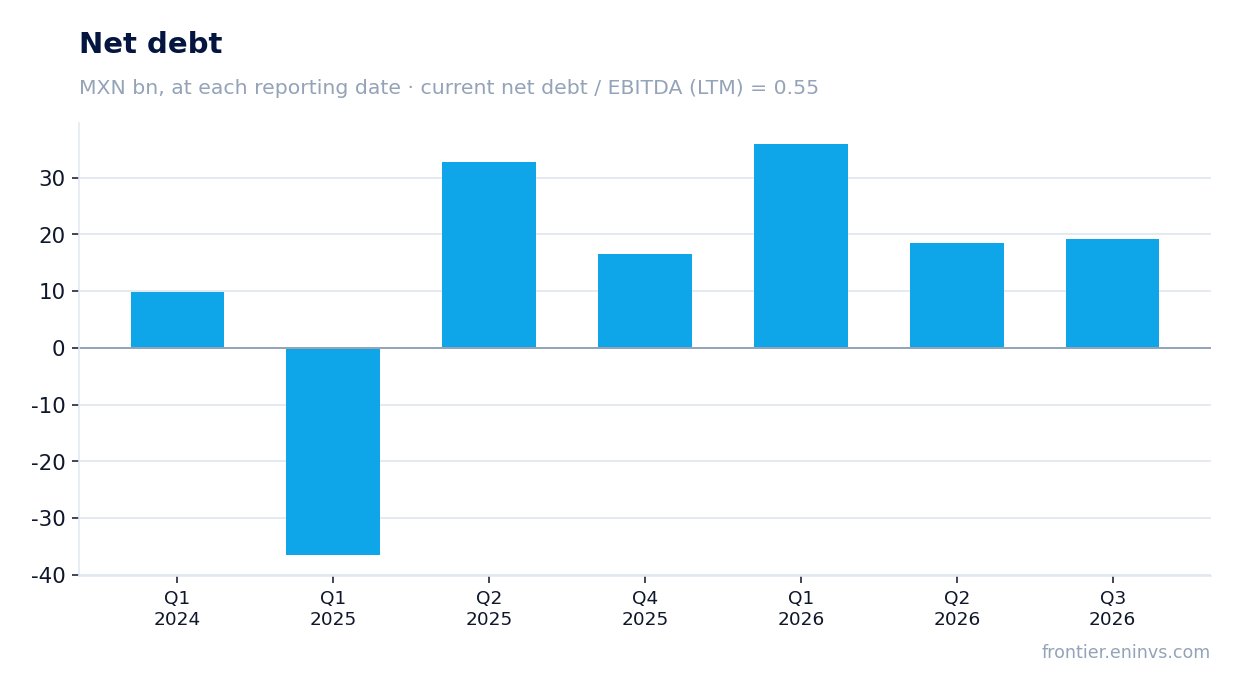
Net debt at 30 September 2026 was 19,236.5 million MXN versus 18,506.5 million on 30 June 2026 – an increase of 0.7 billion MXN over the quarter. Over 12 months debt fell significantly: from 32,835.3 million MXN on 30 June 2025 to 19,236.5 million on 30 September 2026, a decline of 13.6 billion MXN.
The ratio of net debt to EBITDA over the last 12 months is 0.55. That is a moderate level, leaving room for manoeuvre. The decline in debt over the year alongside EBITDA growth means the company directed part of its cash flow to reducing liabilities.
The quarterly increase of 0.7 billion MXN does not change the picture: the leverage level remains low. For a holder it matters that debt does not grow faster than EBITDA, otherwise the advantage of low leverage would disappear.
Dividend yield of 2.9% on payouts supported by LTM profit of 18.0 billion MXN
The dividend yield over the last 12 months is 2.9%. Payouts are supported by profit of 18,004.4 million MXN over the trailing twelve months. With a market capitalisation of 134,273.3 million MXN, the yield is moderate but stable.
Our estimate for the current year's dividend is based on LTM profit and the current yield: if the payout ratio holds, the payment will stay near the current level. The key risk is pressure on net profit below EBITDA: if quarterly profit remains at 3.4 billion MXN, the annual base for the dividend could come in below LTM.
A yield of 2.9% is below the key rate, but for a company with low leverage and growing EBITDA it is an acceptable level. A cut in payouts is possible if net profit falls further or capital expenditure – already 4.9 billion MXN for the quarter – rises.
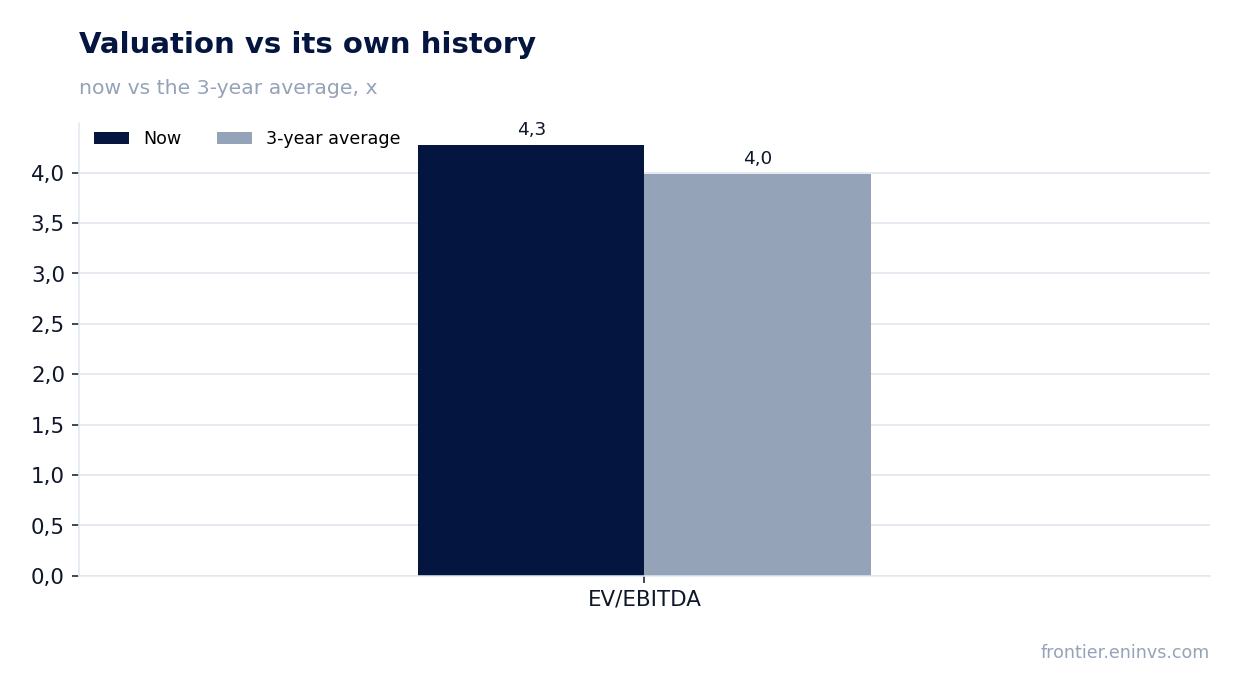
EV/EBITDA of 4.3 is above its own three-year average of 4.0, while the portal model implies +17% upside
The EV/EBITDA multiple over the last 12 months is 4.3 versus its own three-year average of 4.0. The share trades 7% above its own history on this multiple. P/E LTM is 7.5, which looks low for a market with growing EBITDA.
The portal model, which compares EBITDA growth with the target multiple and market capitalisation, implies upside to fair value of +17%. This is our own estimate, not a market consensus.
The combination of a modest premium to its own history and the model's upside means the market has already partly priced in a profit recovery. For further gains, net profit needs to stop falling and EBITDA needs to hold its margin above 15%.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 134 bn MXN |
| P/E (LTM) | 7.5 |
| EV/EBITDA (LTM) | 4.3 |
| P/B | 0.75 |
| Net debt / EBITDA (LTM) | 0.55 |
| Operating cash flow (LTM) | 35.0 bn |
| ROE | 7.5% |
| Dividend yield (12m) | 2.9% |
| EV/EBITDA, 3-year average | 4.0 |
Bottom line
The report's strength was revenue growth to +5.5% and an EBITDA margin of 15.2%: operations accelerated while costs below EBITDA were contained. Weakness is concentrated in net profit, which fell 14.5% on items below the operating line, and in capital expenditure, which consumes free cash flow. Debt fell over the year from 32.8 billion to 19.2 billion MXN, and the net debt to EBITDA ratio is 0.55 – a moderate load. The question for a holder now is whether net profit recovers and the EBITDA margin holds above 15%. Given a multiple above its own history and the portal model's +17% upside, the share looks rather attractive.
Open the company's financial profile LIVERPOL →
See also: market overview · valuation map · stock screeners