ArenaData: H1 revenue up 85.8%, but loss only halved — and it's still a loss
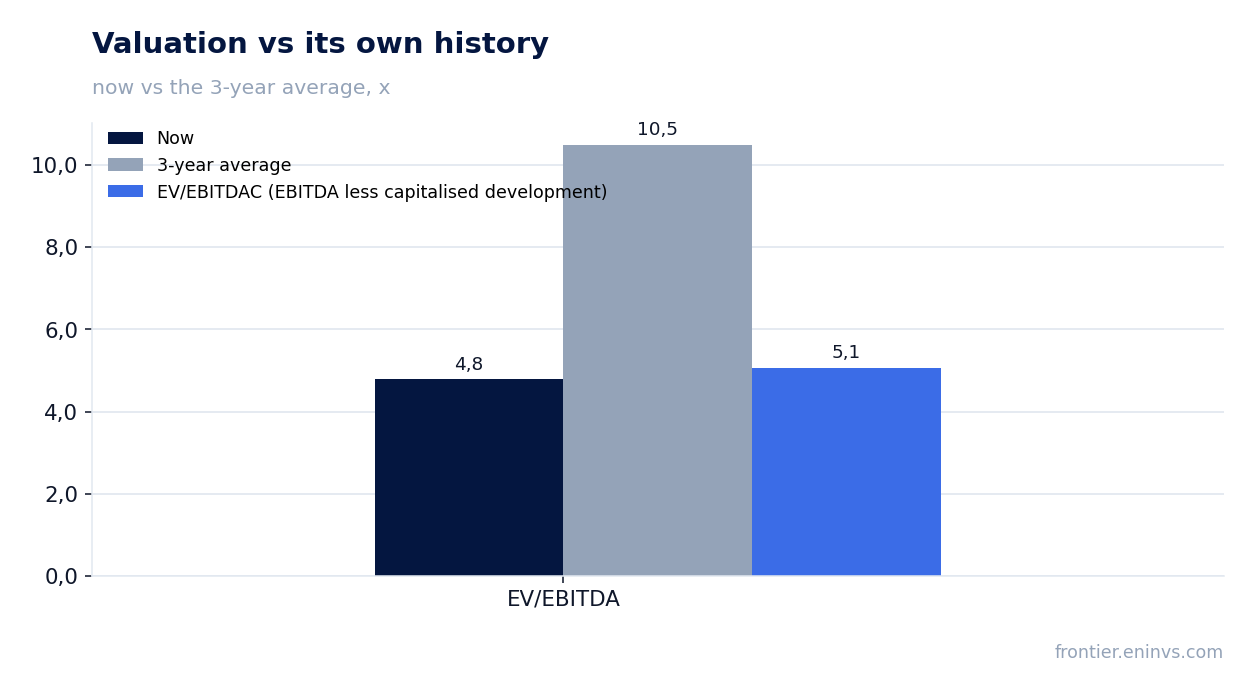
24 июля ArenaData раскрыла результаты за первое полугодие 2026 года. Выручка выросла на 85,8% год к году, до 2 520,5 млн руб., а чистый убыток сократился с 920,0 млн до 347,0 млн руб. На текущей цене акция выглядит привлекательно: мультипликатор EV/EBITDAC LTM в 5,1 раза заметно ниже среднего за три года, а дивидендная доходность 7,5% превышает наш справедливый уровень 7,0%.
Key takeaways
— H1 revenue grew 85.8% to RUB 2,520.5 million, while the loss more than halved
— H1 EBITDA margin was minus 17.4% versus minus 87.8% a year earlier — loss-making sharply reduced
— H1 net margin improved to minus 13.8% from minus 67.8%
— Net debt is negative: minus RUB 1,218.1 million, net debt/EBITDA LTM at minus 0.31
— Capitalised development costs in H1 were RUB 44.0 million — this supported EBITDA but not cash flow
— H1 operating cash flow was RUB 803.0 million, covering capex and dividends
— Dividends over the last 12 months were RUB 6.43 per share, yield 7.5% versus our fair 7.0%
Attractiveness
Key figures, RUB bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 1.36 | 2.52 | +85.8% |
| EBITDA | -1.19 | -0.44 | — |
| Operating profit | -1.25 | -0.56 | — |
| Net profit | -0.92 | -0.35 | — |
| Operating cash flow | 0.39 | 0.80 | +104.7% |
| Capex | 0.19 | 0.04 | -76.4% |
| EBITDA margin | -87.8% | -17.4% | +70.4 pp |
| Net margin | -67.8% | -13.8% | +54.0 pp |
H1 revenue grew 85.8% to RUB 2,520.5 million, while the loss more than halved
In H1 2026, ArenaData's revenue reached RUB 2,520.5 million, up 85.8% from RUB 1,356.4 million in the same period last year. Key drivers were DBMS licences at RUB 836.4 million (2.3x growth), technical support at RUB 973.1 million (up 59.6%), and project work at RUB 637.2 million (up 2.7x).
The net loss narrowed from RUB 920.0 million to RUB 347.0 million, more than halving. The loss remains significant, but the trend points toward breakeven, especially given seasonality — revenue typically concentrates in H2.
H1 EBITDA margin was minus 17.4% versus minus 87.8% a year earlier — loss-making sharply reduced
EBITDA for H1 2026 remained negative at minus RUB 438.6 million, but this is a vast improvement from minus RUB 1,190.8 million a year earlier. The EBITDA margin rose from minus 87.8% to minus 17.4%.
The main driver was revenue growing faster than costs: administrative expenses were nearly flat (RUB 2,320.1 million vs RUB 2,262.9 million), while cost of sales rose from RUB 177.7 million to RUB 564.3 million — still far below the revenue growth rate.
H1 net margin improved to minus 13.8% from minus 67.8%
The net loss narrowed to RUB 347.0 million, implying a net margin of minus 13.8% versus minus 67.8% a year earlier. The improvement came from both revenue growth and a lower share of administrative expenses.
Finance income of RUB 271.1 million (mainly interest on deposits and loans to related parties) partially offset the operating loss. Income tax benefit added another RUB 28.9 million.
Net debt is negative: minus RUB 1,218.1 million, net debt/EBITDA LTM at minus 0.31
As of end-June 2026, ArenaData's net debt was minus RUB 1,218.1 million, meaning cash and equivalents (RUB 1,788.3 million) far exceed total debt (RUB 215.3 million, including lease liabilities). The net debt/EBITDA LTM ratio is minus 0.31.
Over the last 12 months, net debt declined by RUB 1.1 billion, although it rose by RUB 0.9 billion over the half-year — the company spent heavily on dividends and buying out minority stakes in subsidiaries.
Capitalised development costs in H1 were RUB 44.0 million — this supported EBITDA but not cash flow
ArenaData capitalises part of its development costs: in H1, capitalised costs were RUB 44.0 million (vs RUB 336.6 million a year earlier). This reduces the operating loss but does not create cash flow.
EBITDAC LTM (EBITDA less capitalised development) is RUB 3,617.0 million, only slightly below EBITDA LTM of RUB 3,902.7 million. Thus, capitalisation does not distort the picture over the last 12 months, but it was significant in the reported half-year.
H1 operating cash flow was RUB 803.0 million, covering capex and dividends
Operating cash flow for H1 2026 was RUB 803.0 million versus RUB 392.4 million a year earlier. The growth was driven by improved operating results and a RUB 1,488.2 million reduction in receivables.
Capital expenditures (purchases of PP&E and intangibles) were only RUB 44.0 million, well below operating cash flow. Dividends paid to parent shareholders reached RUB 1,367.9 million in H1, exceeding operating cash flow, but the company covered the gap from its accumulated cash.
Dividends over the last 12 months were RUB 6.43 per share, yield 7.5% versus our fair 7.0%
Over the last 12 months, ArenaData paid RUB 6.43 per share, providing a dividend yield of 7.5%. Our model estimates a fair yield of 7.0% for this stock, so the current yield is higher — the share looks undervalued on a dividend basis.
The payout ratio is 0.3 of LTM profit — a moderate level that the company can sustain. Our model forecasts the same RUB 6.43 per share for the next period, implying a forward yield of 7.5%.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 19.9 bn ₽ |
| P/E (LTM) | 5.6 |
| EV/EBITDA (LTM) | 4.8 |
| EV/EBITDAC (EBITDA less capitalised development) | 5.1 |
| P/B | 8.34 |
| Net debt / EBITDA (LTM) | -0.31 |
| Operating cash flow (LTM) | 3.69 bn |
| ROE | -14.6% |
| Dividend yield (12m) | 7.5% |
| EV/EBITDA, 3-year average | 10.5 |
Bottom line
ArenaData отчиталась за полугодие с сильным ростом выручки и значительным сокращением убытка, что подтверждает правильность стратегии консолидации и фокуса на СУБД. Однако компания всё ещё убыточна на уровне чистой прибыли, и улучшение во многом обеспечено эффектом масштаба, а не разовыми факторами. При этом баланс остаётся крепким: чистый долг отрицательный, а денежный поток покрывает инвестиции. С учётом мультипликатора EV/EBITDAC LTM в 5,1 раза против среднего за три года 10,5 раза и дивидендной доходности выше нашего справедливого уровня, акция выглядит привлекательно. Ключевой вопрос — сможет ли компания выйти на положительную чистую прибыль во втором полугодии и сохранить темпы роста.
Open the company's financial profile DATA →
See also: market overview · valuation map · stock screeners