IVA Technologies: profit down 72%, but cash keeps flowing
25 августа IVA Technologies раскрыла результаты за первое полугодие 2026 года. Выручка снизилась на 8,5% год к году, чистая прибыль обвалилась на 72,0%, однако операционный денежный поток за последние 12 месяцев составил 1,7 млрд руб. При текущей цене акция выглядит привлекательно: мультипликатор EV/EBITDA в 4,0 раза ниже собственного трёхлетнего среднего значения, а дивидендная доходность по нашей модели приближается к справедливой.
Key takeaways
— Revenue for the half-year fell 8.5%, but operating cash flow over 12 months reached RUB 1.7 billion.
— Net profit dropped 72% on lower margins: net margin was 8.8% versus 28.8% a year earlier.
— EBITDA margin declined to 36.7% from 42.4%, reflecting pressure on operating efficiency.
— Leverage remains low: net debt of RUB 434.6 million is 0.24x EBITDA over the last 12 months.
— Shares trade at a discount to their own history: EV/EBITDA of 4.0x versus the three-year average of 9.0x.
— Dividend potential: expected payout of RUB 4.04 per share implies a yield of 5.9%, close to the fair 7.0%.
— The portal's model shows 24% upside to fair value.
Attractiveness
Key figures, RUB bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 1.07 | 0.98 | -8.5% |
| EBITDA | -0.45 | -0.36 | — |
| Operating profit | -0.49 | -0.41 | — |
| Net profit | 0.31 | 0.09 | -72.0% |
| Operating cash flow | 0.91 | 0.56 | -38.9% |
| Capex | 0.00 | 0.17 | +4261.2% |
| EBITDA margin | -42.4% | -36.7% | +5.7 pp |
| Net margin | 28.8% | 8.8% | -20.0 pp |
Revenue for the half-year fell 8.5%, but operating cash flow over 12 months reached RUB 1.7 billion.
In the first half of 2026, IVA Technologies' revenue amounted to RUB 3,100.0 million, down 8.5% from the same period a year earlier. The decline in the top line reflects current market conditions, yet the company continues to generate substantial operating cash flow: over the last 12 months it reached RUB 1,700.0 million.
Positive cash flow amid falling revenue points to high business quality and the ability to collect payments from clients. This contrasts sharply with net profit, which declined more due to non-cash items.
Net profit dropped 72% on lower margins: net margin was 8.8% versus 28.8% a year earlier.
Net profit for the first half of 2026 declined by 72.0% year on year. Net margin fell to 8.8% from 28.8% in the same period last year.
Such a sharp drop in profitability could be due to higher costs or one-off expenses, but the reasons are not disclosed in the report. For an investor, it is important that operating cash flow remains high, which mitigates the negative impact of lower profit.
EBITDA margin declined to 36.7% from 42.4%, reflecting pressure on operating efficiency.
EBITDA margin for the first half of 2026 stood at 36.7% versus 42.4% a year earlier. The decline of 5.7 percentage points points to deteriorating operating efficiency, possibly due to higher cost of sales or investments in development.
Nevertheless, the margin level remains high for a software company, confirming the resilience of the business model. Combined with low leverage, this provides a safety cushion.
Leverage remains low: net debt of RUB 434.6 million is 0.24x EBITDA over the last 12 months.
As of the latest reporting date, IVA Technologies' net debt stood at RUB 434.6 million, equivalent to 0.24x EBITDA over the last 12 months. This level of debt poses no threat to financial stability.
Over the last 12 months, net debt increased by RUB 0.9 billion, but given high operating profitability, this does not look critical. The company retains the ability to service obligations and finance growth.
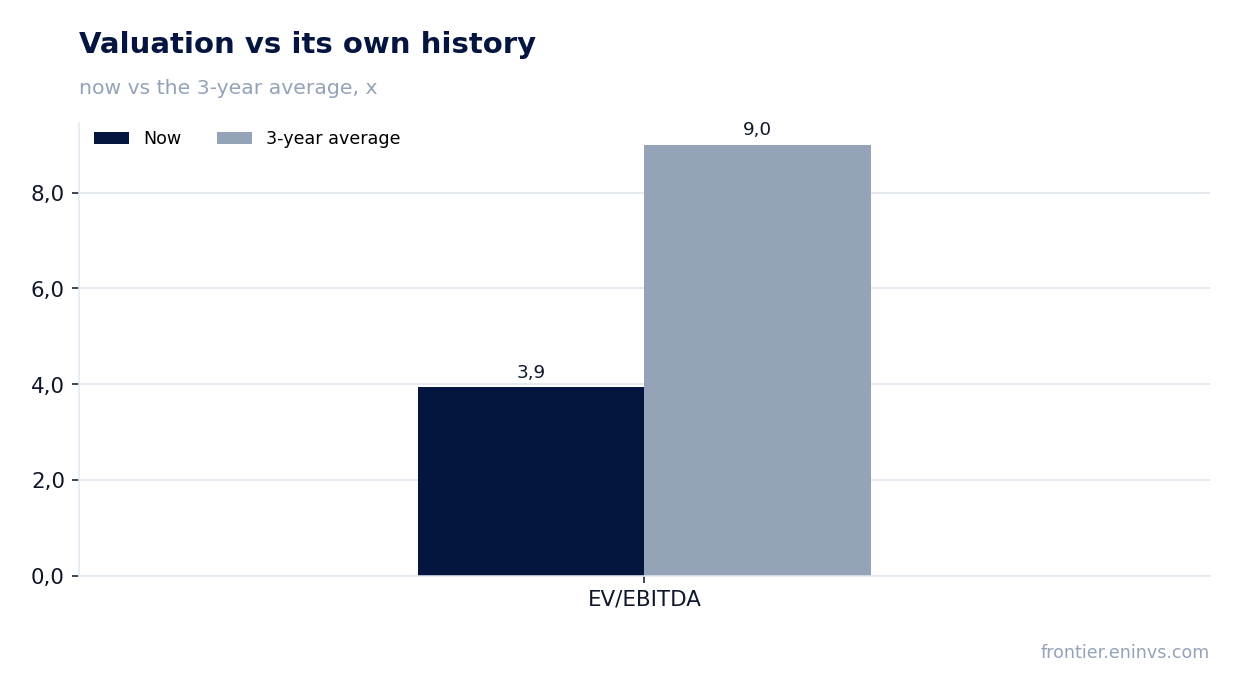
Shares trade at a discount to their own history: EV/EBITDA of 4.0x versus the three-year average of 9.0x.
The current EV/EBITDA multiple is 4.0x (based on EBITDA over the last 12 months), well below the three-year average of 9.0x. This indicates the shares are undervalued relative to their own history.
P/E over the last 12 months is 5.7x, which also looks attractive for a fast-growing software sector. The company's market capitalisation is RUB 6,875.0 million.
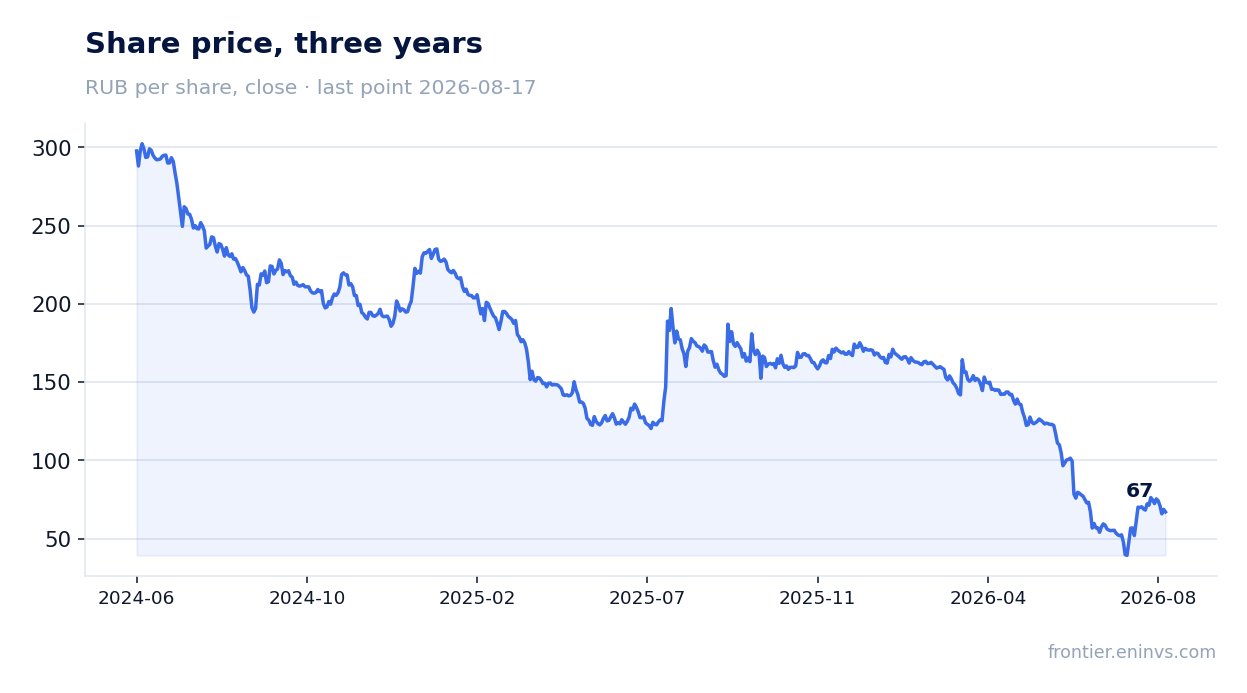
Dividend potential: expected payout of RUB 4.04 per share implies a yield of 5.9%, close to the fair 7.0%.
Over the last 12 months, the company paid no dividends. According to our model, the next expected dividend is RUB 4.04 per share, implying a forward yield of 5.9%.
The fair yield for this issuer is estimated at 7.0%, meaning the current share price implies a slight discount in dividend yield. The model's payout ratio is 0.34 of profit, leaving room for higher payouts.
The portal's model shows 24% upside to fair value.
Our fundamental value-creation model, based on EBITDA growth and a target multiple, shows the share has +24% upside to fair value. This calculation accounts for the current undervaluation relative to historical multiples.
The share is held in the 'Growth-potential (quality)' strategy on the portal, reflecting its compliance with our screening criteria. However, this is not a buy recommendation but a statement of fact.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 6.88 bn ₽ |
| P/E (LTM) | 5.7 |
| EV/EBITDA (LTM) | 4.0 |
| P/B | 1.35 |
| Net debt / EBITDA (LTM) | 0.24 |
| Operating cash flow (LTM) | 1.32 bn |
| ROE | 2.6% |
| EV/EBITDA, 3-year average | 9.0 |
Bottom line
In the first half of 2026 report, the weak spot was net profit, down 72% due to margin compression. However, operating cash flow of RUB 1.7 billion over 12 months shows the business continues to generate cash. Leverage is low, and multiples are well below the company's own three-year history, creating potential for valuation recovery. Dividend yield per our model is close to fair, and the portal's model indicates 24% upside. The key question for a holder is whether the company can halt the revenue decline and restore profitability to previous levels.
Open the company's financial profile IVAT →
See also: market overview · valuation map · stock screeners