KuybyshevAzot: H1 profit up nearly 1.6x on falling revenue – margin was carried by fertilizer prices, not volumes
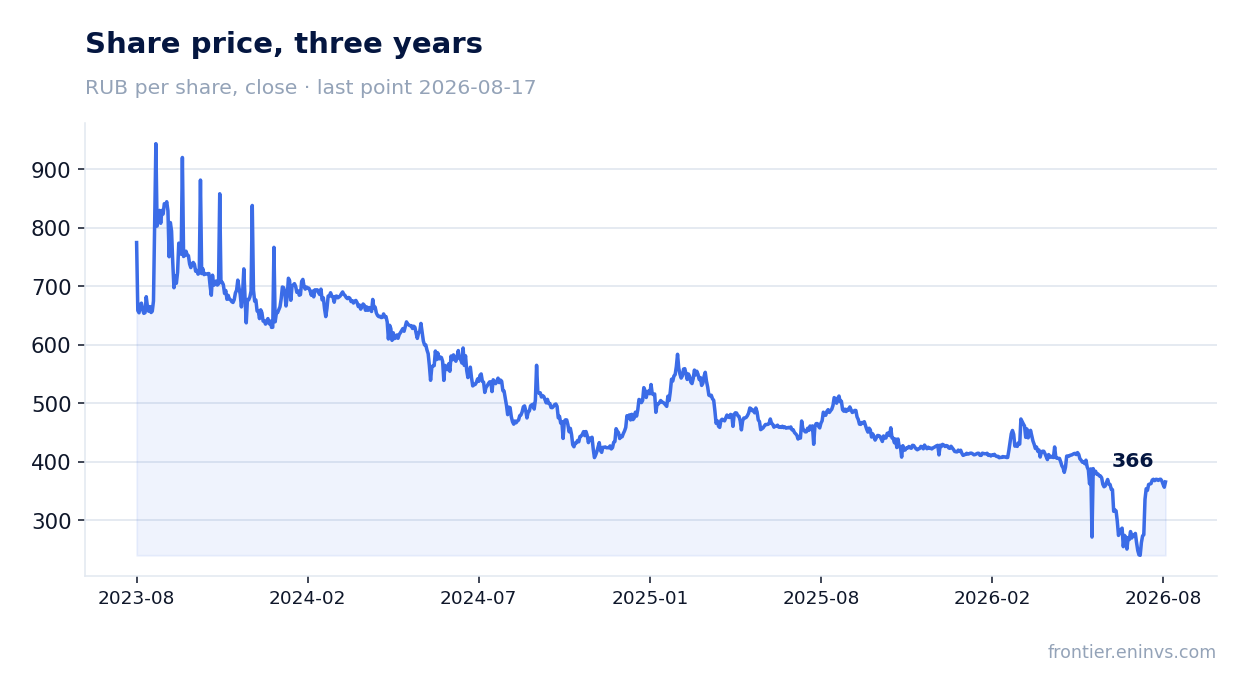
On 28 September we review KuybyshevAzot's H1 2026 report. Revenue fell 4.7% year-on-year to RUB 41,987 mn, but EBITDA rose 31.5% to RUB 11,385 mn and net profit jumped 59.6% to RUB 5,527 mn. The EBITDA margin climbed to 27.1% from 19.7% a year earlier, the company moved to a net cash position of RUB 5,525 mn, and the share fell 10.2% from the release to 28 September. With an EV/EBITDA of 2.77 versus a three-year average of 5.49 and a portal-model upside of +159%, the stock looks attractive, but the key question is the sustainability of pricing.
Key takeaways
— H1 2026 revenue fell 4.7% to RUB 41,987 mn, but EBITDA rose 31.5% to RUB 11,385 mn – margin was carried by fertilizer prices, not volumes
— The EBITDA margin climbed to 27.1% from 19.7% a year earlier, and the net margin to 13.2% from 7.9%, because costs grew slower than prices
— H1 net profit rose 59.6% to RUB 5,527 mn, and this is not a one-off: operating profit increased to RUB 6,324 mn
— The company moved to a net cash position: net debt at 30 June 2026 was minus RUB 5,525 mn versus RUB 6,300 mn at end-2025
— H1 operating cash flow was RUB 9,721 mn with capex of RUB 2,303 mn – free funds allow dividend payments
— No dividends were paid over the last 12 months, but our estimate for the current year is RUB 8.78 per share, a 2.6% yield on the current price
— EV/EBITDA LTM of 2.77 versus a three-year average of 5.49 – the stock trades below its own history, and the portal model implies +159% upside
Attractiveness
Key figures, RUB bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 44.1 | 42.0 | -4.7% |
| EBITDA | 8.66 | 11.4 | +31.5% |
| Operating profit | 3.60 | 6.32 | +75.7% |
| Net profit | 3.46 | 5.53 | +59.6% |
| Operating cash flow | 12.7 | 9.72 | -23.5% |
| Capex | 3.86 | 2.30 | -40.3% |
| EBITDA margin | 19.7% | 27.1% | +7.4 pp |
| Net margin | 7.9% | 13.2% | +5.3 pp |
H1 2026 revenue fell 4.7% to RUB 41,987 mn, but EBITDA rose 31.5% to RUB 11,385 mn – margin was carried by fertilizer prices, not volumes
KuybyshevAzot's H1 2026 revenue was RUB 41,987 mn, down 4.7% year-on-year. Falling revenue with rising profit means the company sold less or at lower prices in volume terms, but earned more per tonne.
EBITDA rose 31.5% to RUB 11,385 mn. This happened because costs grew slower than fertilizer prices. The report does not break down the factors, but the fact that EBITDA growth exceeded revenue growth indicates margin expansion.
Operating profit increased to RUB 6,324 mn, confirming that the improvement is not due to one-off items below the operating line. Net profit rose 59.6% to RUB 5,527 mn, the best result in recent years.
The EBITDA margin climbed to 27.1% from 19.7% a year earlier, and the net margin to 13.2% from 7.9%, because costs grew slower than prices
The EBITDA margin in H1 2026 was 27.1% versus 19.7% a year earlier. The 7.4 percentage point increase is the main positive surprise of the report.
The net margin also improved: 13.2% versus 7.9% a year earlier. This means the company not only cut unit costs but also managed other expenses and taxes efficiently.
Margin improvement on falling revenue is a classic sign of favorable pricing in the fertilizer market. If prices hold, the company can maintain high profitability even with weak volumes.
H1 net profit rose 59.6% to RUB 5,527 mn, and this is not a one-off: operating profit increased to RUB 6,324 mn
Net profit in H1 2026 reached RUB 5,527 mn, up 59.6% year-on-year. This growth is not the result of one-off write-offs or revaluations but of improved operations.
Operating profit rose to RUB 6,324 mn, confirming that the core business is earning more. The gap between operating and net profit is interest, taxes and other items, which did not offset the improvement.
Profit growth on falling revenue is a warning for volumes but positive for margins. The company now earns more per tonne sold, which matters amid volatile raw material prices.
The company moved to a net cash position: net debt at 30 June 2026 was minus RUB 5,525 mn versus RUB 6,300 mn at end-2025
As of 30 June 2026, KuybyshevAzot's net debt was minus RUB 5,525 mn, meaning cash exceeds debt. A year earlier, on 30 June 2025, net debt was RUB 5,800 mn, and at end-2025 it was RUB 6,300 mn.
The reduction in net debt over 12 months was RUB 11,300 mn, and since the start of the year RUB 11,800 mn. This was made possible by operating cash flow of RUB 9,721 mn with capex of only RUB 2,303 mn.
The net debt to LTM EBITDA ratio is minus 0.24 – the company has a net cash cushion. This gives freedom for dividends and investment without increasing debt.
H1 operating cash flow was RUB 9,721 mn with capex of RUB 2,303 mn – free funds allow dividend payments
Operating cash flow in H1 2026 was RUB 9,721 mn. Capital expenditures were modest at RUB 2,303 mn, less than a quarter of operating cash flow.
Free cash flow thus exceeds RUB 7,400 mn. These funds went to reduce debt and build a cash cushion, and in the future can be directed to dividends.
Low capex may mean the company has completed major investment projects or postponed them. In any case, the current capex level does not burden finances.
No dividends were paid over the last 12 months, but our estimate for the current year is RUB 8.78 per share, a 2.6% yield on the current price
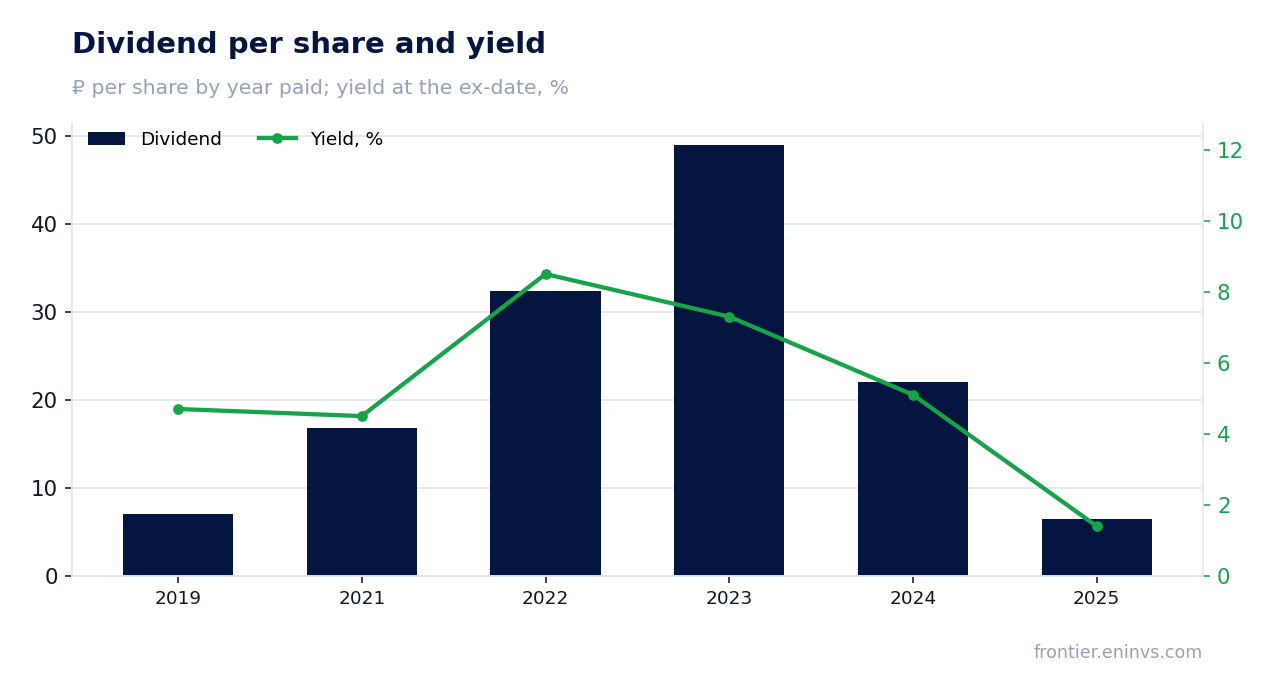
KuybyshevAzot paid no dividends over the last 12 months. The last payment was for 2025 – RUB 6.5 per share with a 1.4% yield at the ex-date. The payout history is unstable: RUB 49 for 2023, RUB 22 for 2024, RUB 6.5 for 2025.
Our estimate for the current financial year is RUB 8.78 per share, a 2.6% yield on the current price. This is our estimate, not a board decision. It assumes a payout ratio of 20% of LTM profit, as last year.
For comparison: the 2.6% yield is well below the central bank key rate of 14% and below the 10.5% yield we consider fair for this name. Even with potential profit growth, the dividend yield remains modest.
The dividend could be smaller if H2 profit falls due to lower fertilizer prices or if the company decides to allocate more funds to investment. The board's decision will be key.
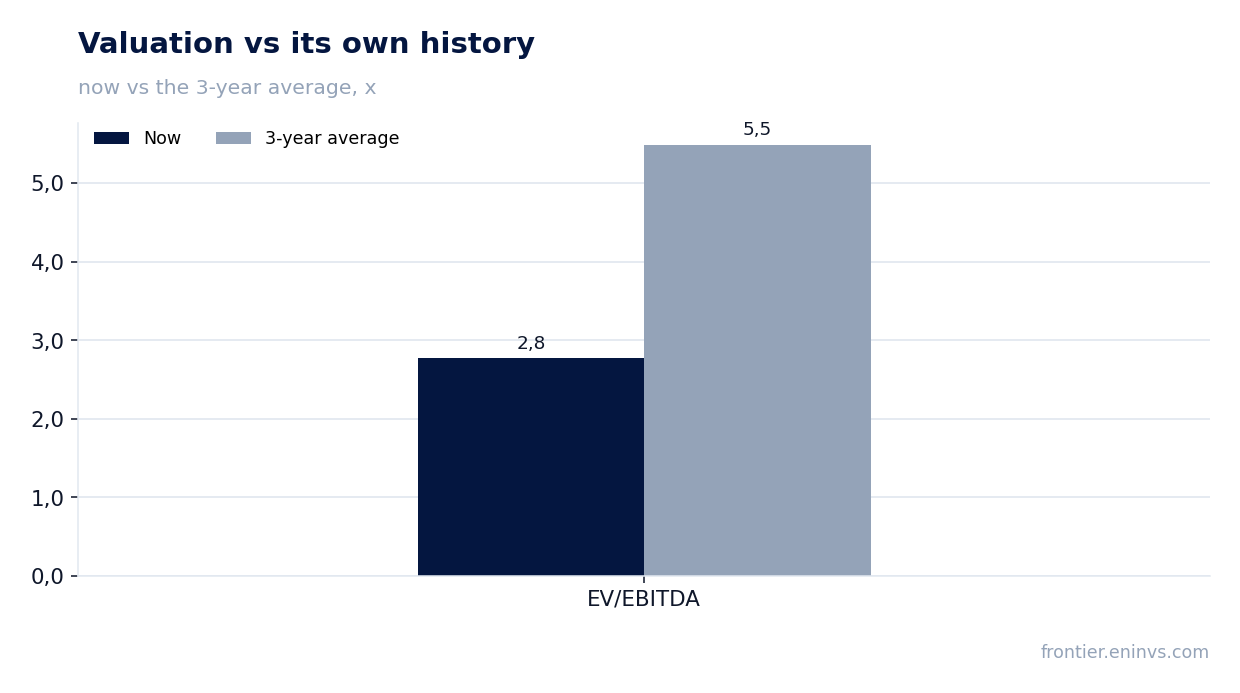
EV/EBITDA LTM of 2.77 versus a three-year average of 5.49 – the stock trades below its own history, and the portal model implies +159% upside
The EV/EBITDA LTM multiple is 2.77, nearly half the three-year average of 5.49. This indicates the market values the company significantly cheaper than in previous years.
P/E LTM is 7.56, which may also be an attractive level for a company with growing profit. Market capitalization is RUB 58,555 mn.
Our portal model, which re-prices EBITDA at current commodity prices at the target EV/EBITDA, implies a +159% upside to fair value. This is our own estimate, not a market consensus.
However, after the report the share fell 10.2% to 28 September, suggesting the market did not believe in the sustainability of high margins. Confirmation of the trend requires the H2 report.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 58.6 bn ₽ |
| P/E (LTM) | 7.6 |
| EV/EBITDA (LTM) | 2.8 |
| P/B | 0.59 |
| Net debt / EBITDA (LTM) | -0.24 |
| Operating cash flow (LTM) | 16.7 bn |
| ROE | 10.9% |
| EV/EBITDA, 3-year average | 5.5 |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2019 | 7.00 | 4.7% |
| 2021 | 16.85 | 4.5% |
| 2022 | 32.40 | 8.5% |
| 2023 | 49.00 | 7.3% |
| 2024 | 22.00 | 5.1% |
| 2025 | 6.50 | 1.4% |
| Our estimate, current year | 8.78 | 2.6% on the current price |
Bottom line
KuybyshevAzot delivered strong profit and margin growth in H1 2026 despite falling revenue. The company moved to a net cash position, and the EV/EBITDA multiple fell to 2.77 versus a three-year average of 5.49. However, the dividend yield remains low, and the sustainability of fertilizer prices is uncertain. At the current price, the stock looks attractive for investors willing to accept commodity market volatility.
Open the company's financial profile KAZT →
See also: market overview · valuation map · stock screeners