Europlan: profit up 4.9x, but the leasing portfolio shrank by 17%
On 20 August, Europlan (PJSC Leasing Company Europlan) released its condensed interim consolidated financial statements for the three and six months ended 30 June 2026. Net profit in the second quarter reached RUB 2,473.2 mn, 4.9 times higher than a year earlier, while net interest income fell 29.6% to RUB 3,937.0 mn. The sharp divergence is explained by the fact that a year ago the company charged RUB 5,060.8 mn to expected credit loss provisions on leasing assets, versus only RUB 276.1 mn this quarter. Net investments in leasing over the half-year declined from RUB 169.9 bn to RUB 141.3 bn, reflecting the business contraction amid the high key rate. At the current price of RUB 671 and trailing twelve-month profit of RUB 7,567.7 mn, the stock trades at a P/E of 10.6 with an ROE of 21.0%, and our portal model implies about 11% upside. With an expected dividend of RUB 32.57 per share, the forward yield is 4.9% – half the 10.5% yield we consider fair. The share looks rather attractive for an investor willing to wait for a rate reversal and portfolio recovery, but not for one seeking a high current dividend.
Key takeaways
— Profit rose 4.9x not because of the business but because of provisions: a year ago charges were RUB 5,060.8 mn, now RUB 276.1 mn
— Net interest income has been falling for four consecutive quarters, and in Q2 the decline accelerated to 29.6%
— The leasing portfolio shrank 17% since the start of the year to RUB 141.3 bn, the main risk to future income
— Trailing twelve-month profit of RUB 7,567.7 mn at ROE 21.0% and P/E 10.6 – valuation does not look stretched
— The expected dividend of RUB 32.57 per share yields only 4.9% – half the 10.5% we consider fair
— Our valuation model implies about 11% upside to fair value, but it hinges on portfolio recovery
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Net interest income | 5.60 | 3.94 | -29.6% |
| Net profit | 0.50 | 2.47 | +392.5% |
| Capex | 0.04 | 0.07 | +100.9% |
| Net margin | 9.0% | 62.8% | +53.8 pp |
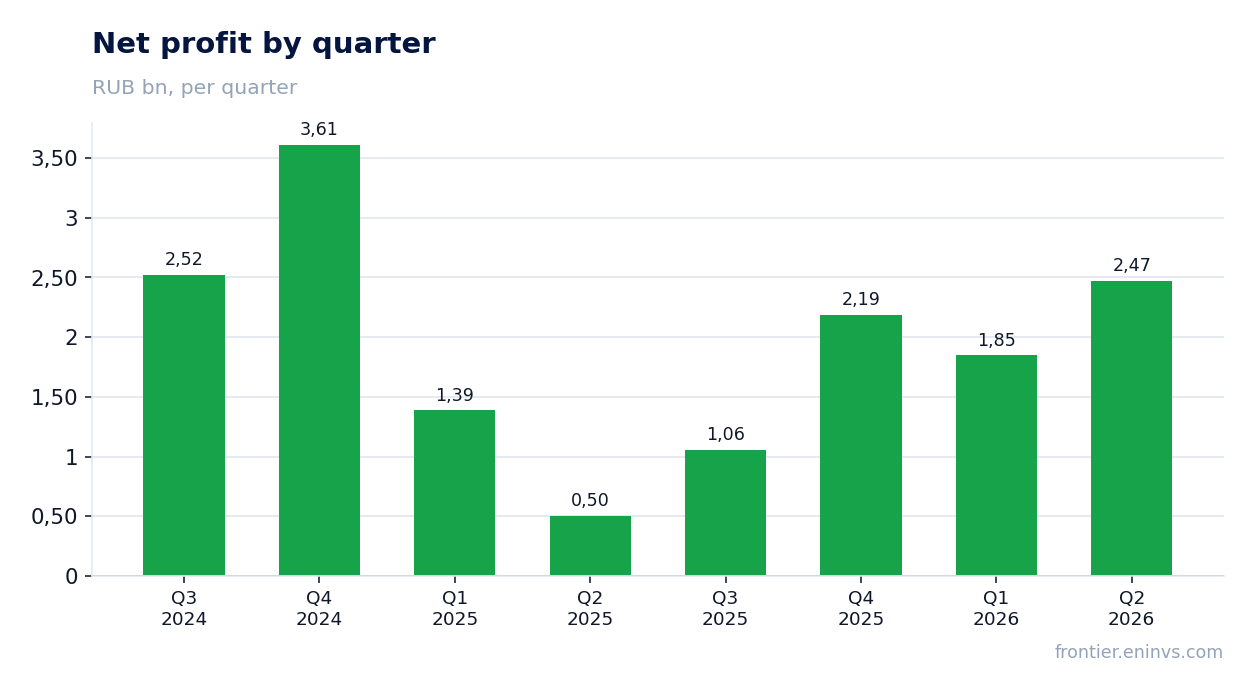
Profit rose 4.9x not because of the business but because of provisions: a year ago charges were RUB 5,060.8 mn, now RUB 276.1 mn
Net profit in the second quarter of 2026 reached RUB 2,473.2 mn versus RUB 502.2 mn a year earlier. Such a 4.9x increase looks impressive, but it is almost entirely explained by the change in provisions. The income statement shows that the change in expected credit loss provisions on leasing assets in Q2 was RUB 276.1 mn, while a year earlier it was RUB 5,060.8 mn. The difference of RUB 4.8 bn is almost equal to the increase in pre-tax profit.
Excluding this effect, pre-tax profit in Q2 would have been about RUB 3.3 bn, which is 4.9 times higher than last year's RUB 0.7 bn solely due to provisions. Without them, pre-tax profit would have declined because operating income fell. This means the quality of profit this quarter is low – it reflects not an improvement in the business but merely the absence of large charges that a year ago were caused by deteriorating portfolio quality.
For the first half of 2026, net profit was RUB 4,322.3 mn versus RUB 1,888.1 mn a year earlier. Here the provision effect is even more pronounced: over six months, charges to provisions for leasing assets were RUB 1,420.4 mn versus RUB 10,130.3 mn a year earlier. The difference of RUB 8.7 bn is the main source of profit growth for the half-year.
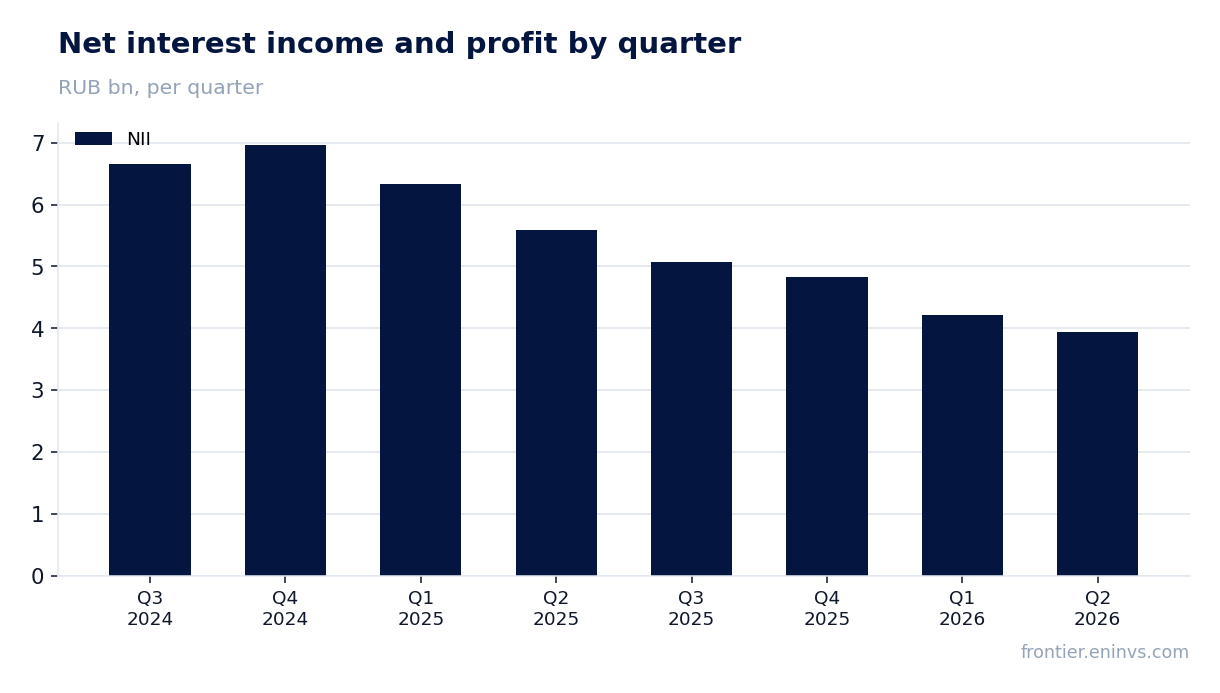
Net interest income has been falling for four consecutive quarters, and in Q2 the decline accelerated to 29.6%
Net interest income in the second quarter of 2026 was RUB 3,937.0 mn, 29.6% less than in Q2 2025. This is the fourth consecutive quarterly decline: in Q1 2026 the drop was 33.5%, in Q4 2025 – 30.7%, in Q3 2025 – 23.8%. In Q2 the rate of decline slowed slightly compared to Q1, but remains very high.
The reason for the fall is the contraction of the leasing portfolio. Net investments in leasing, financial assets at amortised cost and lease receivables as of 30 June 2026 amounted to RUB 141,270.1 mn versus RUB 169,928.7 mn at the end of 2025. A 16.9% reduction over six months directly reduces the base for interest income accrual. The report also states that the high key rate of the Central Bank of Russia limited access to financing for small and medium-sized businesses and hindered the recovery of business activity, which led to a decline in the Group's leasing portfolio.
Interest income for the half-year fell to RUB 19,681.3 mn from RUB 30,170.0 mn a year earlier, i.e. by 34.8%. Interest expenses declined to RUB 11,533.3 mn from RUB 18,243.7 mn. The reduction in expenses partially offsets the fall in income but not fully. Net interest income for the half-year was RUB 8,148.0 mn versus RUB 11,926.3 mn a year earlier.
The leasing portfolio shrank 17% since the start of the year to RUB 141.3 bn, the main risk to future income
Net investments in leasing as of 30 June 2026 amounted to RUB 141,270.1 mn, down 16.9% from RUB 169,928.7 mn as of 31 December 2025. This is the company's key asset, and its contraction means future interest income will be lower. The portfolio is shrinking against the backdrop of high rates: the company is not growing new leasing deals fast enough to offset repayments of old ones.
The report states that the Group expects deferred demand for leasing services to materialise as the key rate of the Central Bank of Russia declines. This means management views the current contraction as temporary. However, while the rate remains at 14.0%, a portfolio recovery is unlikely. In addition, the number of offices decreased from 92 at the end of 2025 to 90 as of 30 June 2026, while the number of employees rose from 2,958 to 3,138, which may indicate network optimisation while maintaining operational efficiency.
The portfolio contraction is not only a loss of income but also a potential source of risk. If the company is forced to sell assets or tighten terms, this could lead to additional provisions. In the first half of 2026, charges to provisions for leasing assets already amounted to RUB 1,420.4 mn, significantly less than last year's RUB 10,130.3 mn, but still substantial.
Trailing twelve-month profit of RUB 7,567.7 mn at ROE 21.0% and P/E 10.6 – valuation does not look stretched
Trailing twelve-month profit was RUB 7,567.7 mn, and net interest income for the same period was RUB 18,000.0 mn. With a market capitalisation of RUB 80,496.0 mn, the price-to-earnings ratio (P/E) is 10.6. Return on equity (ROE) is 21.0%. For a company currently undergoing portfolio contraction, these figures look fairly solid.
Comparing the current P/E with its own three-year history is not possible due to the absence of data in the FACTS. However, it can be noted that with ROE of 21.0% and P/E of 10.6, the implied price-to-book ratio (P/B) is about 2.2. This means the market values the company's equity at roughly 2.2 times its book value, which for a leasing company with ROE of 21.0% is not excessive.
Our valuation model, which compares return on equity with price-to-book, implies about 11% upside to fair value. This is our own estimate, not a market consensus. It assumes that the current level of profit is sustainable and that the portfolio will not continue to shrink at the same pace.
The expected dividend of RUB 32.57 per share yields only 4.9% – half the 10.5% we consider fair
Over the last 12 months, the company paid no dividends – the FACTS state that RUB 0.0 per share was paid. This is because dividends were already paid in 2025: according to the history, for the 2025 calendar year RUB 29.0 per share was paid at an ex-date price of RUB 643.7, giving a yield of 4.5%. In 2024, the payout was RUB 77.0 per share with a yield of 13.2%.
Our model estimates the next dividend at RUB 32.57 per share. At the current price of RUB 671.0, this gives a forward yield of 4.9%. This is significantly below the yield we consider fair for this stock – 10.5%. The implied payout ratio is 0.7 of profit, meaning the company directs about 70% of net profit to dividends. With the key rate at 14.0%, a yield of 4.9% looks uncompetitive compared to risk-free instruments.
The dividend could be smaller if profit declines due to further portfolio contraction or rising provisions. In addition, the company may prefer to direct funds to maintain capital or new investments. In 2025, the dividend was already reduced compared to 2024 – from RUB 77.0 to RUB 29.0 per share, showing that payouts are not steadily growing.
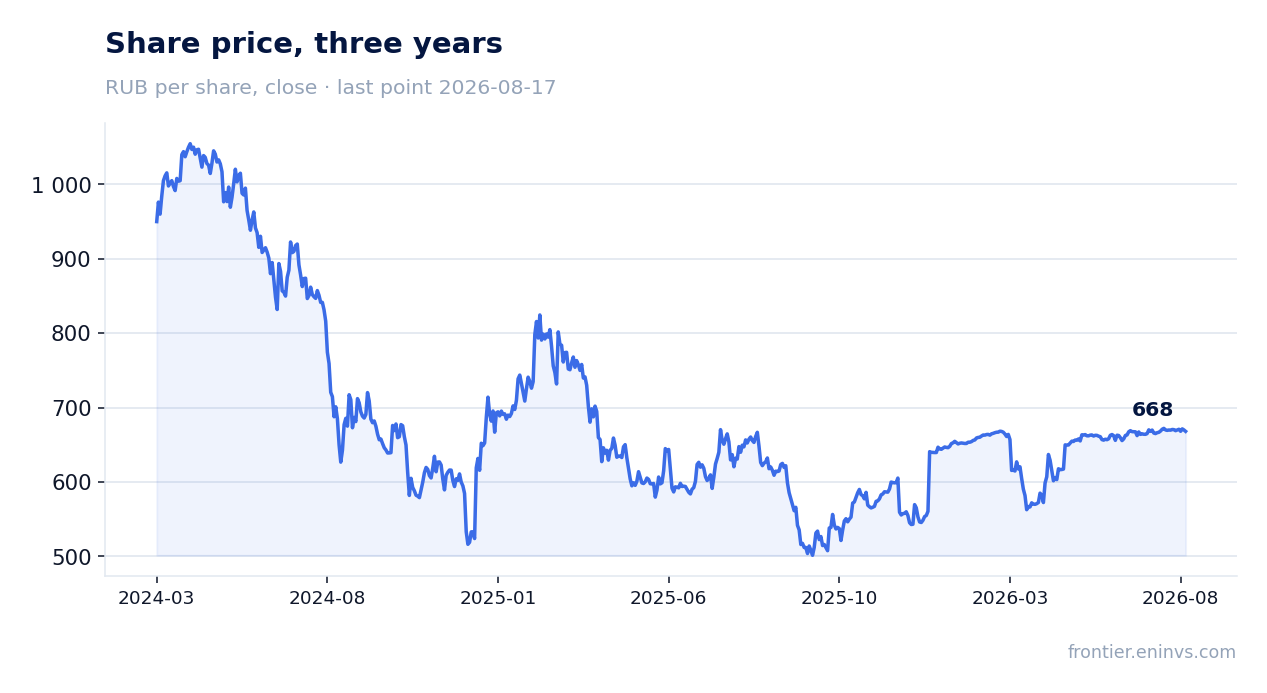
Our valuation model implies about 11% upside to fair value, but it hinges on portfolio recovery
Our valuation model, based on comparing return on equity with price-to-book, implies about 11% upside to fair value. This is our own estimate, not a market consensus. It assumes that the current level of profit (RUB 7,567.7 mn over the last 12 months) is sustainable and that the company will not face new large provision charges.
However, this upside looks modest compared to the risks. The leasing portfolio is shrinking, net interest income has been falling for four consecutive quarters, and the dividend yield of 4.9% is significantly below the 10.5% we consider fair. If the portfolio continues to contract, profit may decline, and the current valuation will not look as attractive.
The key factor for realising the upside is a reduction in the key rate. The report states that the company expects deferred demand for leasing services to materialise as the rate declines. If the rate starts to fall, the portfolio could recover, leading to higher interest income and profit. In that case, the current price may prove attractive. If the rate remains high, the company will continue to lose portfolio, and profit may decline.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 80.5 bn ₽ |
| P/E (LTM) | 10.6 |
| P/B | 1.90 |
| ROE | 21.0% |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2024 | 77.00 | 13.2% |
| 2025 | 29.00 | 4.5% |
Bottom line
The strong point of the report is the sharp improvement in profit – RUB 2,473.2 mn in Q2 versus RUB 502.2 mn a year earlier, mainly due to the absence of large provision charges. However, this is a one-off effect: a year ago provisions were RUB 5,060.8 mn, now RUB 276.1 mn. The underlying business is contracting: the leasing portfolio fell 16.9% since the start of the year, and net interest income has been declining for four consecutive quarters. Valuation does not look stretched – P/E 10.6 with ROE 21.0%, and our model implies about 11% upside. But the dividend yield of 4.9% is significantly below the 10.5% we consider fair, which limits the stock's appeal for income-oriented investors. The question for a holder now is when the key rate will start to decline and whether demand for leasing will return. Until then, profit may remain volatile and the portfolio may continue to shrink.
Open the company's financial profile LEAS →
See also: market overview · valuation map · stock screeners