Lenta 3Q 2026: revenue +34% on acquisitions, EBITDA margin 6.1%, full-year targets in doubt
Lenta is Russia's fourth-largest food retailer by revenue: Lenta and Giper Lenta hypermarkets, Super Lenta supermarkets, Monetka convenience stores, Ulybka Radugi drogerie stores and, since this year, the acquired O'Key hypermarkets, Remi and Dom Lenta (formerly OBI Russia). On 30 October 2026 the company published operating and financial results for 3Q and 9M 2026. The share trades at RUB 1,866 (Moscow Exchange, 30.10.2026, 12:18 Moscow time, +2.4% from the previous close), market capitalisation is RUB 216 bn on 116.0 mn shares.
Verdict: neutral. Like-for-like sales accelerated to +8.1%, and EBITDA grew at a double-digit rate for the first time this year, +12.5%. But the margin fell to 6.1%, net income dropped 30%, and management wrote for the first time that full-year 2026 results may deviate from the strategy targets (EBITDA margin of at least 7%). At 3.9x annual EBITDA the share trades above its own median and above X5. Our weighted value of RUB 2,324 at end-2027 (+25% over 14 months) is close to the return an equity investor should require with the key rate at 14%.
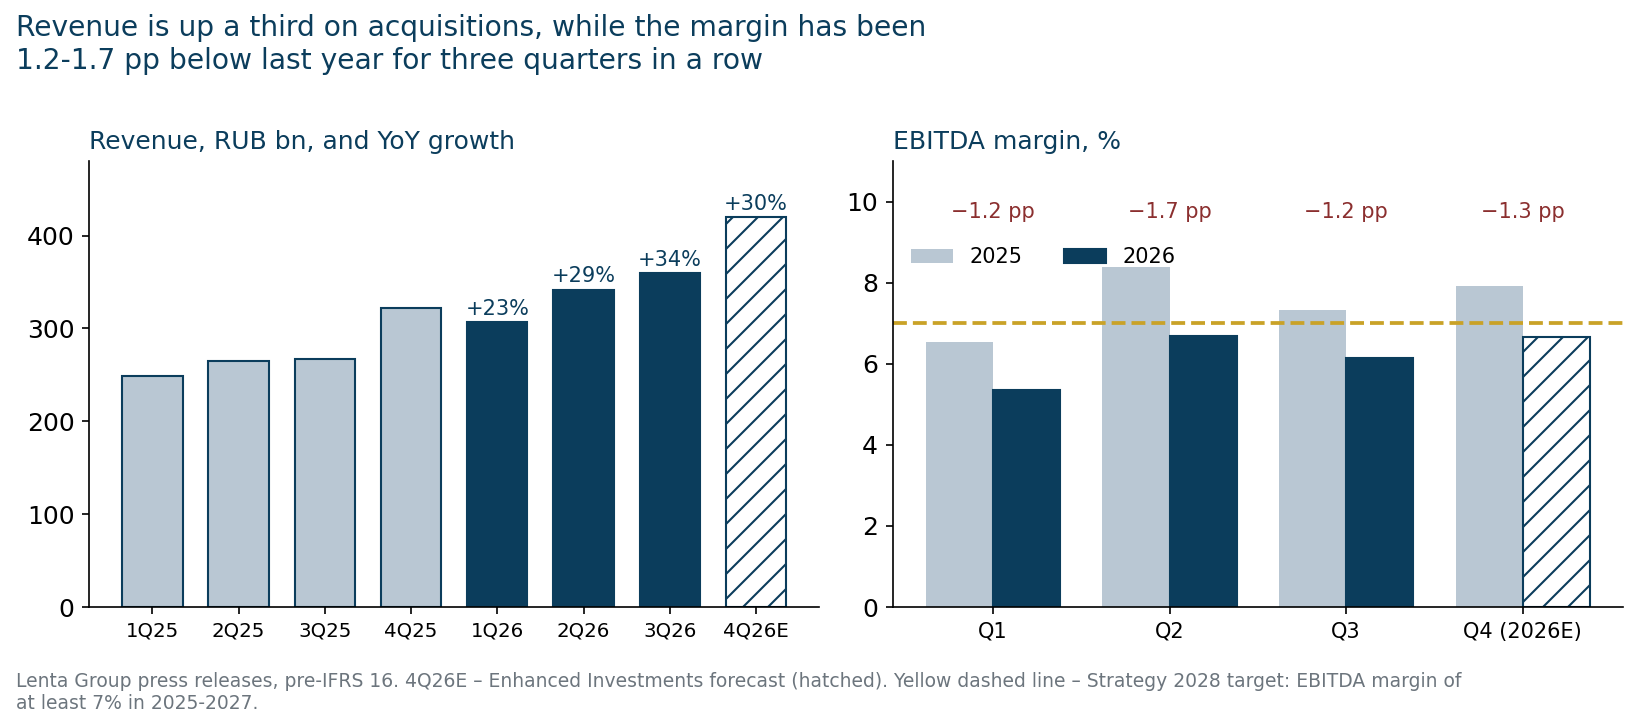
- Revenue RUB 359.3 bn, +34.3% YoY: acquired chains delivered about half of the increase, organic growth was about 16% (authors' calculation).
- Like-for-like (LFL) sales +8.1% after +6.5% in 2Q, traffic +4.2% across all formats, supermarkets +17.3%.
- EBITDA RUB 22.1 bn (+12.5%), margin 6.1% vs 7.3% a year ago: we estimate the new assets are running at about breakeven, plus pricing in small formats and rent.
- Net income RUB 5.7 bn (-29.8%): net interest expense grew 2.8 times to RUB 5.1 bn.
- Net debt RUB 124.3 bn, 1.4x EBITDA; free cash flow for the quarter was -RUB 4.8 bn.
- The target of at least 7% margin for 2026 requires 9.2% in 4Q. We expect 6.7%, and 6.3% for the year.
Revenue up a third, but about half of the increase came from acquired chains
All figures below are pre-IFRS 16, the basis on which Lenta sets its targets and compares itself. Under IFRS 16 store leases are treated as debt and lease payments leave operating expenses, so EBITDA is higher and debt is larger. For retailers we use the pre-IFRS 16 basis: rent stays in expenses, and EBITDA is after rent. IFRS 16 figures are given for reference.
| Metric, RUB bn | 3Q 2026 | 3Q 2025 | Change | 9M 2026 | Change |
|---|---|---|---|---|---|
| Revenue | 359.3 | 267.5 | +34.3% | 1,007.8 | +29.0% |
| Gross profit | 79.8 | 61.3 | +30.1% | 224.9 | +26.6% |
| Gross margin | 22.2% | 22.9% | -0.7 pp | 22.3% | -0.4 pp |
| EBITDA | 22.1 | 19.6 | +12.5% | 61.3 | +5.5% |
| EBITDA margin | 6.1% | 7.3% | -1.2 pp | 6.1% | -1.4 pp |
| Operating profit | 12.9 | 12.9 | -0.3% | 36.3 | -5.4% |
| Net interest expense | 5.1 | 1.8 | +179% | 10.2 | +76% |
| Net income | 5.7 | 8.2 | -29.8% | 18.7 | -21.9% |
| IFRS 16 net income, for reference | 5.1 | 7.1 | -27.5% | 15.8 | -26.2% |
The company's EBITDA matches our formula "operating profit plus depreciation and amortisation" up to impairment: 12.9 + 9.0 = RUB 21.9 bn vs RUB 22.1 bn reported, the difference is RUB 0.16 bn of impairment loss. So we use the company's figure.
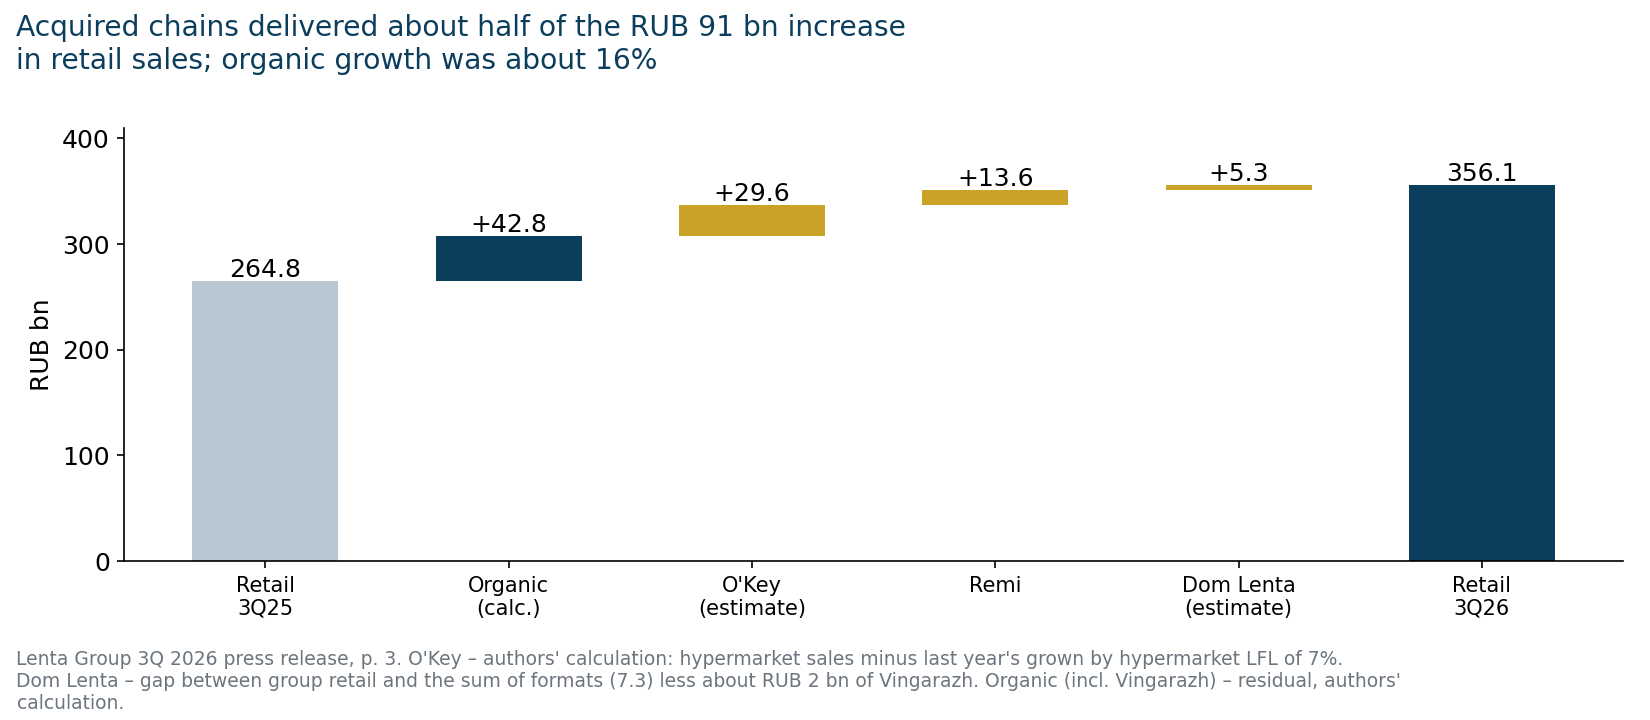
Retail sales grew by RUB 91.3 bn to RUB 356.1 bn. The company does not disclose how much each new chain contributed, except Remi (RUB 13.6 bn). We estimated the rest ourselves:
- O'Key (75 hypermarkets, in the group since 2 June): hypermarket sales rose by RUB 39.2 bn to RUB 175.6 bn. If hypermarkets without O'Key had grown at their LFL of 7.0%, that would be RUB 146.0 bn, leaving RUB 29.6 bn for O'Key (authors' calculation).
- Dom Lenta: the sum of the five formats in the company's table is RUB 7.3 bn below group retail. The gap includes Dom Lenta and Vingarazh, which the company says made "almost RUB 2 bn" in the quarter. That leaves RUB 5.3 bn for Dom Lenta (authors' calculation).
- Organic: 91.3 - 29.6 - 13.6 - 5.3 = RUB 42.8 bn, or +16% year on year (authors' calculation). This is LFL of +8.1% plus growth in the company's own selling space.
The acquired chains show in the ticket: the average hypermarket ticket fell 8.1% to RUB 1,410, while the number of tickets grew 40%. O'Key shoppers buy smaller baskets than in Lenta hypermarkets.
Organic growth accelerated: LFL +8.1%, traffic is growing in every format
Like-for-like sales (revenue of stores open for more than a year, excluding acquired chains and VAT) grew 8.1% after 6.5% in 2Q. Traffic contributed +4.2%, the average ticket +3.8%. Including VAT, whose rate was raised to 22% from 1 January, growth was 9.2%.
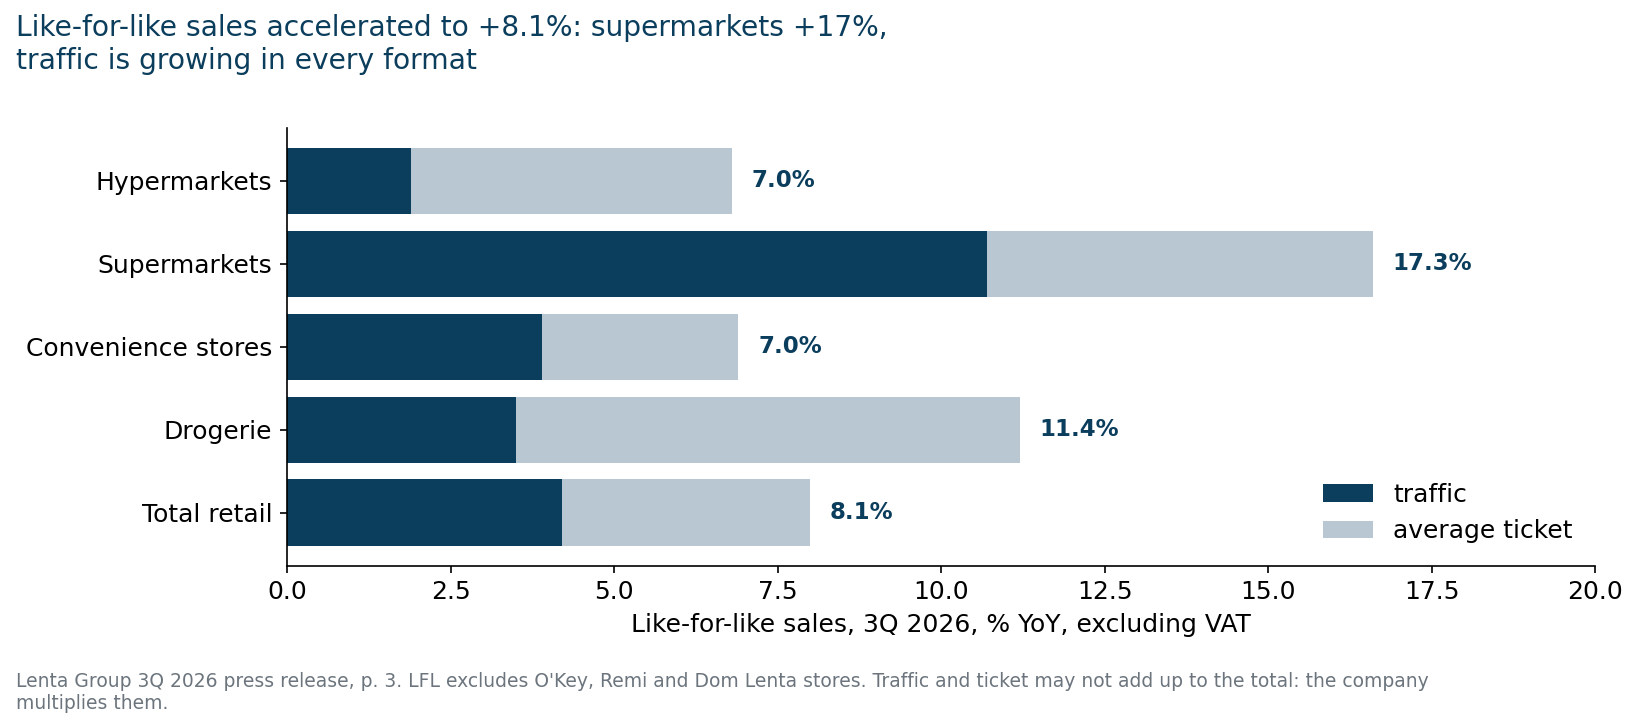
- Supermarkets were the best format: LFL +17.3%, traffic +10.7%, revenue +24.8% to RUB 35.5 bn. The chain passed 400 stores.
- Hypermarkets: LFL +7.0% with traffic +1.9%. According to the company, 31 O'Key stores had been rebranded as Giper Lenta by 30 September, and most of the rest will be converted by the end of November. Management says the first refurbished hypermarkets show positive dynamics but gives no numbers.
- Convenience stores (Monetka): LFL +7.0%, traffic +3.9%, revenue +25.4% to RUB 109.5 bn. Openings slowed: net additions of 214 stores in the quarter vs 301 a year ago, and 682 vs 807 over 9M. The company attributes this to more careful site selection. In the strategy presented in November 2025, Lenta planned to open more than 1,000 Monetka stores a year.
- Drogerie (Ulybka Radugi): LFL +11.4%, revenue +19.9% to RUB 14.7 bn. The 2026 opening plan was cut to 200 stores, and the chain shrank by 10 stores in 3Q.
Online is lagging: revenue grew 6.7% to RUB 18.0 bn. Own services added 21% to RUB 13.8 bn (77% of online), while sales through partners fell 23%. In 2Q management attributed the decline in the partner channel to the removal of apps from digital stores.
Margin: down 1.2 pp – new assets near breakeven, pricing and rent
The EBITDA margin fell 1.19 pp to 6.1%. The line items show where the decline came from:
- Gross margin -0.73 pp to 22.2%. The company explains this by adapting prices in small formats to demand. In 2Q the decline was 2.4 times smaller, -0.30 pp.
- Rent +0.44 pp to 3.5% of revenue. The share of owned space fell from 38% to 33%: most Monetka, O'Key, Remi and Dom Lenta stores are leased. The margin before rent (EBITDAR) fell less, by 0.75 pp to 9.7%.
- Staff +0.11 pp, utilities +0.15 pp, store operating costs +0.22 pp. Advertising and other costs, by contrast, saved 0.24 pp.
The company names the consolidation of new assets as the main reason. We test this with a calculation. Had the organic business (RUB 307 bn of retail) kept last year's 7.3%, it would have produced RUB 22.6 bn of EBITDA. The group made only RUB 22.1 bn. So RUB 48 bn of sales from acquired chains brought EBITDA of about zero (authors' calculation). This is an upper-bound estimate of the drag from new chains: the organic business also lost gross margin on small-format pricing. That is also where the upside lies: if the O'Key integration finishes in November and the acquired chains reach even a 3-4% margin, this would add RUB 1.5-2 bn of EBITDA per quarter (authors' assumption).
The trend within the year is more encouraging than the 9M report. EBITDA year on year: +0.7% in 1Q, +2.9% in 2Q, +12.5% in 3Q. The margin decline narrowed from 1.69 pp in 2Q to 1.19 pp.
Interest ate the profit: RUB 5.1 bn in the quarter vs RUB 1.8 bn a year ago
Operating profit was flat year on year at RUB 12.9 bn. Net income fell 29.8% because of interest. Net interest expense grew 2.8 times in a year: RUB 1.8 bn in 3Q 2025, RUB 1.8 bn in 1Q 2026, RUB 3.3 bn in 2Q and RUB 5.1 bn in 3Q.
The cause is the debt taken on for the O'Key deal. Gross debt rose from RUB 99.9 bn at the start of the year to RUB 143.4 bn. The weighted average rate over 12 months was 13.8%, and most loans carry fixed rates. Annualised, 3Q interest amounts to RUB 20 bn, or 23% of 12-month EBITDA. EBITDA interest cover fell from 10.7x to 4.3x (authors' calculation). The company said it refinanced most of the O'Key loans in 3Q at Lenta's lower rates. The savings were not disclosed.
Cash: working capital absorbed RUB 5.2 bn, free cash flow -RUB 4.8 bn
| Cash flow, RUB bn | 3Q 2026 | 3Q 2025 | 9M 2026 | 9M 2025 |
|---|---|---|---|---|
| EBITDA | 22.1 | 19.6 | 61.3 | 58.1 |
| Operating cash flow before working capital | 22.0 | 19.4 | 61.2 | 57.8 |
| Change in working capital | -5.2 | -0.9 | -24.3 | -11.4 |
| Interest and tax paid | -6.4 | -5.3 | -14.0 | -12.2 |
| Operating cash flow | 10.3 | 13.2 | 22.8 | 34.2 |
| Investing (incl. chain acquisitions) | -15.1 | -15.6 | -53.6 | -42.7 |
We calculated operating cash flow before working capital as pre-tax profit plus adjustments (7.7 + 14.3 = RUB 22.0 bn). It is almost equal to EBITDA, so there is no gap between profit and cash at this level. The cash went into working capital: RUB 5.2 bn in the quarter and RUB 24.3 bn over 9M, twice as much as a year earlier. The company refers to "investments in working capital" but the release has no balance sheet with inventories and payables. Whether O'Key's payables are shrinking after supplier terms changed, or inventories are growing, can only be checked in the IFRS statements.
Capex rose to RUB 15.0 bn from RUB 12.0 bn a year ago (4.2% of revenue against the strategy ceiling of 5.5%). Free cash flow as calculated by the company (operating cash flow minus capex) was -RUB 4.8 bn. Net debt rose by RUB 6.8 bn in the quarter. The difference of about RUB 2 bn consists of other financing payments, which the company does not break down.
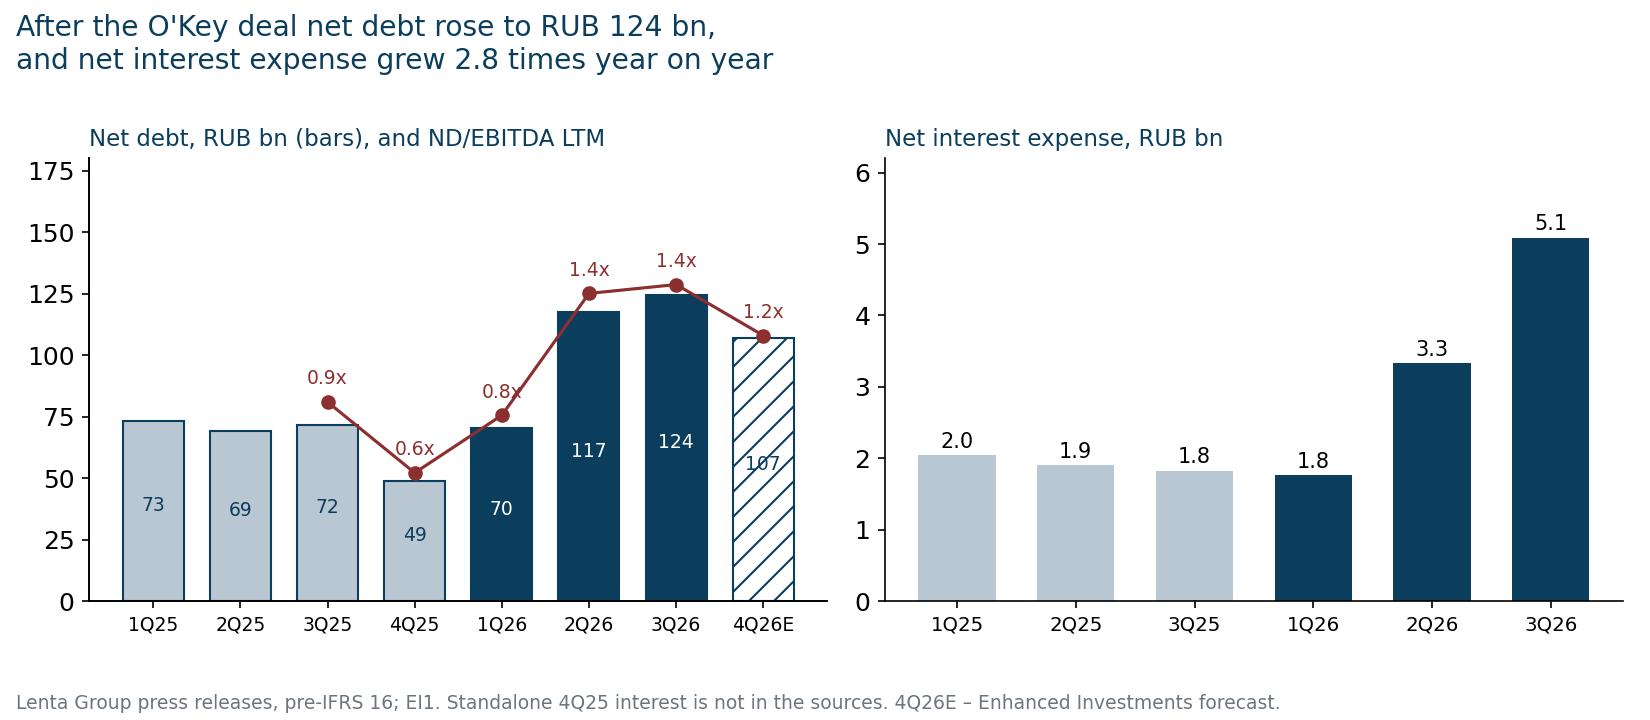
Net debt as of 30 September was RUB 124.3 bn, 1.4x 12-month EBITDA. The company calls this its target range. Under the strategy the normal level is 1.5x, with up to 2.0x allowed for M&A. Including leases (IFRS 16), net debt is RUB 289.2 bn, lease liabilities grew from RUB 119.5 bn to RUB 164.9 bn over 9M, and leverage is 2.3x IFRS 16 EBITDA (authors' calculation). Cash on accounts fell from RUB 25.2 bn to RUB 19.1 bn in the quarter.
4Q is seasonally strong for retailers' cash flow: in 4Q 2025 Lenta's net debt fell by RUB 22.7 bn. We assume a decline of RUB 17 bn to RUB 107 bn, and leverage of 1.2x at year-end (authors' forecast).
The target of at least 7% for 2026 is nearly out of reach, and the company has for the first time allowed for a deviation
In November 2025 Lenta presented its strategy to 2028: revenue of RUB 2.2 trn in 2028, EBITDA margin of at least 7% in 2025-2027 and about 8% in 2028, net debt up to 1.5x EBITDA (up to 2.0x for acquisitions), capex excluding acquisitions no higher than 5.5% of revenue. The strategy allows dividends once leverage falls (Retail.ru and Financial One, 27.11.2025).
The 9M margin was 6.1%. To reach 7% for the year, given our 4Q revenue estimate of RUB 420 bn, 4Q EBITDA would need to be RUB 38.6 bn, or 9.2% of revenue. Lenta's best quarter by margin over the past two years was 2Q 2025, before the acquisitions: 8.4% (authors' calculation).
Management sees this. In 2Q the CEO wrote that he was confident of reaching the strategy goals. In 3Q the wording changed: full-year 2026 results may deviate from the strategy targets, but the strategic goals are not being revised, and the company considers the impact of the new assets temporary. The release contains no quantitative guidance for 2026.
Our 4Q forecast: revenue RUB 420 bn (+30%), EBITDA RUB 28 bn (+10%), margin 6.7% vs 7.9% a year ago. That gives RUB 1,428 bn of revenue and RUB 89.3 bn of EBITDA for the year, a 6.3% margin (authors' forecast). Revenue of RUB 2.2 trn by 2028 would require another +24% a year in 2027-2028. That is unlikely without new acquisitions: organic growth is currently about 16%.
Valuation: 3.9x annual EBITDA – above its own history and above X5
Enterprise value (EV) is market cap plus net debt: 216.4 + 124.3 = RUB 340.7 bn. 12-month EBITDA (4Q 2025 plus 9M 2026) is 25.5 + 61.3 = RUB 86.9 bn.
| Multiple | Lenta | X5 (29.10.2026) |
|---|---|---|
| EV/EBITDA LTM, pre-IFRS 16 | 3.9x | 3.1x |
| EV/EBITDA 2026E | 3.6x | – |
| EV/EBITDA 2027E (base case) | 3.0x | 2.8x |
| P/E LTM, IFRS | 8.7x | 7.1x |
| EBITDA margin 3Q 2026 | 6.1% | 6.6% |
| LFL 3Q 2026 | +8.1% | +7.4% |
| Dividend yield, next 12 months | 0 | about 12.6% |
P/E is based on IFRS net income for 4Q 2025 and 9M 2026: 9.2 + 15.8 = RUB 25.0 bn. X5 figures come from our review of 29.10.2026, same basis. The companies calculate LFL differently (Lenta excludes VAT), so the comparison is indicative.
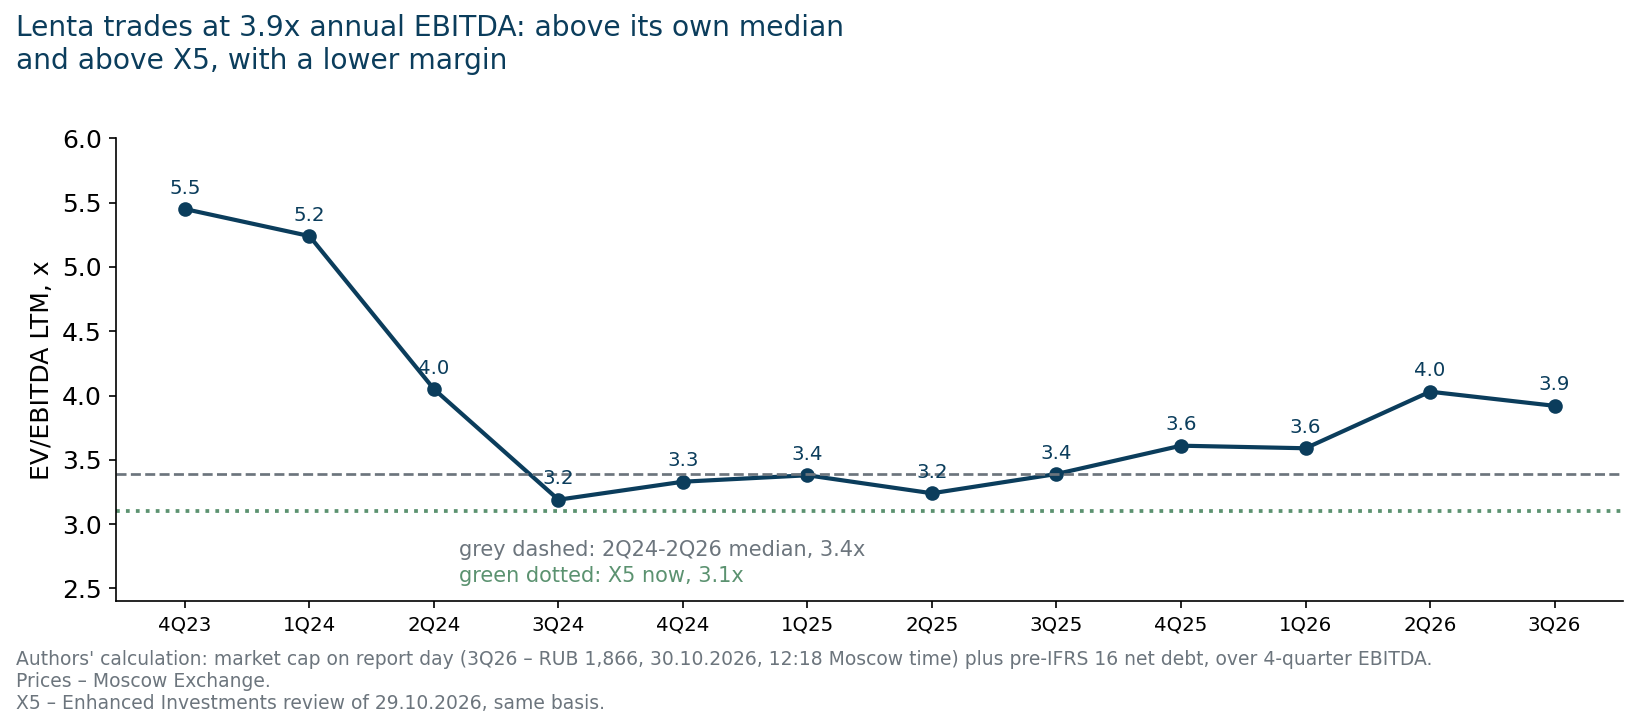
Since mid-2024 Lenta has usually traded at 3.2-3.6x EBITDA, with a median of 3.4x on report dates. It is now 3.9x: 12-month EBITDA has grown 9% since the 3Q 2025 report (from RUB 79.5 bn to RUB 86.9 bn), while net debt is up RUB 53 bn. The market is already paying for the acquired chains reaching a normal margin. Year to date the share is down 6.0%, the Moscow Exchange index is down 10.0%. Since the 2Q report (3 August) Lenta has lost 2.9%, while the index has gained 10.0%.
Scenarios for end-2027 (authors' assumptions): 2027 revenue +17% (14% organic plus a full year of O'Key), no dividends.
- Pessimistic (30%): integration drags on, EBITDA margin 6.0%, EV/EBITDA 3.0x, net debt RUB 97 bn. Value RUB 1,756 (-6%).
- Base (50%): the margin partly recovers to 6.4%, multiple 3.4x (median), debt RUB 93 bn. Value RUB 2,332 (+25%).
- Optimistic (20%): Lenta returns to the 7% strategy target, multiple 3.9x, debt RUB 88 bn. Value RUB 3,173 (+70%).
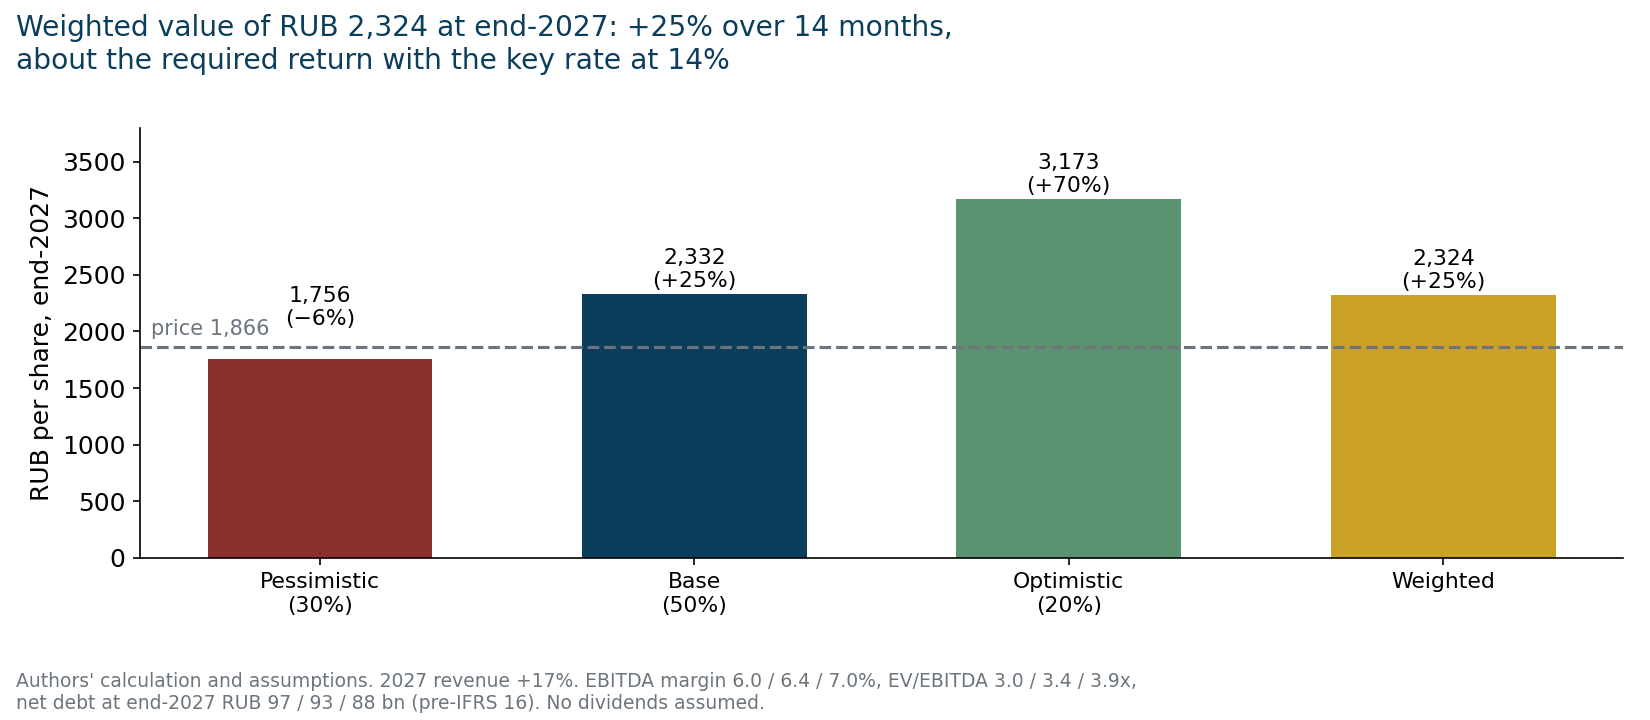
The weighted value is RUB 2,324, +25% over 14 months, or 21% a year. With the key rate at 14%, it is reasonable to require 20% a year or more from a share with no dividends (the rate plus a risk premium, authors' assumption). There is a margin of safety only in the optimistic scenario, and it needs a margin that the company itself does not promise this year.
Risks: margins of the new chains, interest, slower openings
- O'Key integration is both the main risk and the main source of growth. If the acquired chains stay near zero EBITDA in 2027, the group margin will be stuck around 6%.
- Price investment in small formats. The gross margin is falling faster than in 2Q. The company is buying traffic with price, and it is not yet clear whether this is temporary.
- Interest. RUB 20 bn a year against RUB 87 bn of EBITDA. Lower key rates help only slowly: the debt is mostly fixed-rate.
- Working capital. A RUB 24 bn outflow over 9M with no breakdown. If this is the normalisation of the acquired chains' payables, the outflow is one-off. If inventories are growing, it is a risk for 2027 cash flow.
- New acquisitions. The RUB 2.2 trn revenue target for 2028 cannot be reached without deals, and debt could rise to 2x EBITDA. This pushes dividends further out.
Bottom line
The quarter is better than the headlines about falling profit suggest. LFL accelerated to 8%, EBITDA is growing at a double-digit rate, and the margin decline is narrowing. But Lenta has warned for the first time of a possible deviation from its strategy targets, interest expense is eating the growth, and there is no free cash flow. A valuation of 3.9x annual EBITDA already assumes the O'Key integration succeeds. So we rate the share neutral. Two signals would improve the view: a 4Q EBITDA margin of at least 7% (7.9% a year ago) and working capital turning positive for the year. The next check comes with 4Q operating results in January and financial results in March 2027.
Sources
- Lenta Group, press release "Lenta Group reports 34.3% revenue growth and 8.1% LFL sales growth in 3Q 2026", 30.10.2026 (lentagroup.ru).
- Lenta Group, press release on 2Q and 1H 2026 results, 03.08.2026.
- Lenta strategy to 2028: Retail.ru and Financial One, 27.11.2025.
- Share and index prices – Moscow Exchange; historical financials – Enhanced Investments EI1 database.
- X5 – Enhanced Investments 3Q 2026 review, 29.10.2026.
Open the company's financial profile LENT →
See also: market overview · valuation map · stock screeners