MD Medical: revenue up 28.8% fails to save margin — it fell 2 p.p., and dividend yield is below fair
On August 25, MD Medical reported results for the first half of 2026. Revenue grew 28.8% to RUB 24.8 billion, EBITDA rose 20.0%, but the EBITDA margin fell from 30.2% to 28.2%, and net profit added only 5.1%. At the current price, the share looks rather attractive: multiples are below its own history, and the dividend yield of 6.7% is only slightly below the 7.0% we consider fair.
Key takeaways
— Revenue grew 28.8% in the half-year, but acquisitions drove nearly a third of the increase
— EBITDA margin fell 2 p.p. to 28.2% due to staff costs and depreciation
— Net profit rose only 5.1%: net margin dropped from 26.3% to 21.5%
— Debt rose RUB 6.7 billion over 12 months, but net debt/EBITDA remains negative
— Capex for the half-year was RUB 2.6 billion, while operating cash flow was RUB 7.1 billion
— Dividend over 12 months is RUB 89 per share, yield 6.7% versus the 7.0% we consider fair
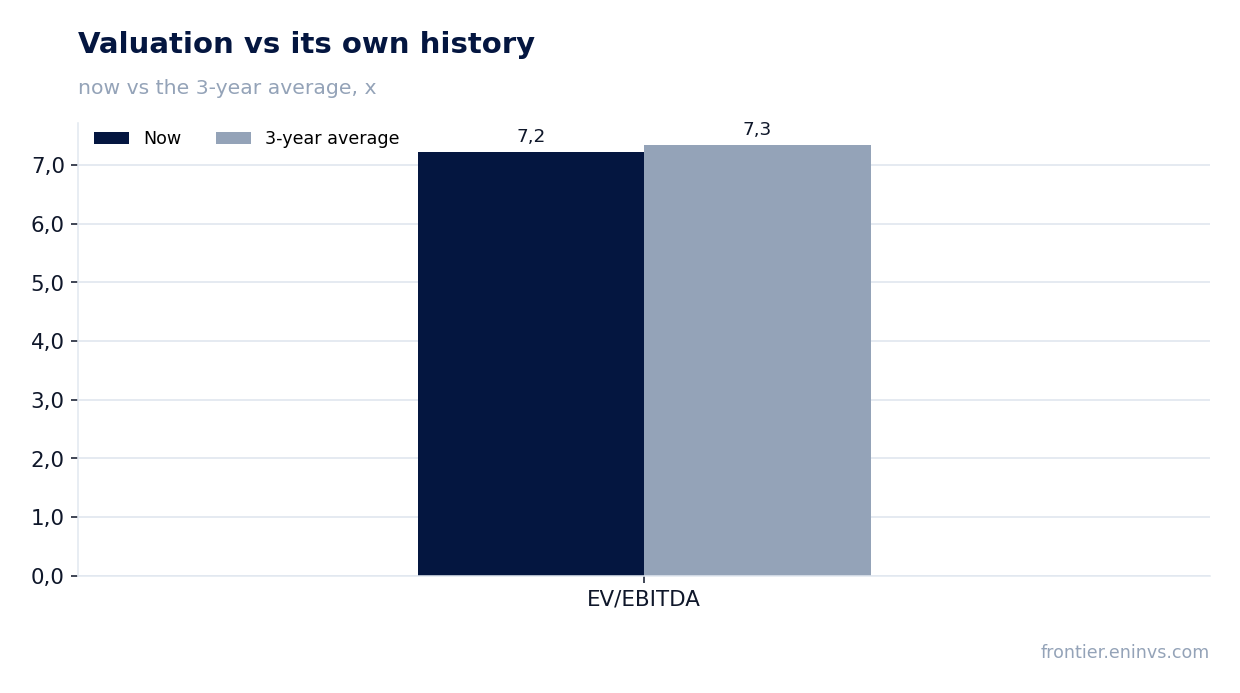
— The share trades at a discount to its own history: EV/EBITDA of 7.2 versus the average of 7.3
Attractiveness
Key figures, RUB bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 19.3 | 24.8 | +28.8% |
| EBITDA | 5.82 | 6.99 | +20.0% |
| Operating profit | 4.65 | 5.50 | +18.1% |
| Net profit | 5.06 | 5.32 | +5.1% |
| Operating cash flow | 6.05 | 7.06 | +16.7% |
| Capex | 1.35 | 2.58 | +90.2% |
| EBITDA margin | 30.2% | 28.2% | -2.0 pp |
| Net margin | 26.3% | 21.5% | -4.8 pp |
Revenue grew 28.8% in the half-year, but acquisitions drove nearly a third of the increase
In the first half of 2026, MD Medical's revenue reached RUB 24,809 million, up 28.8% year-on-year. The main contribution came from the networks acquired in June 2026 — Zdvitsa and Ilyinskaya Hospital — which added RUB 34.6 million and RUB 45.4 million in revenue, respectively. Had both deals closed on January 1, half-year revenue would have been RUB 26.6 billion, 7% above the actual figure.
Organic growth was also notable: the 'Diagnostic center and other outpatient services' segment more than doubled from RUB 2.7 billion to RUB 6.0 billion, reflecting regional expansion. Maternity services grew 26%, IVF 13%. Thus, even without M&A, the business is growing at double-digit rates.
EBITDA margin fell 2 p.p. to 28.2% due to staff costs and depreciation
EBITDA for the half-year grew 20.0% to RUB 7.0 billion, but slower than revenue, so the EBITDA margin fell from 30.2% to 28.2%. The main reason is higher cost of sales: employee compensation rose 33.7% to RUB 9.2 billion, and depreciation of fixed assets increased 10.4% to RUB 1.1 billion.
The margin decline is partly due to the integration of acquired assets, which have not yet reached target profitability. At the same time, staff cost growth outpaces inflation, possibly indicating stronger competition for medical personnel.
Net profit rose only 5.1%: net margin dropped from 26.3% to 21.5%
Net profit for the first half-year was RUB 5,323 million, only 5.1% above the prior year. Net margin fell from 26.3% to 21.5%. Besides operating factors, financial expenses weighed: last year the company reported net financial income of RUB 423 million, while this year it had expenses of RUB 176 million.
An additional factor was higher income tax: the effective rate, judging by the expense dynamics, increased due to changes in the profit structure and deferred taxes on acquisitions.
Debt rose RUB 6.7 billion over 12 months, but net debt/EBITDA remains negative
As of end-June 2026, loans and borrowings stood at RUB 10,870 million, up RUB 6.7 billion over the year. The main reason is the RUB 6.0 billion raised in the first half to finance the acquisition of Ilyinskaya Hospital. Despite higher debt, the company retains a net cash position: net debt is minus RUB 4,142 million, and net debt/EBITDA for the trailing twelve months is minus 0.32.
The company still has significant financial headroom, allowing it to fund expansion with debt without hurting its dividend policy.
Capex for the half-year was RUB 2.6 billion, while operating cash flow was RUB 7.1 billion
Operating cash flow for the first half-year reached RUB 7,060 million, up 16.7% year-on-year. Capital expenditures totaled RUB 2,577 million (purchases of fixed and intangible assets), almost double the prior year, as the company actively invests in network expansion.
Free cash flow after capex is about RUB 4.5 billion, which comfortably covers dividend payments for the half-year (RUB 3.5 billion). Thus, operating activity remains the main source of funding for investments and growth.
Dividend over 12 months is RUB 89 per share, yield 6.7% versus the 7.0% we consider fair
Over the last 12 months, the company paid RUB 89 per share, providing a dividend yield of 6.7%. Our model estimates the next payment also at RUB 89, implying a forward yield of 6.7%. We consider a yield of 7.0% fair for this name, meaning the current price is only slightly above the level that matches our target.
The payout ratio is about 0.5 of profit, leaving room for dividend growth as earnings rise. However, if the company continues large acquisitions, the pace of payout growth may slow.
The share trades at a discount to its own history: EV/EBITDA of 7.2 versus the average of 7.3
The current EV/EBITDA (LTM) multiple is 7.2, below the three-year average (7.3). P/E (LTM) is 8.7, and ROE is 28.3%, indicating high capital efficiency. Our valuation model, based on EBITDA growth and a target multiple, suggests upside potential of 13%.
Thus, given current growth rates and margins, the share appears undervalued relative to its own history and our calculations.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 98.1 bn ₽ |
| P/E (LTM) | 8.7 |
| EV/EBITDA (LTM) | 7.2 |
| P/B | 3.19 |
| Net debt / EBITDA (LTM) | -0.32 |
| Operating cash flow (LTM) | 15.0 bn |
| ROE | 28.3% |
| Dividend yield (12m) | 6.8% |
| EV/EBITDA, 3-year average | 7.3 |
Bottom line
MD Medical continues to grow at a high rate, but the quality of growth is deteriorating: EBITDA and net margins are declining, and a significant part of revenue growth comes from acquisitions that have yet to be integrated. Nevertheless, the company maintains a net cash position, generates strong operating cash flow, and pays dividends with a yield close to fair. With multiples below its own history and upside potential of 13% on our model, the share looks rather attractive. The key question for a holder is whether the company can restore margins to last year's levels; otherwise, the current valuation may be justified.
Open the company's financial profile MDMG →
See also: market overview · valuation map · stock screeners