MOEX: profit up 4.7% but margin compressed 4.5 points, while the dividend yield stays ahead of the key rate
On 26 August MOEX reported Q2 2026 results. Revenue rose 15.2% year on year to RUB 35,560.4 mn, net profit – 4.7% to RUB 15,766.2 mn, EBITDA – 4.7% to RUB 15,766.0 mn. Top-line growth decelerated from 16.3% in Q1, while the EBITDA margin fell from 48.8% to 44.3%. With the stock on a P/E LTM of 7.6 and a dividend yield of 13.0% against the 10.5% we consider fair, the share looks attractive at the current price for an income-oriented holder.
Key takeaways
— Revenue rose 15.2%, but this is a deceleration from 16.3% a quarter earlier
— EBITDA margin compressed to 44.3% from 48.8% a year earlier
— Net profit added only 4.7% – cost growth ate almost all of the revenue gain
— Fee and commission income rose to RUB 22,271.7 mn, supporting the top line
— Dividend yield of 13.0% exceeds the 10.5% we consider fair and the 14.0% key rate
— P/E LTM of 7.6 and ROE of 24.4% – valuation remains low for such a return on equity
— On the portal's model, the stock has 19% upside to fair value
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 30.9 | 35.6 | +15.2% |
| EBITDA | 15.1 | 15.8 | +4.7% |
| Operating profit | 13.3 | 15.0 | +13.2% |
| Net profit | 15.1 | 15.8 | +4.7% |
| Capex | 2.04 | 1.99 | -2.5% |
| EBITDA margin | 48.8% | 44.3% | -4.5 pp |
| Net margin | 48.8% | 44.3% | -4.5 pp |
Revenue rose 15.2%, but this is a deceleration from 16.3% a quarter earlier
MOEX revenue in Q2 2026 came in at RUB 35,560.4 mn, up 15.2% year on year. This is a deceleration from 16.3% growth in Q1. Fee and commission income contributed RUB 22,271.7 mn, while net interest income was RUB 13,288.7 mn.
The slowdown comes against a high base from Q2 2025, when revenue jumped 144.8% year on year. At that time the market saw a surge in trading volumes after sanctions on currency pairs. Now growth is returning to more moderate rates, reflecting normalisation of market activity.
Fee income is growing faster than interest income: over the year it added about RUB 4.4 bn, while net interest income remained almost flat. This suggests transaction services are becoming the key driver of revenue, rather than the interest business.
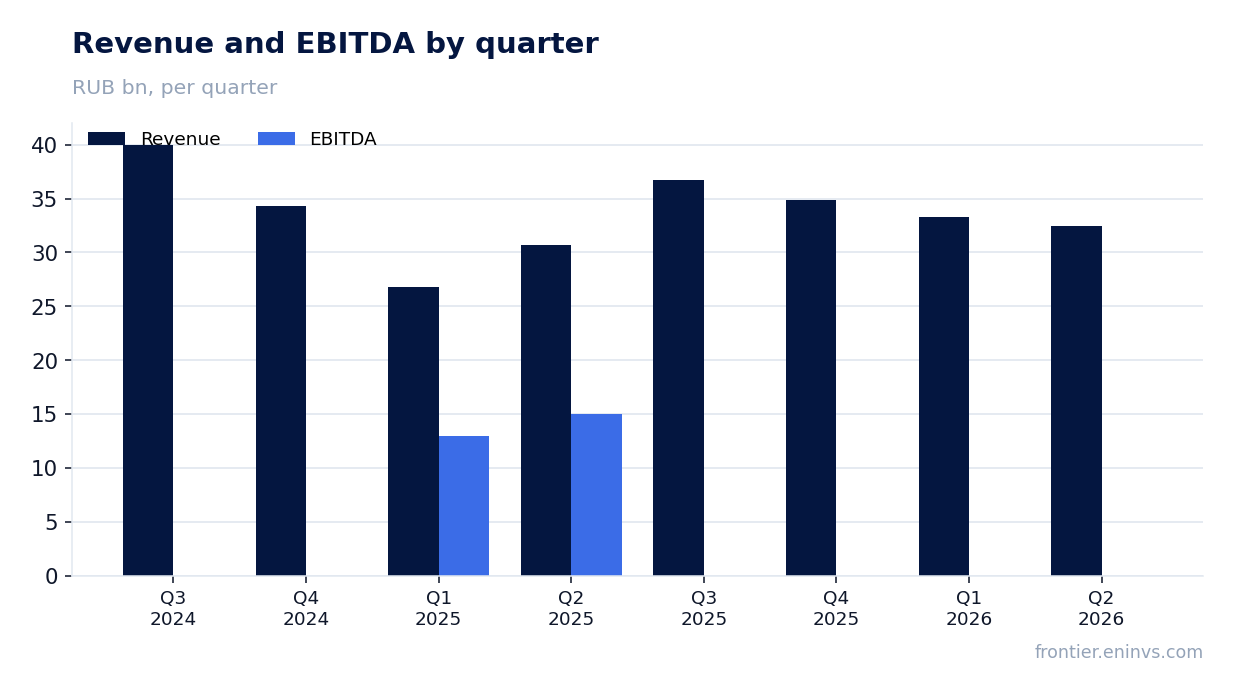
EBITDA margin compressed to 44.3% from 48.8% a year earlier
EBITDA in Q2 2026 was RUB 15,766.0 mn, up 4.7% year on year. However, the EBITDA margin fell to 44.3% from 48.8% in Q2 2025. This means that revenue growth of 15.2% was accompanied by faster growth in operating expenses.
Operating profit was RUB 15,002.1 mn, also up 4.7% from a year earlier. The gap between revenue and profit growth points to an increased share of service-related costs – fee and other direct expenses, which have been disclosed as a separate line since 2026.
A 4.5 percentage point margin contraction is a significant change for an exchange business, where operating leverage is usually high. If last year each ruble of revenue brought almost 49 kopecks of EBITDA, now it brings 44 kopecks. This may be due to a shift in the revenue mix towards less profitable segments or to higher personnel and technology costs.
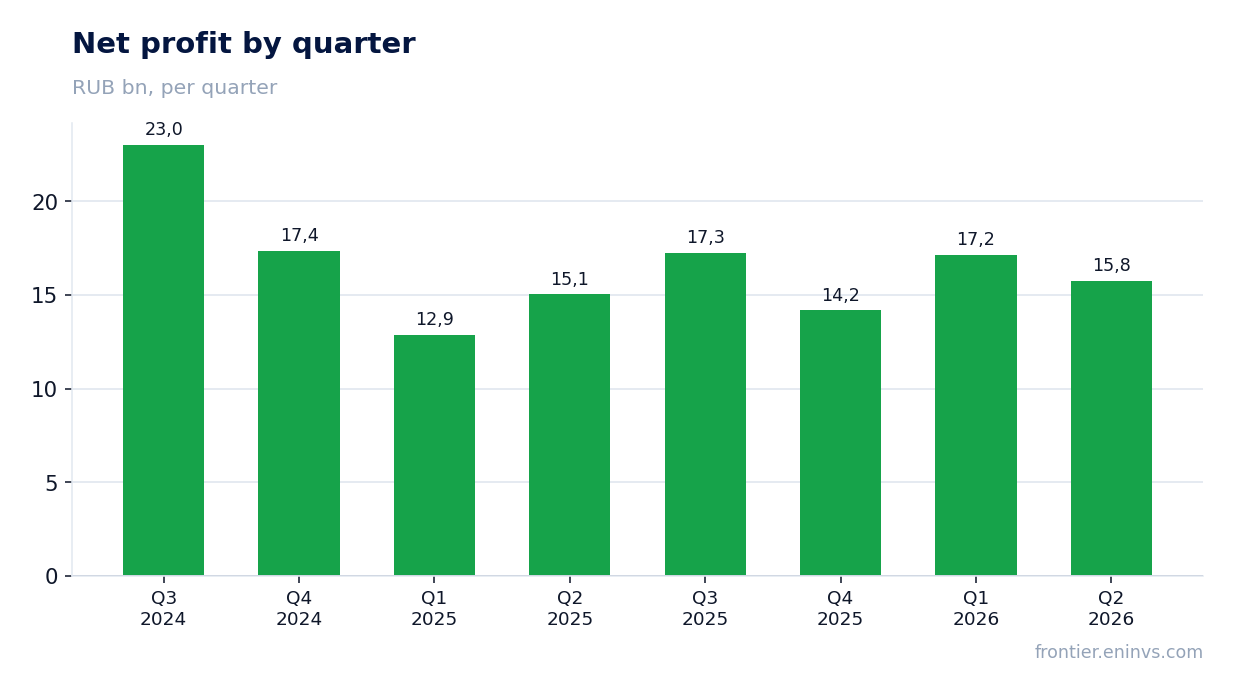
Net profit added only 4.7% – cost growth ate almost all of the revenue gain
Net profit in Q2 2026 was RUB 15,766.2 mn, up 4.7% year on year. This is significantly slower than revenue growth of 15.2%. The ratio of net profit to net interest income fell to 44.3% from 48.8% a year earlier, reflecting pressure on profitability.
For H1 2026, net profit was RUB 32,929.0 mn versus RUB 27,947.1 mn in the same period last year. However, growth slowed in Q2: while profit grew 32.2% in Q1, it added only 4.7% in Q2. This is a sharp deceleration.
The main reason is faster growth in expenses. Fee and other direct expenses, as well as general and administrative expenses, are growing faster than revenue. In H1 2026, depreciation of property and equipment was RUB 4,317.0 mn versus RUB 3,606.0 mn a year earlier, also weighing on profit.
Fee and commission income rose to RUB 22,271.7 mn, supporting the top line
Fee and commission income in Q2 2026 was RUB 22,271.7 mn, up 24.8% year on year. This is the key driver of revenue: without its growth, total revenue would have shown much more modest dynamics. Net interest income remained almost flat at RUB 13,288.7 mn versus RUB 13,008.5 mn.
Within fee income, the largest contributions come from money market trading (RUB 5,871.8 mn per quarter), derivatives market (RUB 4,144.1 mn) and equity market (RUB 4,693.6 mn). Fee income growth of 24.8% outpaces revenue growth, indicating an increasing share in total income.
Financial marketplace services brought RUB 1,700.4 mn per quarter, up 3.5% year on year. This segment is growing slower than other fee segments but remains a significant source of diversification.
Dividend yield of 13.0% exceeds the 10.5% we consider fair and the 14.0% key rate
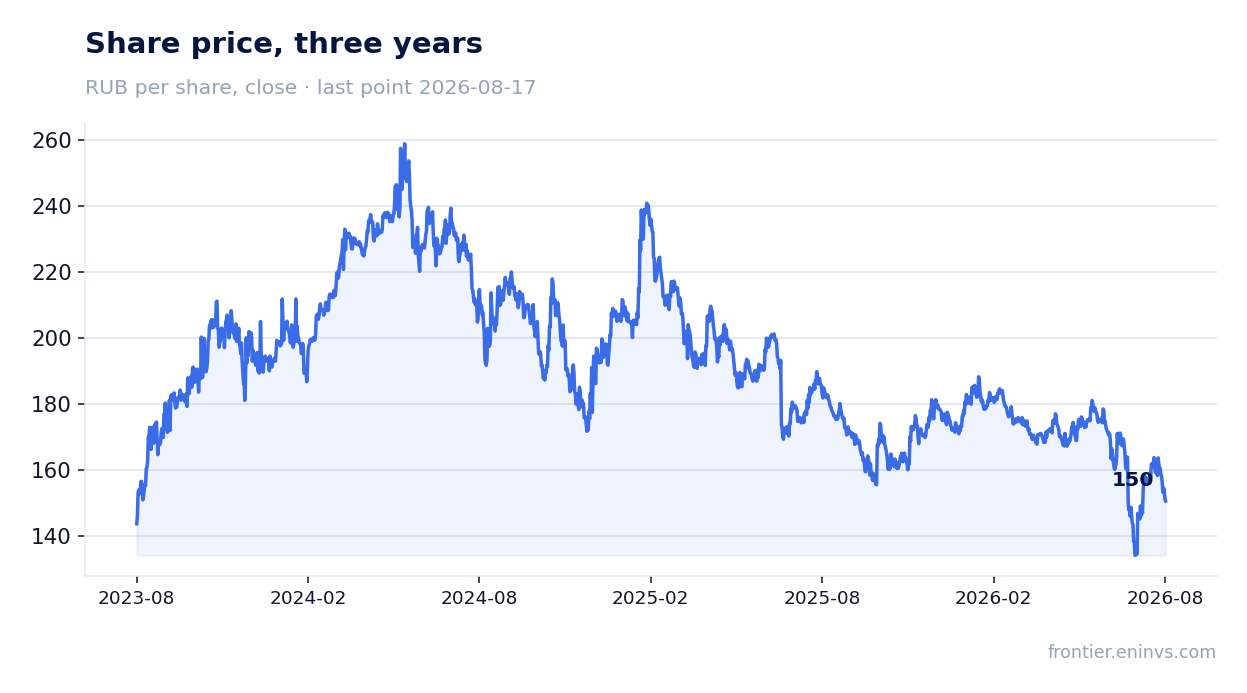
Over the last 12 months MOEX paid RUB 19.57 per share, giving a current dividend yield of 13.0% at the price of RUB 154.31. This is above the 10.5% yield we consider fair for the name. On our model, the next dividend could be RUB 21.27 per share, implying a forward yield of 14.1%.
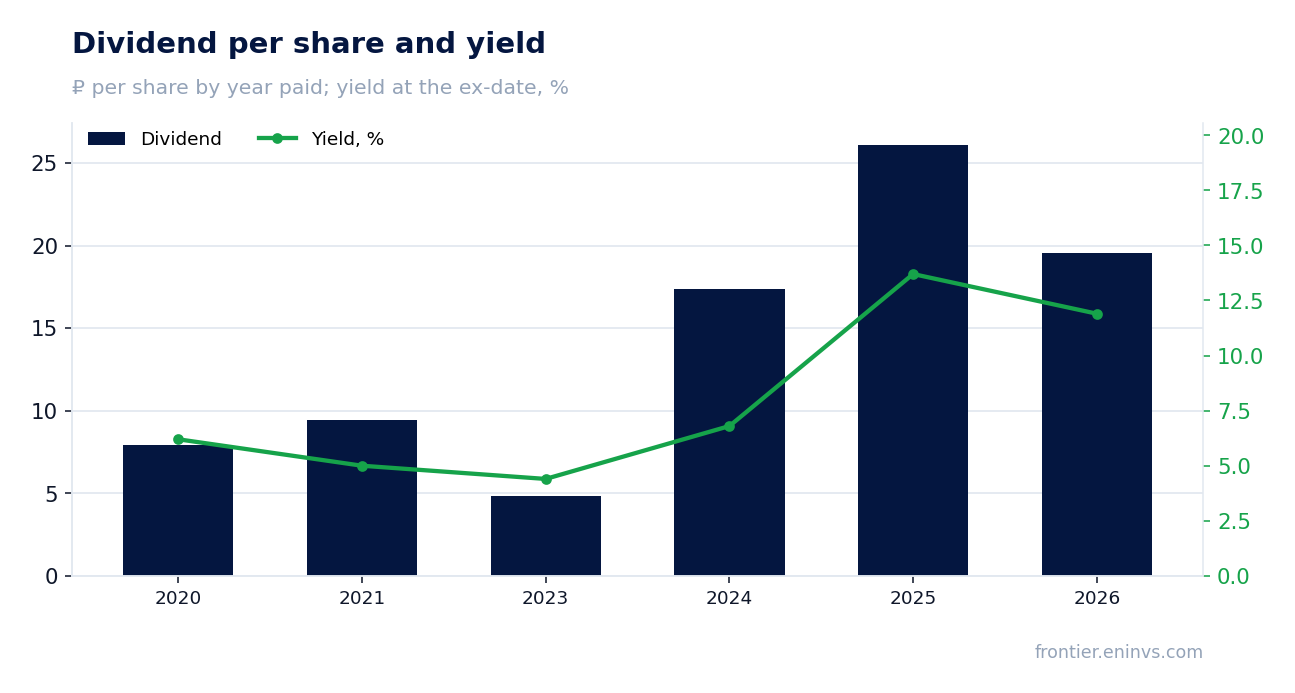
The payout history shows growth: in 2024 the dividend was RUB 17.35 per share, in 2025 – RUB 26.11, and for 2026 RUB 19.57 has already been paid. The yield at the ex-date reached 13.7% in 2025 and 11.9% in 2026. The current yield of 13.0% is in the upper part of the historical range.
The CBR key rate is 14.0%, and MOEX's dividend yield of 13.0% is only slightly below it. With the forward estimate of 14.1%, the stock offers a yield comparable to the rate while also having capital growth potential. This makes it attractive for conservative investors.
The risk to the dividend is lower profit: the payout ratio is 0.75 of profit. If margin pressure persists, profit may not grow, and the dividend could stay at last year's level. Even in that case, the yield remains above 10.5%.
P/E LTM of 7.6 and ROE of 24.4% – valuation remains low for such a return on equity
MOEX shares trade at a P/E LTM of 7.6 with a return on equity of 24.4%. This is a low valuation for a company earning a quarter of its equity. Historically, the stock traded at higher multiples, but the current level reflects concerns about slowing growth.
Market capitalisation is RUB 342,302.5 mn. With net profit of RUB 44,920.4 mn over the last 12 months and revenue of RUB 140,000.0 mn, the company looks undervalued relative to its historical metrics. However, LTM includes both strong quarters and periods of deceleration.
On the portal's model, the stock has 19% upside to fair value. This is our own calculation based on comparing ROE and P/B. It is not a market consensus and does not represent a target price.
On the portal's model, the stock has 19% upside to fair value
Our model estimates the stock's upside to fair value at 19%. This is the result of comparing return on equity of 24.4% with the current price-to-book ratio. The model assumes the market will eventually value MOEX's business resilience above the current level.
However, realising this potential depends on the company's ability to maintain margin and profit. If cost pressure persists, profit may not grow, and multiples could remain low. In that case, fair value would be below the estimate.
It is important to note that the stock is held in our live model strategies: RU AI conviction (Claude), RU AI long-short (market-neutral) and RU Banks & financials (potential). This is a fact, not an argument for the valuation – each strategy screens stocks by its own criteria.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 342 bn ₽ |
| P/E (LTM) | 7.6 |
| P/B | 1.27 |
| ROE | 24.4% |
| Dividend yield (12m) | 13.0% |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2020 | 7.93 | 6.2% |
| 2021 | 9.45 | 5.0% |
| 2023 | 4.84 | 4.4% |
| 2024 | 17.35 | 6.8% |
| 2025 | 26.11 | 13.7% |
| 2026 | 19.57 | 11.9% |
Bottom line
MOEX reported Q2 2026 with revenue up 15.2%, but profit added only 4.7% due to margin compression. The strengths remain fee income, up 24.8%, and a high return on equity of 24.4%. The weaknesses are the deceleration in revenue growth from Q1 and the fall in EBITDA margin to 44.3%. For a holder, the key question is whether the 13.0% dividend yield can be sustained at the current profit level. At the current price the stock looks attractive: P/E LTM of 7.6, dividend yield above the 10.5% we consider fair, and 19% upside on the portal's model.
Open the company's financial profile MOEX →
See also: market overview · valuation map · stock screeners