IDGC Center & Volga: profit up 20.7% as debt turns into RUB 4.9 bn net cash
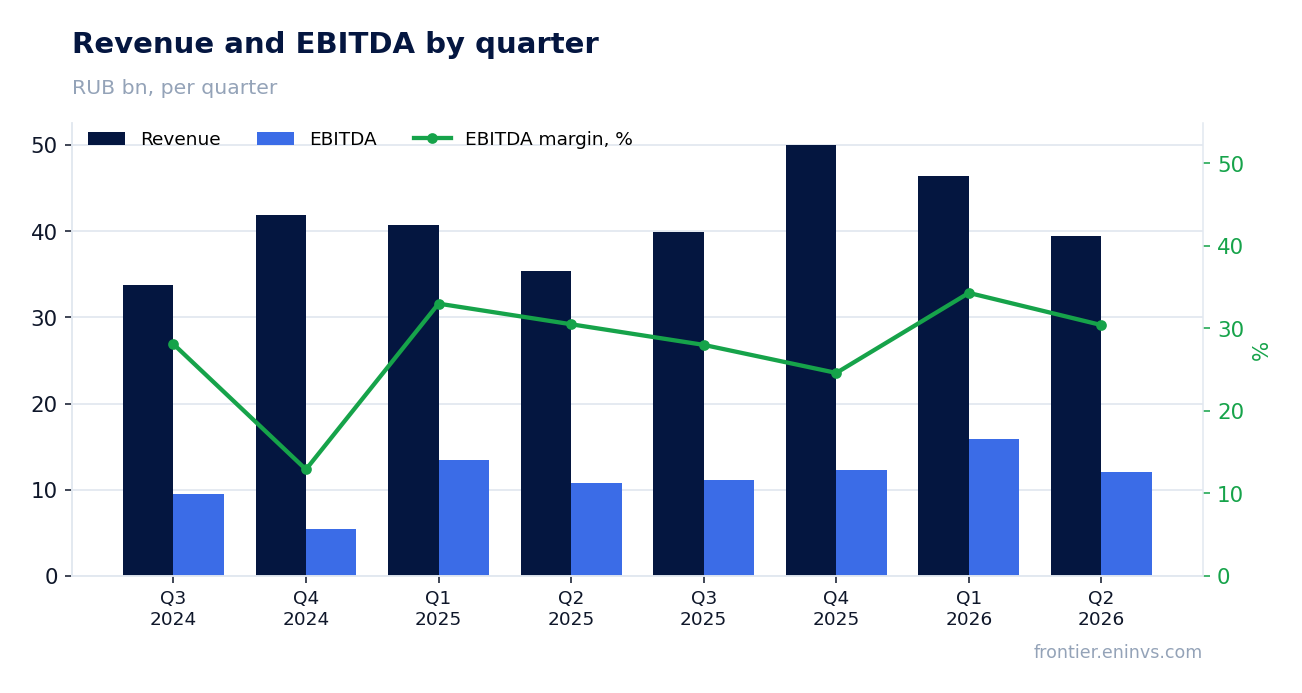
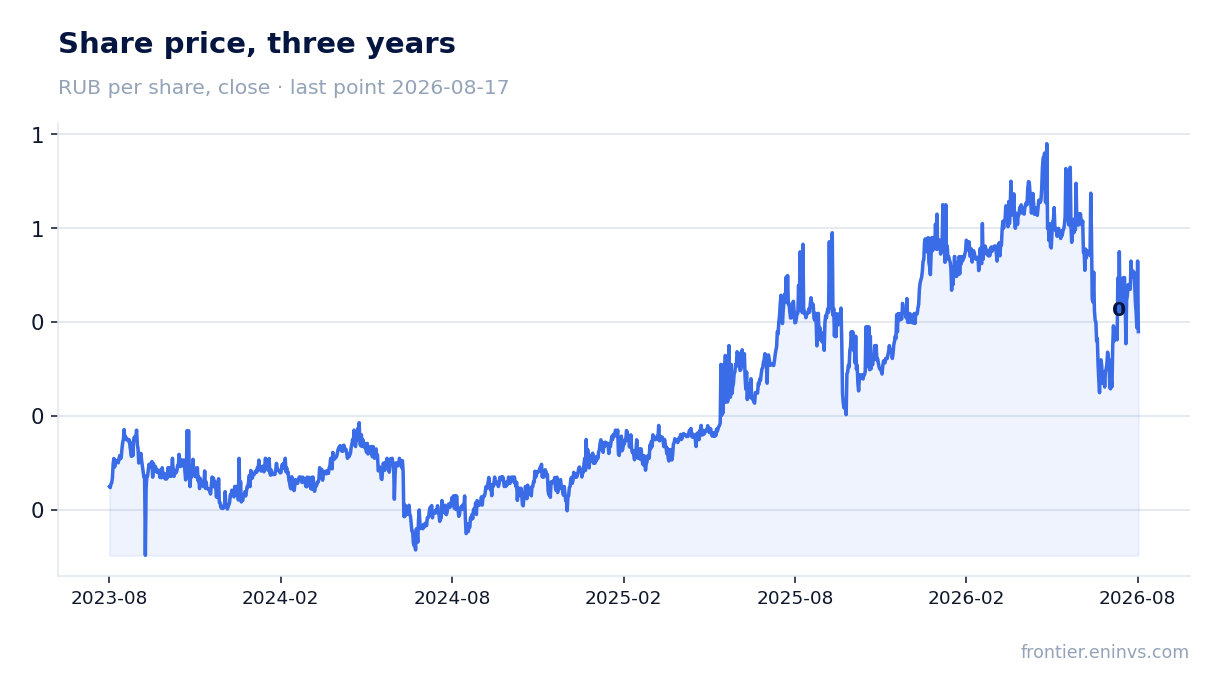
On 28 August, IDGC Center & Volga reported results for the second quarter of 2026. Revenue rose 11.5% year on year to RUB 39.5 bn, EBITDA reached RUB 12.0 bn (+11.2%), and net profit was RUB 6.0 bn (+20.7%). Top-line growth decelerated from +13.9% in the first quarter, but the company held net cash for a second consecutive quarter: net debt stood at RUB -4.9 bn on 30 June versus RUB 3.5 bn a year earlier. At RUB 0.4861 per share, the stock trades at EV/EBITDA of 1.06 – below its own three-year average of 1.46 – while the 13.8% dividend yield is well above the 10.5% we consider fair. Verdict: rather attractive, as the dividend and cash cushion outweigh the revenue slowdown.
Key takeaways
— Revenue rose 11.5%, but growth decelerated from the first quarter
— Profit gained 20.7% on lower interest costs, not just operating momentum
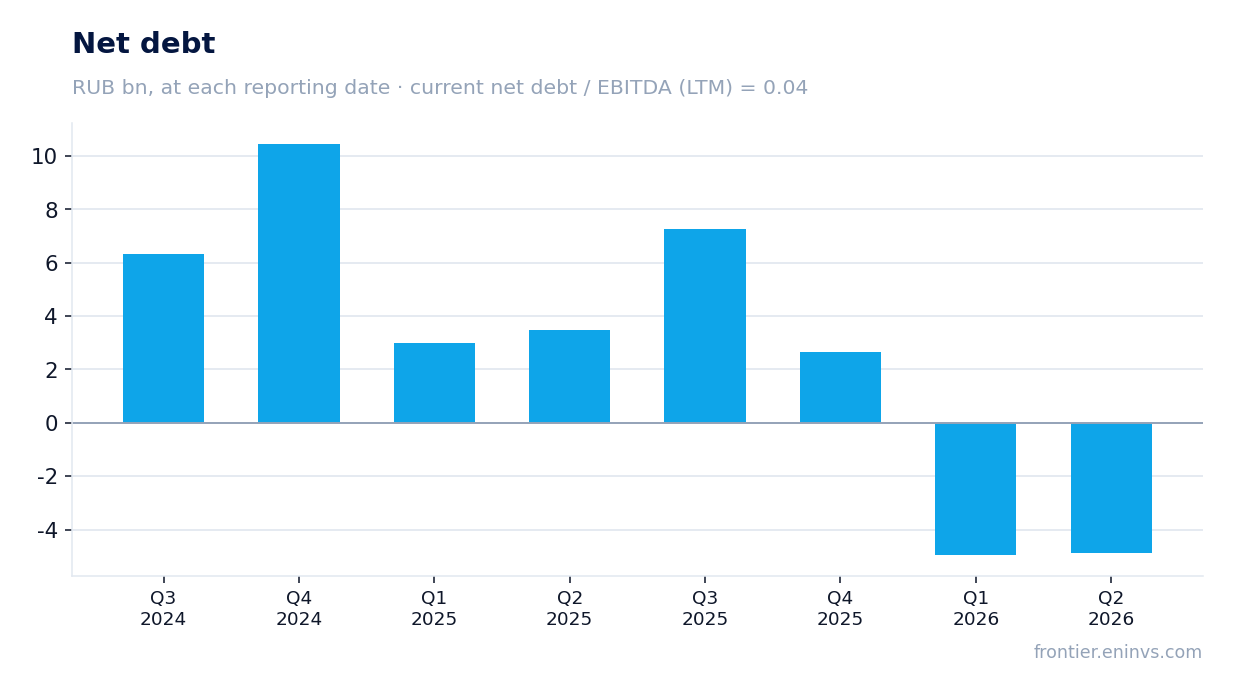
— Net debt was RUB -4.9 bn on 30 June versus RUB 3.5 bn a year earlier
— H1 capex rose to RUB 12.5 bn, but operating cash flow covers it
— We estimate the 2026 dividend at RUB 0.08 per share – 14.7% on the current price
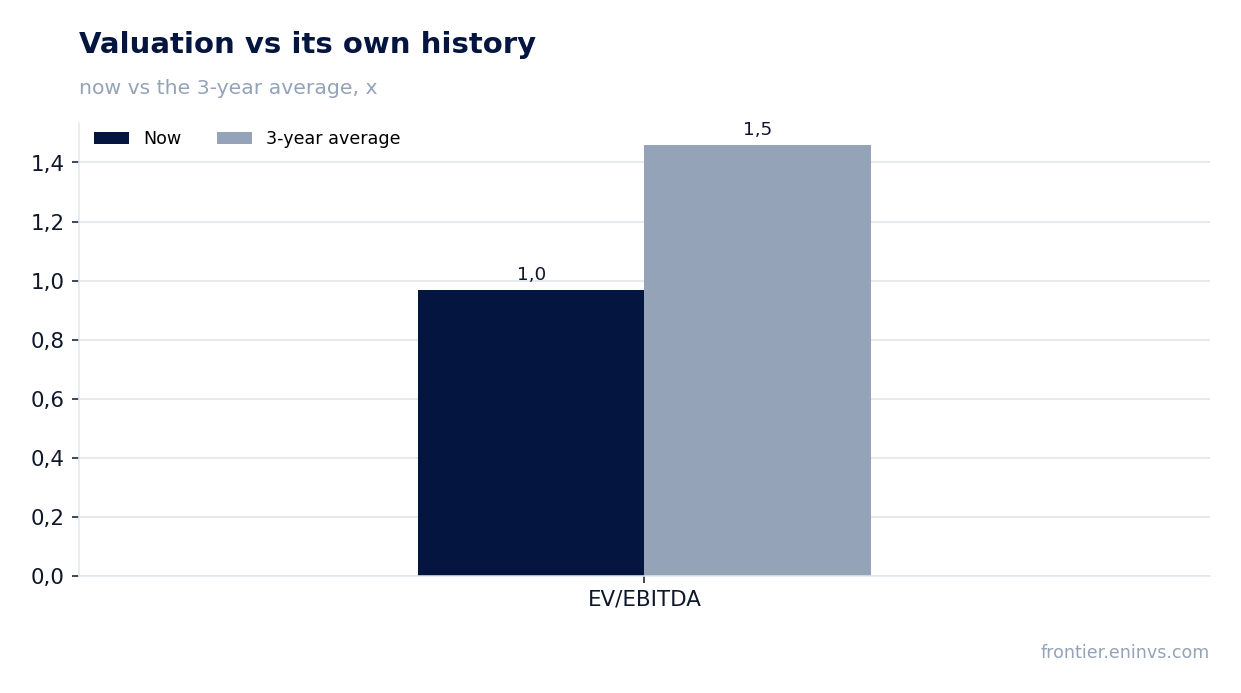
— EV/EBITDA of 1.06 is below the company's own three-year average of 1.46
— The portal's model implies 47% upside to fair value
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 35.4 | 39.5 | +11.5% |
| EBITDA | 10.8 | 12.0 | +11.2% |
| Operating profit | 7.19 | 7.94 | +10.4% |
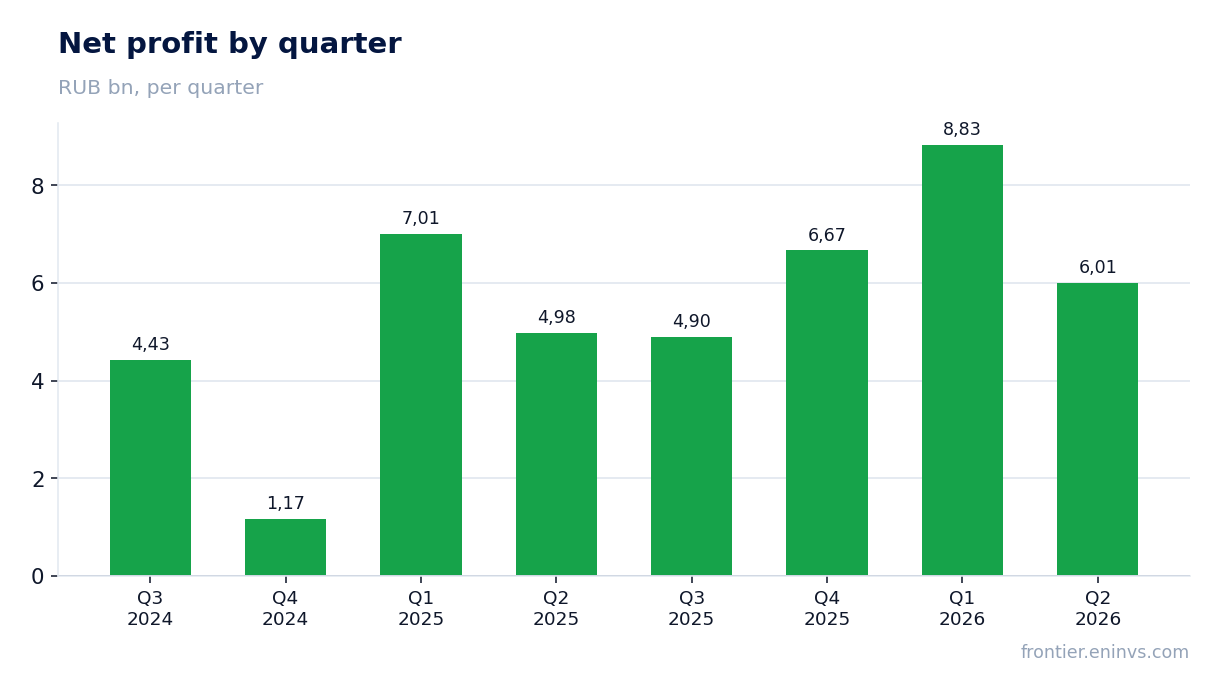
| Net profit | 4.98 | 6.01 | +20.7% |
| Operating cash flow | 2.72 | 4.56 | +67.5% |
| Capex | 5.17 | 5.80 | +12.1% |
| EBITDA margin | 30.5% | 30.4% | -0.1 pp |
| Net margin | 14.1% | 15.2% | +1.1 pp |
Revenue rose 11.5%, but growth decelerated from the first quarter
In the second quarter of 2026, IDGC Center & Volga's revenue reached RUB 39.5 bn, up 11.5% year on year. This is a deceleration from the first quarter, when growth was 13.9%. Electricity transmission remains the main contributor: according to the report, this segment generated RUB 36.5 bn versus RUB 32.7 bn a year earlier. Technological connection to grids rose to RUB 1.5 bn from RUB 1.2 bn.
The slowdown in revenue growth does not look alarming: the company operates in a regulated tariff environment, and quarterly dynamics can fluctuate due to the timing of connections and settlements with consumers. Annual growth remains in double digits, which is a normal level for a grid company with predictable tariffs. More importantly, revenue is growing faster than operating costs, which drives margin improvement.
Profit gained 20.7% on lower interest costs, not just operating momentum
Net profit in the second quarter of 2026 rose 20.7% year on year to RUB 6.0 bn, while EBITDA grew 11.2% and operating profit 10.4%. The outperformance of net profit versus EBITDA is explained by lower interest costs: RUB 1.1 bn for the quarter versus RUB 1.7 bn a year earlier. This is the result of a reduced debt portfolio and a shift into a net cash position.
The EBITDA margin remained virtually flat at 30.4% versus 30.5% a year earlier. The net margin rose to 15.2% from 14.1%. The increase in net margin with stable operating profitability is a consequence of the financial component. If interest costs continue to decline, this will support profit in the coming quarters as well.
Net debt was RUB -4.9 bn on 30 June versus RUB 3.5 bn a year earlier
As of 30 June 2026, IDGC Center & Volga's net debt stood at RUB -4.9 bn, meaning the company has a net cash position. A year earlier, on 30 June 2025, net debt was positive at RUB 3.5 bn. The reduction over 12 months was RUB 8.4 bn. Compared with 31 March 2026, net debt was virtually unchanged: RUB -5.0 bn at the end of the first quarter versus RUB -4.9 bn at the end of the second.
The net debt to EBITDA ratio for the trailing twelve months is -0.08. This is a level, not a direction: we do not have an earlier value for this ratio, so we do not claim that leverage rose or fell – it remains negative. Cash on the balance sheet rose to RUB 35.1 bn from RUB 27.8 bn at the end of 2025. Interest expenses for the half-year fell to RUB 2.2 bn from RUB 3.3 bn a year earlier, confirming that debt service is no longer weighing on profit.
H1 capex rose to RUB 12.5 bn, but operating cash flow covers it
In the first half of 2026, IDGC Center & Volga's capital expenditures amounted to RUB 12.5 bn versus RUB 10.7 bn a year earlier. Operating cash flow for the same period reached RUB 17.8 bn, fully covering the investments. In the second quarter alone, operating cash flow was RUB 4.6 bn and capital expenditures RUB 5.8 bn, meaning that in a single quarter the flow did not cover capex, but at the half-year level the ratio is comfortable.
The increase in capital expenditures is a normal story for a grid company upgrading its infrastructure. Importantly, the company funds the programme from its own resources without increasing debt. This explains why net debt remains negative despite higher capex. If the investment programme continues to grow, it could limit dividend payments, but for now there is a margin of safety.
We estimate the 2026 dividend at RUB 0.08 per share – 14.7% on the current price
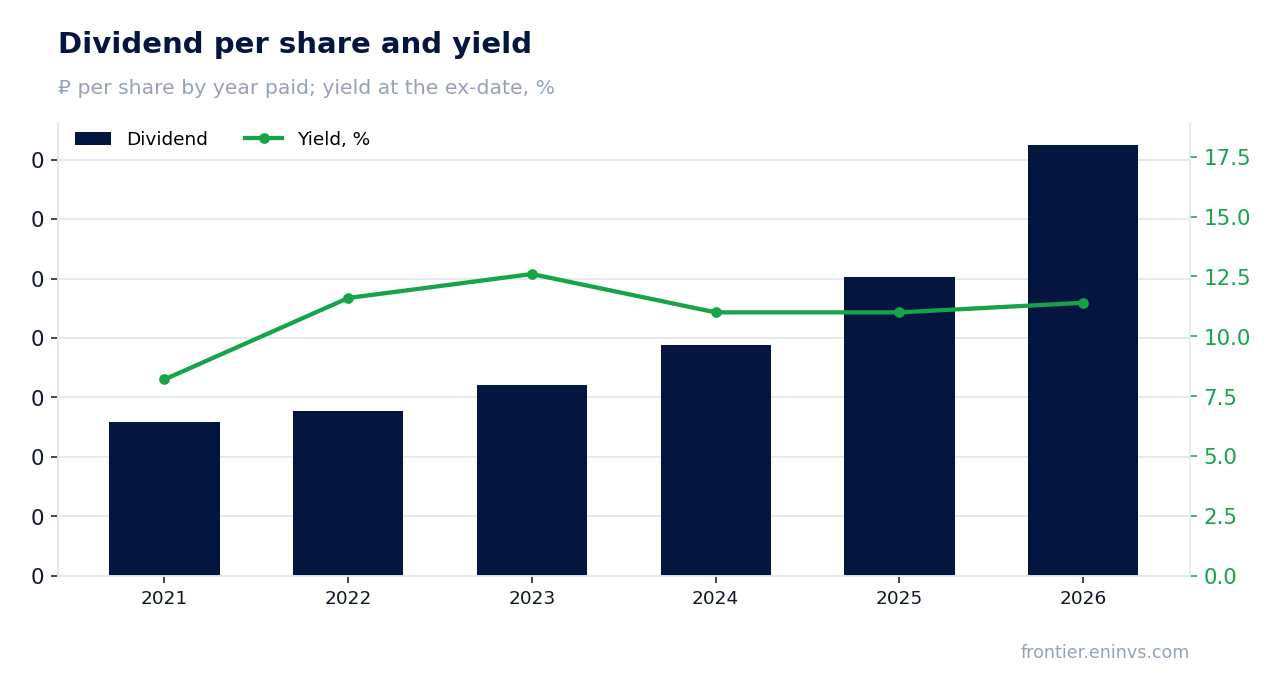
Over the last 12 months, IDGC Center & Volga paid RUB 0.0725 per share, which at the current price gives a yield of 13.8%. This is the payment for 2025. Our estimate for the current financial year's dividend is RUB 0.08 per share, corresponding to 14.7% on the current price. This is our own calculation, not a board decision: we assume a payout ratio of 0.33 of profit, as last year, and trailing twelve-month profit.
The 13.8% yield is noticeably above the key rate of 14.0% – effectively at the same level, but with the expected dividend increase to RUB 0.08, the forward yield reaches 15.9%. For comparison, we consider a fair yield for this name to be 10.5%. The payment history shows steady growth: from RUB 0.0259 in 2021 to RUB 0.0725 in 2026. The yield at the ex-date price ranged from 8.2% to 12.6%, and the current level is above the historical range.
What could make the dividend smaller: an increase in capital expenditures requiring more own funds, or a decline in profit due to tariff decisions. So far, the company generates enough cash to pay and invest simultaneously. The dividend is the main reason the stock is attractive: with a yield above 13% and a net cash position, the risk of a payout cut is low.
EV/EBITDA of 1.06 is below the company's own three-year average of 1.46
Based on the trailing twelve months, IDGC Center & Volga's EV/EBITDA is 1.06, while the three-year average for this multiple is 1.46. The stock trades below its own history. The trailing P/E is 2.24. Market capitalisation is RUB 59.2 bn, which, with a net cash position of RUB 4.9 bn, gives a very low valuation for the business.
Such a low valuation is explained primarily by the company's status: it is a subsidiary of Rosseti with regulated tariffs and limited liquidity. The market does not price in significant growth, but it also does not demand a high risk premium. According to the portal's model, which compares EBITDA growth with a target multiple, the upside to fair value is +47%. This is our own model, not a market consensus.
The portal's model implies 47% upside to fair value
Our fundamental model, which compares EBITDA growth with a target multiple and market capitalisation, shows 47% upside to fair value. This is not a target price or a recommendation, but the output of the portal's model. The model uses the current trailing twelve-month EBITDA and the historical range of the multiple.
The stock is held in our live model strategies on the portal – RU Dividend growers (income). This is a fact, not an argument for the valuation: inclusion in the strategy reflects compliance with its own criteria, not our view on attractiveness. The model's upside matters in the context of the dividend yield: even without a re-rating, the stock can deliver returns through payouts.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 59.2 bn ₽ |
| P/E (LTM) | 2.2 |
| EV/EBITDA (LTM) | 1.1 |
| P/B | 0.50 |
| Net debt / EBITDA (LTM) | -0.08 |
| Operating cash flow (LTM) | 39.8 bn |
| ROE | 19.3% |
| Dividend yield (12m) | 13.8% |
| EV/EBITDA, 3-year average | 1.5 |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2021 | 0.03 | 8.2% |
| 2022 | 0.03 | 11.6% |
| 2023 | 0.03 | 12.6% |
| 2024 | 0.04 | 11.0% |
| 2025 | 0.05 | 11.0% |
| 2026 | 0.07 | 11.4% |
| Our estimate, current year | 0.08 | 14.7% on the current price |
Bottom line
IDGC Center & Volga delivered a solid quarter: revenue and EBITDA grew at double-digit rates, and net profit gained over 20% on lower interest costs. The company held a net cash position of RUB 4.9 bn for a second consecutive quarter, removing debt risks. The 13.8% dividend yield and expected RUB 0.08 per share make the stock attractive for income-oriented investors. EV/EBITDA of 1.06 is below its own three-year average, and the portal's model implies 47% upside. The key question for a holder is whether profit growth will persist amid a revenue slowdown and whether the increased investment programme will eat into the dividend. Verdict: rather attractive – the dividend and cash cushion outweigh the slowdown.
Open the company's financial profile MRKP →
See also: market overview · valuation map · stock screeners