Russneft: H1 profit up a third, but almost half of debt may be called early
On August 25, Russneft released its results for the first half of 2026. EBITDA rose 37.5% year on year, net profit 34.7%, and EBITDA margin improved from 20.2% to 27.5%. At the same time, the auditor flagged that loans of RUB 114.4 bn could be called early, almost twice the net debt. At the current price, the share looks attractive: EV/EBITDA of 2.7x is below its three-year average, and the dividend yield exceeds the fair level.
Key takeaways
— H1 EBITDA up 37.5% – to a 27.5% margin
— H1 net profit up 34.7% – to a 13.2% margin
— H1 revenue almost flat – growth came from prices and mix
— Net debt up RUB 21.8 bn in six months and RUB 43.5 bn over the year
— Auditor flags risk of early loan repayment of RUB 114.4 bn
— Dividend yield of 17.2% over 12 months – above fair
— Portal model sees 260% upside
Attractiveness
Key figures, RUB bn
| Metric | H1 2025 | H1 2026 | Change |
|---|---|---|---|
| Revenue | 120 | 120 | +0.7% |
| EBITDA | 24.1 | 33.1 | +37.5% |
| Operating profit | 21.5 | 29.7 | +38.4% |
| Net profit | 11.8 | 15.9 | +34.7% |
| Operating cash flow | 21.7 | 27.6 | +27.0% |
| Capex | 14.4 | 11.3 | -21.6% |
| EBITDA margin | 20.2% | 27.5% | +7.3 pp |
| Net margin | 9.9% | 13.2% | +3.3 pp |
H1 EBITDA up 37.5% – to a 27.5% margin
For the first half of 2026, Russneft's EBITDA reached RUB 30,984 mn on an LTM basis, up 37.5% year on year. The EBITDA margin rose from 20.2% to 27.5% – this is the key metric of the report: the company earns more on every ruble of revenue.
EBITDA growth with almost flat revenue means the improvement came not from volumes but from operational efficiency or pricing conditions. The report does not provide segment detail – the company operates in a single segment, 'Exploration, production and related services', so the drivers of margin remain within cost of sales.
H1 net profit up 34.7% – to a 13.2% margin
Net profit for the first half of 2026 rose 34.7% year on year, and net margin improved from 9.9% to 13.2%. On an LTM basis, net profit was RUB 27,900 mn, implying a margin of about 12.7% – lower than in the reported half-year but still high.
The report shows one-off items: charity expenses rose to RUB 3,281 mn from RUB 440 mn a year earlier, while impairment of financial assets was RUB 3,177 mn versus RUB 4,196 mn. Without these items, profit would have been higher, but the company deliberately allocates funds to social projects and reserves for loan losses.
H1 revenue almost flat – growth came from prices and mix
Revenue for the first half of 2026 was RUB 120,450 mn, only 0.7% higher than a year earlier (RUB 119,608 mn). Export revenue rose from RUB 55,542 mn to RUB 84,149 mn, while domestic revenue fell from RUB 64,066 mn to RUB 36,301 mn. This indicates a shift toward exports, where ruble prices were higher.
The report shows oil sales for export rose from RUB 55,542 mn to RUB 84,149 mn, while domestic sales fell from RUB 60,358 mn to RUB 32,792 mn. The emergence of new large export buyers (Main buyer 1 – RUB 27,643 mn, Main buyer 2 – RUB 18,968 mn) confirms the shift in sales channels.
Net debt up RUB 21.8 bn in six months and RUB 43.5 bn over the year
Net debt at the end of the half-year was RUB 59,630 mn, up RUB 21.8 bn from the previous reporting date and RUB 43.5 bn over the trailing twelve months. The net debt to LTM EBITDA ratio of 1.92 is moderate, but the debt dynamics warrant attention.
The increase in debt is linked to financing the buyback of own shares: RUB 29,725 mn was spent on this in the half-year, as well as to an increase in long-term loans issued to related parties – from RUB 96,701 mn to RUB 125,385 mn. The company is increasing debt, but also placing funds in loans, as seen from financial income of RUB 6,175 mn for the half-year.
Auditor flags risk of early loan repayment of RUB 114.4 bn
The auditor's report states that debt on long-term loans and borrowings of RUB 114,428 mn may be called early by creditors due to breaches of certain covenants. This resulted in overstating long-term liabilities and understating short-term liabilities by the same amount.
As of June 30, 2026, current liabilities exceeded current assets by RUB 34,867 mn (a year earlier – by RUB 88,195 mn). Management states measures to reduce liquidity risks: revising the capex program, attracting prepayments from buyers, and rescheduling payments to suppliers. Nevertheless, the risk of early repayment is key to assessing the debt burden.
Dividend yield of 17.2% over 12 months – above fair
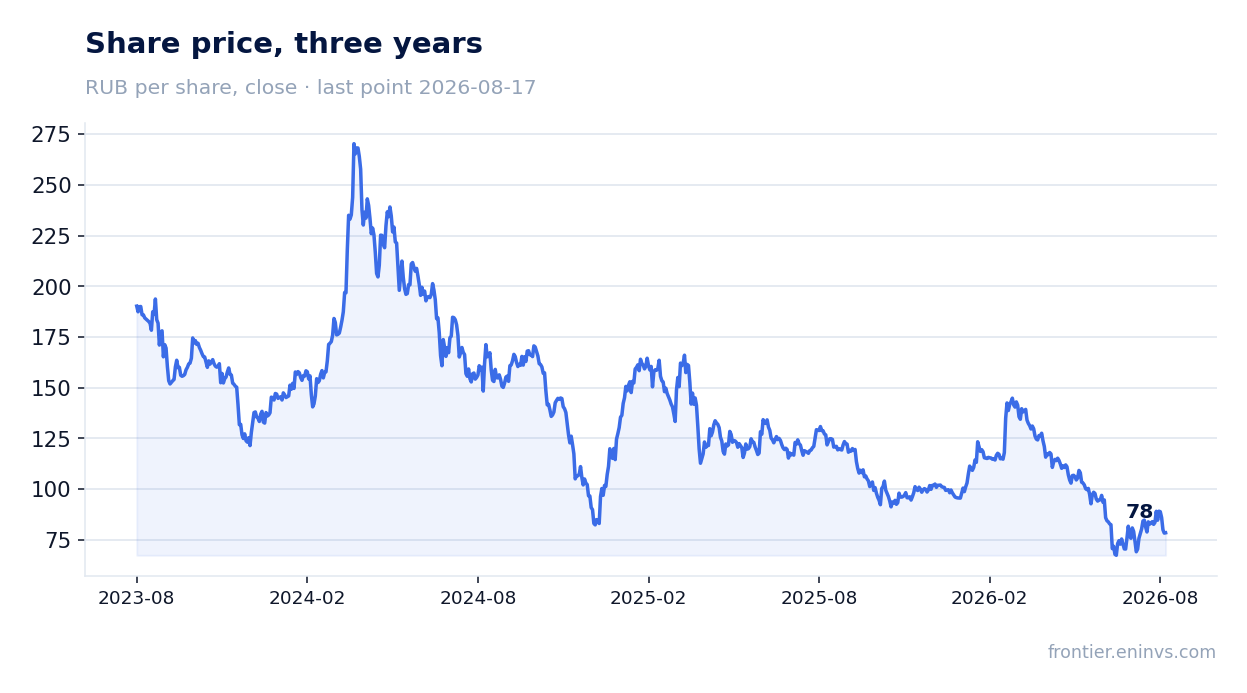
Over the last 12 months, Russneft paid RUB 13.38 per share, giving a yield of 17.2% at the current price. This is above the fair yield of 12.0% that we consider adequate for this issuer. The payout ratio to LTM profit is only 0.17, meaning the company distributes only a small part of profit.
Our model estimates the next payment at RUB 8.92 per share, corresponding to a forward yield of 11.1% – slightly below fair. Even with lower payments, the share remains attractive for income-oriented investors.
Portal model sees 260% upside
Our portal model, which re-prices EBITDA at current oil prices and applies a target EV/EBITDA multiple, shows the share has upside potential of +260% to fair value. This is the portal's own calculation, not a market consensus.
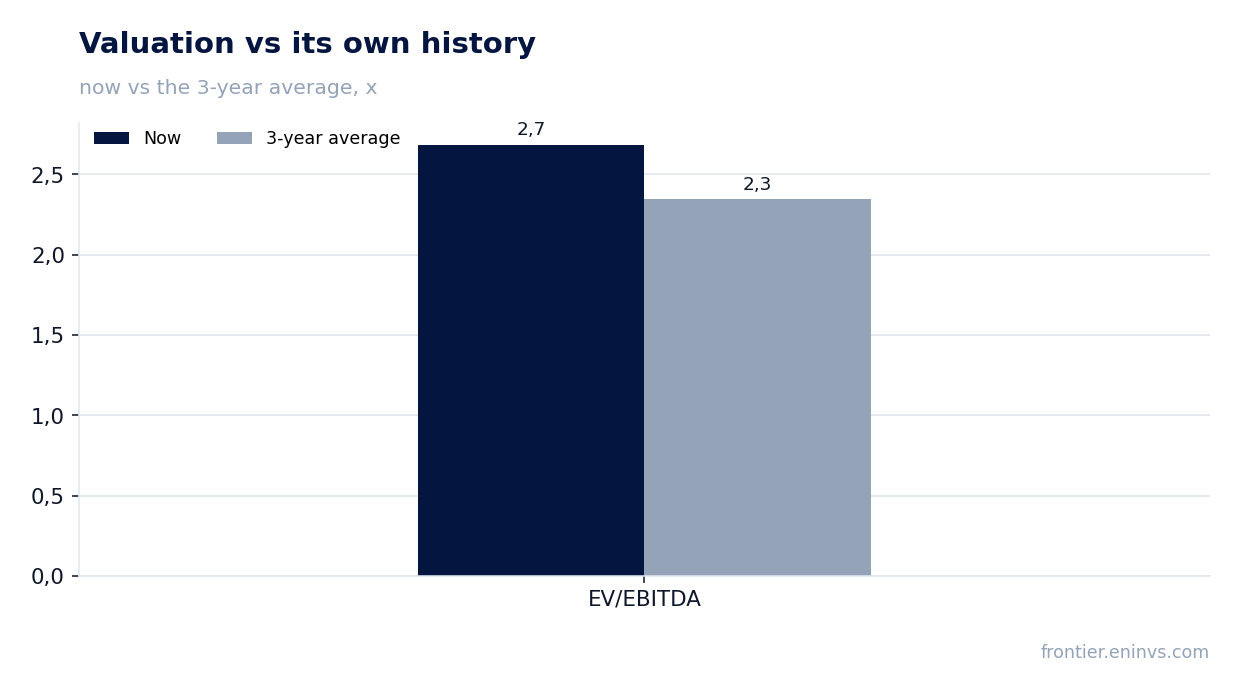
The current EV/EBITDA LTM is 2.72, which is below the three-year average (2.34 – the three-year average, but for comparison: the current multiple is above the average). However, the portal model accounts for higher oil prices that are not fully reflected in current share prices. The share trades at a P/E LTM of 0.88 – an extremely low valuation.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 24.6 bn ₽ |
| P/E (LTM) | 0.9 |
| EV/EBITDA (LTM) | 2.7 |
| P/B | 0.17 |
| Net debt / EBITDA (LTM) | 1.92 |
| Operating cash flow (LTM) | 21.8 bn |
| ROE | 21.1% |
| EV/EBITDA, 3-year average | 2.3 |
Bottom line
Russneft reported strongly: H1 EBITDA and net profit rose by a third, with margins reaching 27.5% and 13.2%, respectively. However, profit growth is not accompanied by cash generation – LTM operating cash flow is only RUB 21.8 bn versus RUB 30.9 bn EBITDA, and debt is rising. The auditor's qualified opinion on possible early loan repayment is a serious signal that the market has not yet priced in. At the same time, the valuation is extremely low: P/E of 0.88, EV/EBITDA of 2.72 versus a three-year average of 2.34, and a dividend yield of 17.2% above fair. The share looks attractive for a patient investor, but only if the company resolves its liquidity issue.
Open the company's financial profile RNFT →
See also: market overview · valuation map · stock screeners