Rosneft: revenue finally grew in Q2 after a year of declines, but profit stayed in the shadow of one-off charges
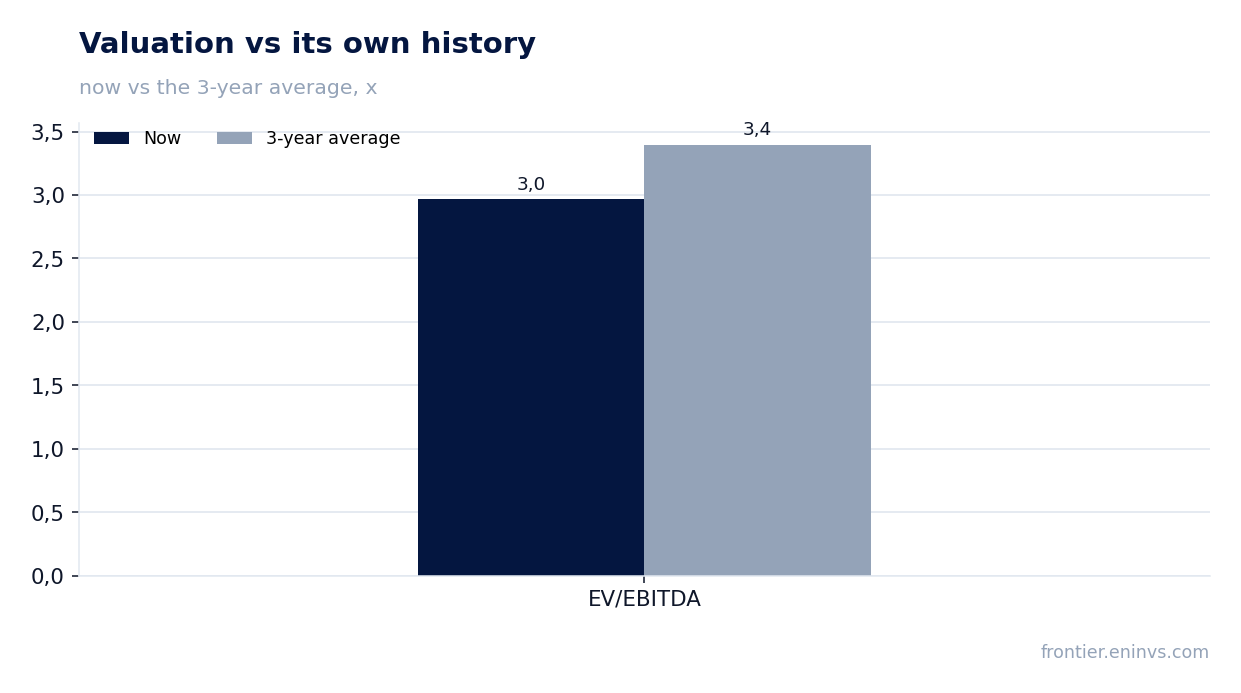
31 августа Роснефть раскрыла результаты за второй квартал 2026 года: выручка выросла на 14,0% год к году, до 2 257,0 млрд руб., EBITDA – на 27,4%, до 576,0 млрд руб., чистая прибыль – на 13,3%, до 85,0 млрд руб. Акция выглядит привлекательно: мультипликатор EV/EBITDA (3,04) ниже собственного трёхлетнего среднего (3,40), а модель портала оценивает потенциал роста в 63%.
Key takeaways
— Q2 revenue grew 14.0% – the first positive annual rate in five quarters
— EBITDA margin widened to 25.5% from 22.8% a year earlier, but net margin stayed at 3.8%
— Net profit rose only 13.3% to RUB 85.0 bn despite strong EBITDA
— Leverage of 1.54x LTM EBITDA is moderate, but absolute debt was flat over the year
— Dividend yield of 4.1% is far from the fair 10.5%, limiting appeal
— The portal's model sees 63% upside at the current price
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Revenue | 1 980 | 2 257 | +14.0% |
| EBITDA | 452 | 576 | +27.4% |
| Operating profit | 226 | 311 | +37.6% |
| Net profit | 75.0 | 85.0 | +13.3% |
| Operating cash flow | 551 | — | — |
| Capex | 387 | — | — |
| EBITDA margin | 22.8% | 25.5% | +2.7 pp |
| Net margin | 3.8% | 3.8% | +0.0 pp |
Q2 revenue grew 14.0% – the first positive annual rate in five quarters
In Q2 2026, Rosneft's revenue reached RUB 2,257.0 bn, up 14.0% year-on-year. This is the first positive annual rate after four quarters of decline: Q1 2026 was down 11.0%, Q4 2025 down 23.9%, Q3 2025 down 19.5%, and Q2 2025 down 23.9%.
Sequential dynamics are also positive: revenue rose from RUB 2,032.0 bn in Q1 2026. In the H1 report, revenue from oil, gas, petroleum products and petrochemicals was RUB 4,208 bn, close to the RUB 4,184 bn a year earlier, while ancillary services and other sales added RUB 81 bn versus RUB 79 bn.
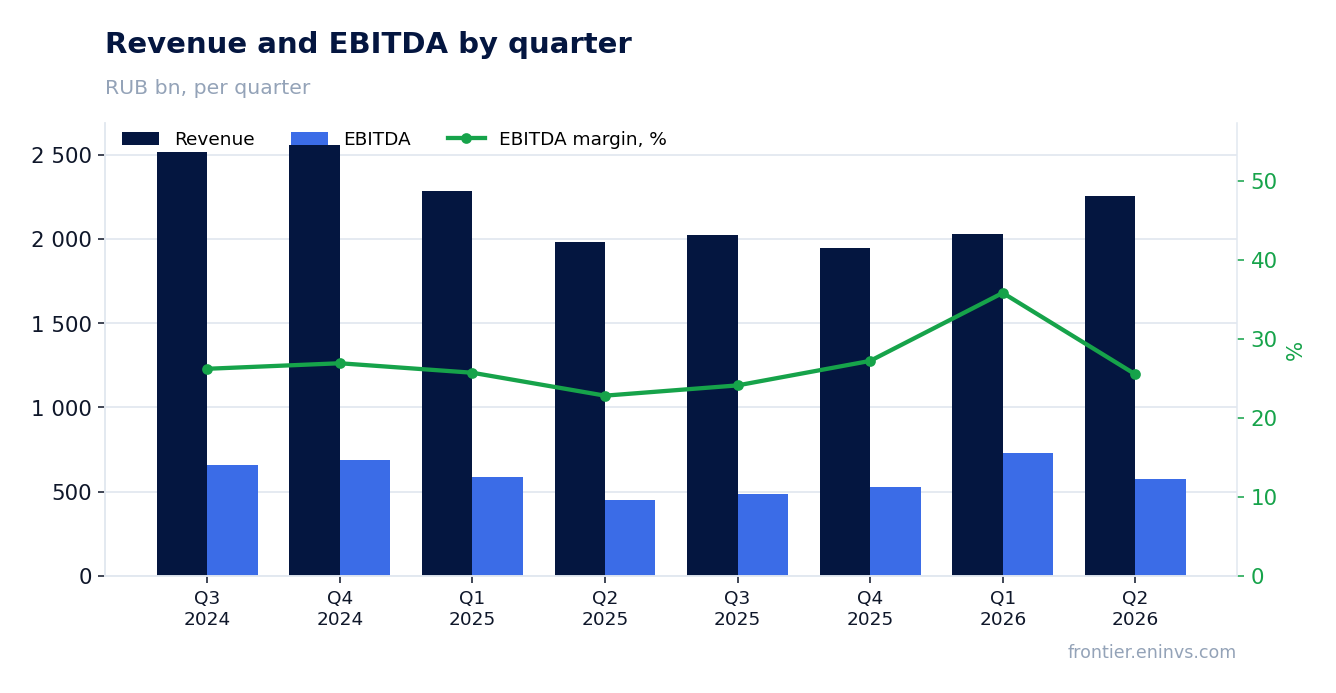
EBITDA margin widened to 25.5% from 22.8% a year earlier, but net margin stayed at 3.8%
Q2 EBITDA grew 27.4% year-on-year to RUB 576.0 bn, and the EBITDA margin widened to 25.5% from 22.8% in Q2 2025. This is a notable improvement in operational efficiency, especially given the modest revenue growth.
However, net margin stayed at 3.8% – exactly the same as a year earlier. The reason lies in the 'Other expenses' line: in H1 2026 they were RUB 195 bn versus RUB 14 bn in H1 2025, eating a large part of operating profit.
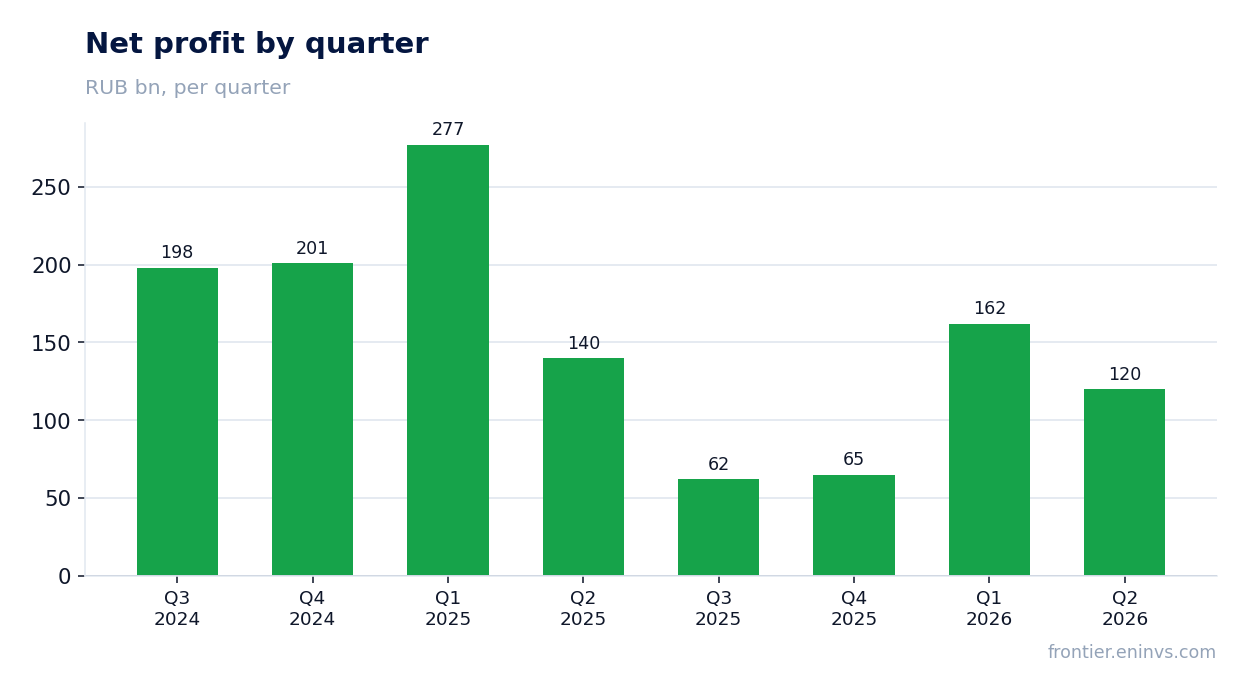
Net profit rose only 13.3% to RUB 85.0 bn despite strong EBITDA
Q2 net profit was RUB 85.0 bn, up 13.3% year-on-year. Growth is positive but much more modest than EBITDA dynamics, due to the aforementioned other expenses.
In H1 2026, net profit attributable to Rosneft shareholders was RUB 200 bn versus RUB 245 bn in H1 2025 – a decline of 18.4%. This means that on a cumulative basis profit is still falling, despite a strong second quarter.
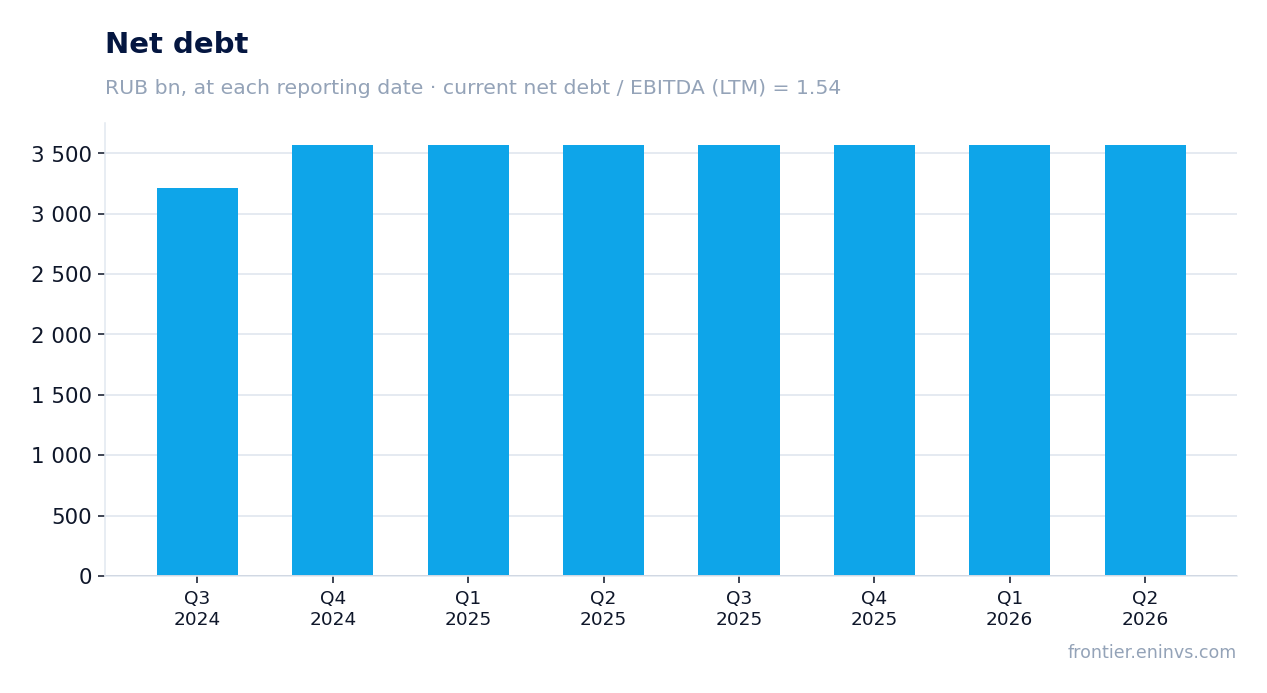
Leverage of 1.54x LTM EBITDA is moderate, but absolute debt was flat over the year
As of end-Q2 2026, Rosneft's net debt was RUB 3,572.4 bn, exactly RUB 0.0 bn more than at the previous reporting date and a year earlier. Leverage based on trailing twelve-month EBITDA is 1.54x, which looks moderate for a company of this scale.
In the balance sheet as of June 30, 2026, current liabilities are RUB 7,929 bn and non-current liabilities RUB 4,442 bn. Cash and cash equivalents are included in current assets (RUB 4,004 bn), but the exact amount is not disclosed in the condensed interim financial statements.
Dividend yield of 4.1% is far from the fair 10.5%, limiting appeal
Over the last 12 months, Rosneft paid RUB 13.83 per share, providing a yield of 4.1%. Our model estimates a fair yield for this name at 10.5% – more than double the current level.
With a payout ratio of 0.47 of profit, the company distributes less than half of net profit as dividends. The report states that on June 19, 2026, the shareholders' meeting approved dividends for 2025 of RUB 2.27 per share (RUB 21.6 bn in total), significantly below the RUB 14.68 per share a year earlier.
The portal's model sees 63% upside at the current price
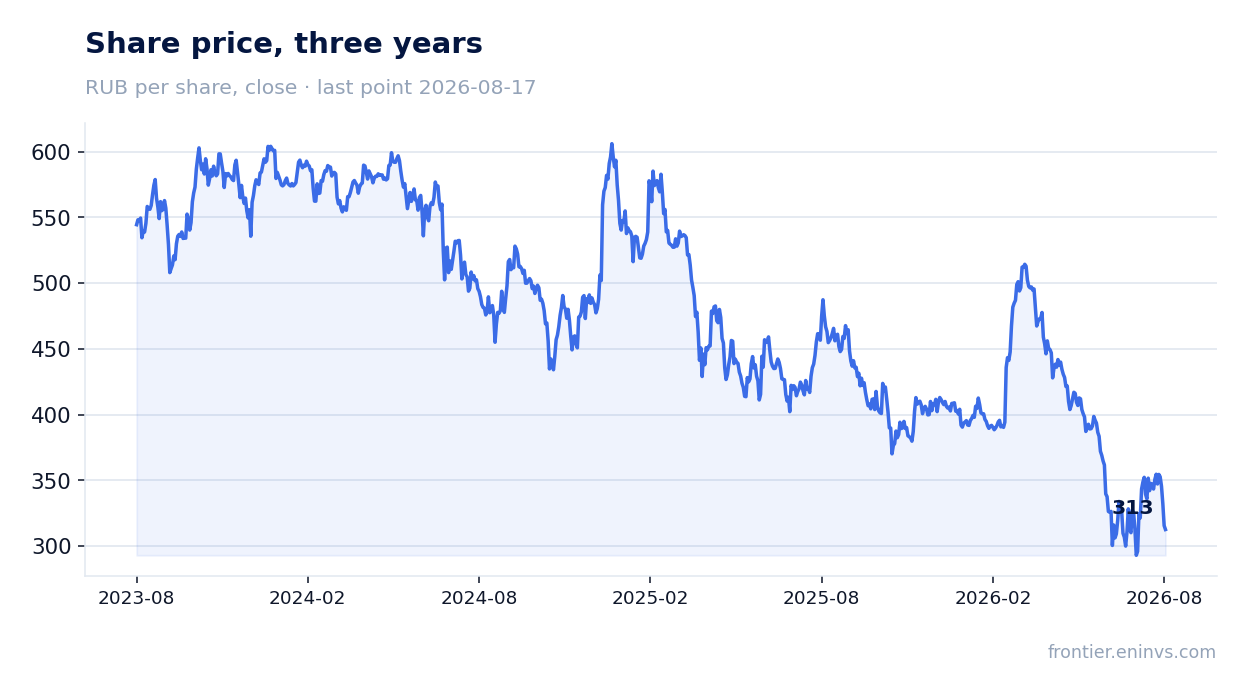
According to the portal's model, which re-prices EBITDA at current commodity prices and applies a target EV/EBITDA multiple, the fair value of the share is 63% above the current market price. This is significant upside potential based on operational metrics, not market consensus.
With a current market cap of RUB 3,492.6 bn and EV/EBITDA of 3.04 versus the three-year average of 3.40, the share trades at a discount to its own history. P/E LTM is 14.08, which also looks moderate for an oil company with growing revenue.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 3 493 bn ₽ |
| P/E (LTM) | 14.1 |
| EV/EBITDA (LTM) | 3.0 |
| P/B | 0.38 |
| Net debt / EBITDA (LTM) | 1.54 |
| ROE | 3.7% |
| Dividend yield (12m) | 4.1% |
| EV/EBITDA, 3-year average | 3.4 |
Bottom line
In Q2 2026, Rosneft delivered a strong operational result: revenue grew for the first time in a year, EBITDA margin widened to 25.5%, and leverage remained moderate. However, net profit is growing more slowly due to one-off other expenses, and the dividend yield is far from fair. The share trades at a discount to its own history, and the portal's model sees significant upside. Verdict – attractive: at the current price, upside potential outweighs risks, but realisation depends on whether positive revenue dynamics persist and other expenses normalise.
Open the company's financial profile ROSN →
See also: market overview · valuation map · stock screeners