Sovcombank: quarterly profit up fivefold, and it's not just a low-base effect
On August 14, Sovcombank released its Q2 2026 results: net interest income grew 69.1% YoY to RUB 64,775 million, and net profit surged 410.8% to RUB 25,576 million. Return on equity over the last twelve months reached 24.1%, and the share looks attractive after the report: at a P/E of 2.8 and with upside potential of +48% per the portal's model, the market has not yet fully priced in the improvement in net interest margin and loan book quality.
Key takeaways
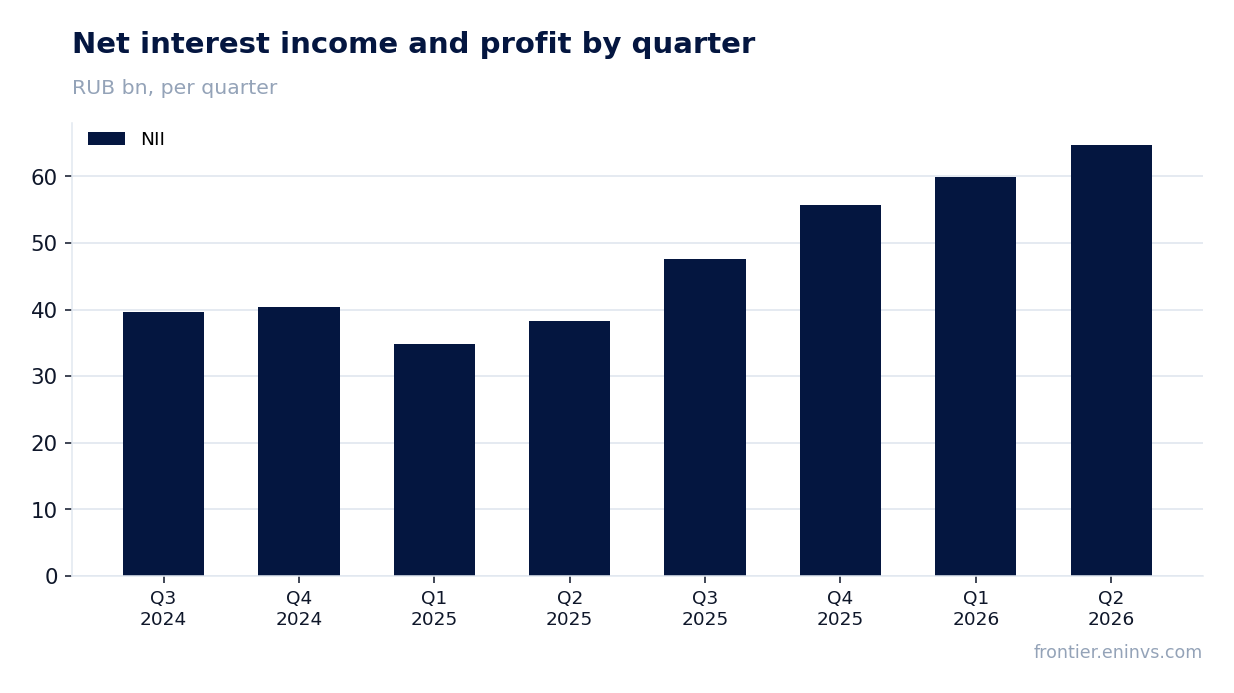
— Net interest income in Q2 grew 69.1% to RUB 64.8 billion – the best quarter in two years
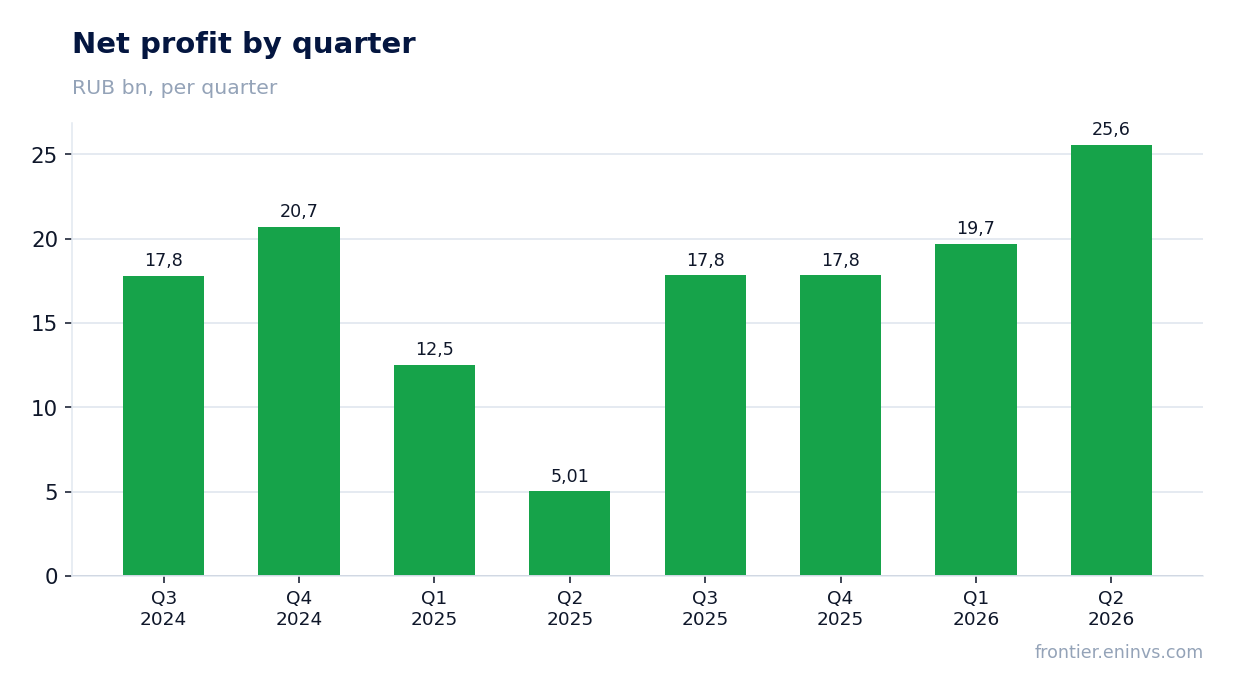
— Quarterly net profit reached RUB 25.6 billion – 5.1 times higher than a year earlier, driven by higher net interest income and lower provisions
— Net profit as a share of net interest income jumped from 13.1% to 39.5% – indicating a significant improvement in operating efficiency
— Return on equity over the last twelve months reached 24.1% – above the sector average and reflecting high capital efficiency
— Fee and commission income in Q2 rose 19.7% to RUB 13.9 billion, supported by bank guarantees and settlement services
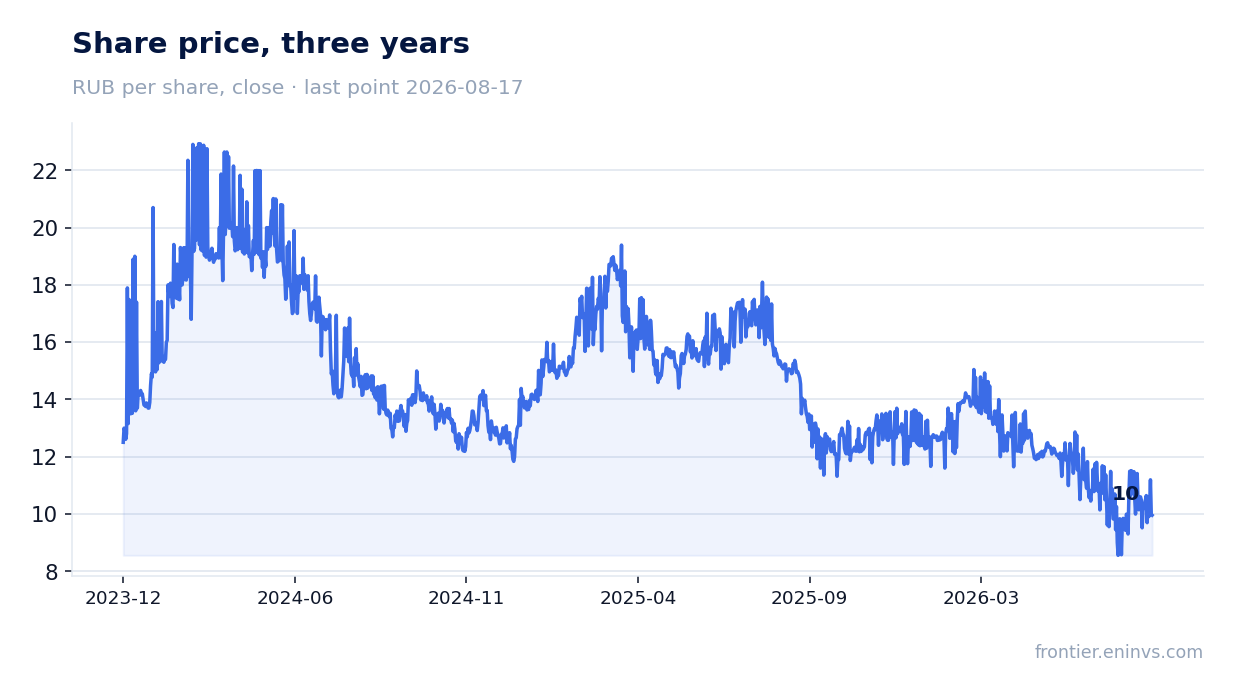
— The share price rose 9.1% on the release day but then corrected 2.9% – the market remains cautious despite strong results
— The portal's model values the share 48% above the current price, pointing to significant upside potential
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Net interest income | 38.3 | 64.8 | +69.1% |
| Net profit | 5.01 | 25.6 | +410.8% |
| Net margin | 13.1% | 39.5% | +26.4 pp |
Net interest income in Q2 grew 69.1% to RUB 64.8 billion – the best quarter in two years
In Q2 2026, Sovcombank's net interest income reached RUB 64,775 million, up 69.1% from the same period a year earlier. This is the highest quarterly figure in two years – the previous peak was in Q4 2025 (RUB 55,713 million).
The growth was driven both by higher interest income and lower interest expenses. Interest income rose 4.2% to RUB 177,678 million, while interest expenses fell 23.6% to RUB 110,877 million – indicating lower funding costs, especially important in a high-key-rate environment.
The key driver was net interest margin expansion: the bank now attracts funds cheaper than a year ago, while asset yields remain high. This is also visible in the half-year dynamics: H1 2026 net interest income grew to RUB 124,739 million from RUB 73,193 million in H1 2025.
Quarterly net profit reached RUB 25.6 billion – 5.1 times higher than a year earlier, driven by higher net interest income and lower provisions
Sovcombank's net profit in Q2 2026 reached RUB 25,576 million versus RUB 5,007 million in Q2 2025. The 5.1-fold growth was driven not only by net interest margin expansion but also by lower cost of risk: credit loss expenses for H1 fell from RUB 38,070 million to RUB 41,162 million, with elevated provisions in Q2 2025 related to portfolio quality.
For H1 2026, net profit reached RUB 45,278 million, more than double the H1 2025 result (RUB 17,543 million). Return on equity over the last twelve months reached 24.1% – a high figure confirming the bank's ability to generate profit on invested capital.
Importantly, the profit growth is not one-off: it rests on sustainable improvement in operating income and controlled provision expenses. Even without the low-base effect, the absolute quarterly profit is a record for the past two years.
Net profit as a share of net interest income jumped from 13.1% to 39.5% – indicating a significant improvement in operating efficiency
In Q2 2026, net profit amounted to 39.5% of net interest income – a year earlier this ratio was only 13.1%. This is not a margin or profitability ratio, but it clearly shows how efficiently the bank converts its core income into the bottom line.
The improvement was driven by a combination of factors: net interest margin expansion, lower cost of risk, and control over operating expenses. In H1 2026, personnel expenses grew only 9.9% to RUB 48,910 million, lagging behind revenue growth.
Such a significant efficiency gain is a key signal for shareholders: the bank is not only growing revenues but doing so with lower unit costs, which directly supports its ability to pay dividends.
Return on equity over the last twelve months reached 24.1% – above the sector average and reflecting high capital efficiency
Over the last twelve months (LTM), Sovcombank earned RUB 80,967 million in net profit against equity attributable to shareholders of RUB 445,503 million (as of June 30, 2026). This translates into a return on equity of 24.1% – a compelling figure compared with the Russian banking sector average.
High ROE also supports dividend potential: with a payout ratio of 0.18 of profit and a current share price of RUB 10.26, the model's next dividend estimate is RUB 0.56 per share, implying a forward yield of 5.7%. This is below the fair yield of 10.5% we consider adequate for this issuer, but the very existence of payouts at such profitability is a positive signal.
The bank's market capitalization is RUB 228,539.7 million, which, against LTM profit of RUB 80,967 million, gives a P/E of just 2.8 – an extremely low valuation for a business with ROE above 20%.
Fee and commission income in Q2 rose 19.7% to RUB 13.9 billion, supported by bank guarantees and settlement services
Sovcombank's fee and commission income in Q2 2026 reached RUB 13,932 million, up 19.7% from a year earlier (RUB 11,638 million). The main drivers were bank guarantees (RUB 6,913 million for the quarter) and settlement services (RUB 3,584 million).
For H1, fee and commission income grew to RUB 31,867 million from RUB 26,561 million in H1 2025. Growth was supported by the guarantee business, electronic trading platform income (RUB 4,426 million for H1), and securities issuance services (RUB 3,630 million).
Diversification into fee-based income reduces the bank's dependence on net interest margin and enhances the stability of financial results in periods of rate volatility.
The share price rose 9.1% on the release day but then corrected 2.9% – the market remains cautious despite strong results
On the release day, August 14, 2026, Sovcombank shares rose 9.1% to RUB 10.26 per share (the pre-release close). However, by August 17 the price had fallen 2.9%, indicating profit-taking and lingering investor caution.
Such dynamics are typical for the banking sector amid macroeconomic uncertainty: strong quarterly results often do not lead to sustained share price growth if the market prices in future deterioration.
Nevertheless, at a P/E of 2.8 and ROE of 24.1%, the share trades at a discount to its own historical multiples, creating potential for re-rating if current trends persist.
The portal's model values the share 48% above the current price, pointing to significant upside potential
According to the portal's model, based on the ratio of annualized earnings to market cap (ROE vs P/B), the fair value of Sovcombank's share is 48% above the current level. This implies that, given current return on equity and profitability, the share is significantly undervalued.
The model accounts for the fact that at an ROE of 24.1% and P/E of 2.8, the market values the bank with an excessive discount that does not match its actual profit-generation capacity. For comparison, the average P/E for the Russian banking sector typically ranges between 4 and 6, giving Sovcombank ample room for growth.
The share is included in our portal strategies: RU AI conviction (Claude), RU AI long-short (market-neutral), and RU Banks & financials (potential). This reflects alignment with fundamental selection criteria, though it is not a standalone buy argument.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 229 bn ₽ |
| P/E (LTM) | 2.8 |
| P/B | 0.59 |
| ROE | 24.1% |
Bottom line
Sovcombank's Q2 2026 report shows genuinely strong results: net profit grew 5.1-fold to RUB 25.6 billion, driven by net interest margin expansion and lower cost of risk. Net profit as a share of net interest income jumped from 13.1% to 39.5%, indicating a significant improvement in operating efficiency, while ROE over the last twelve months reached 24.1%.
Open the company's financial profile SVCB →
See also: market overview · valuation map · stock screeners