Ultimate Education: it can pay the coupons, but not the RUB 600mn due in July 2028; the 42% yield at a price of 79 is the price of a single redemption
Ultimate Education is a holding of seven online schools offering continuing education: Bang Bang Education, Fashion Factory, XYZ, Psychodemia, MAED, Moscow Digital School and MIIN. It has one bond issue, BO-P01, for RUB 600mn with a 19.75% monthly coupon, maturing on 14 July 2028, rated BBB(RU) by ACRA with a negative outlook (7 October 2025). The bond trades at 79% of par with a 42% yield, a spread of 2,700 bp over OFZ. Verdict: the company can service the RUB 117mn of annual coupons – 2025 EBITDA is RUB 330mn even after the decline – but revenue is down 32%, the net loss is RUB 180mn, cash is RUB 72mn, and with quotes at this level the RUB 600mn redemption in 22 months cannot be refinanced. This is not a coupon story; it is a bet on online education demand recovering by mid-2028.
The issuer's card on the portal, with financials by period, our credit analysis and all issues: Ultimate Education. Below are the calculations of Enhanced Investments based on the issuer's IFRS and RAS statements, the MOEX payment schedule and disclosures; where a figure is the authors' estimate, it is marked as such.
What happened to the business: revenue down 32%, EBITDA down 61%, profit turned into a loss in a single year
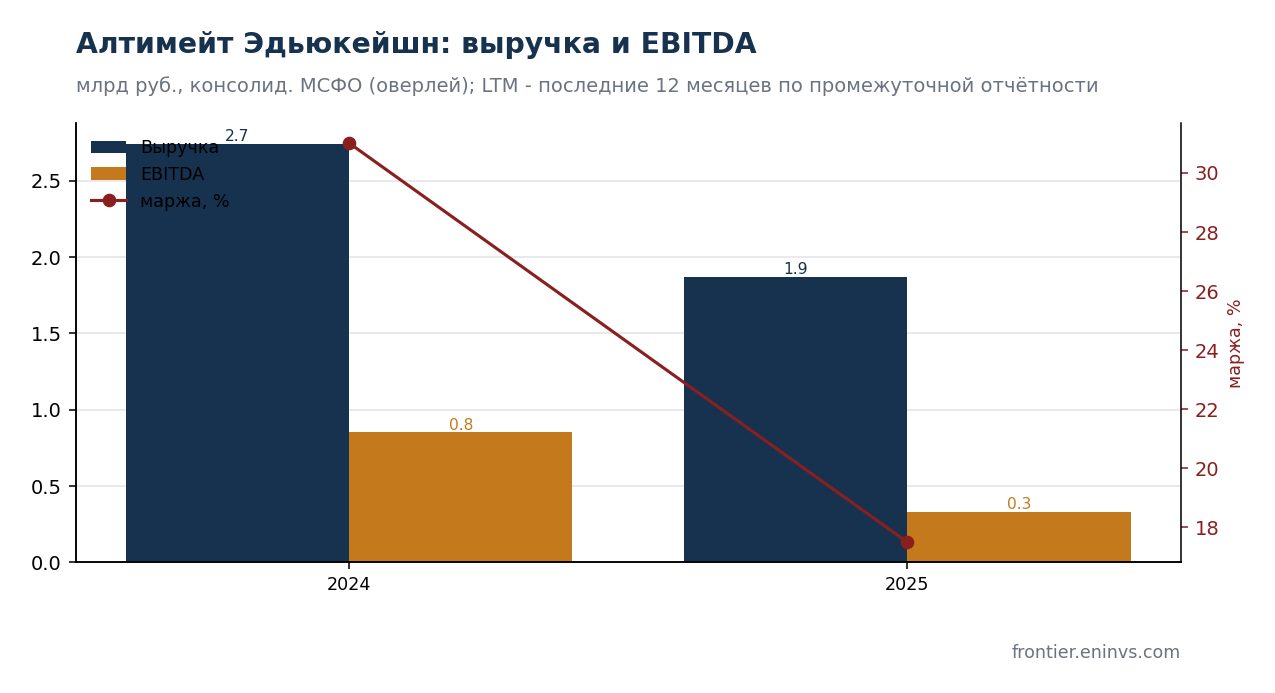
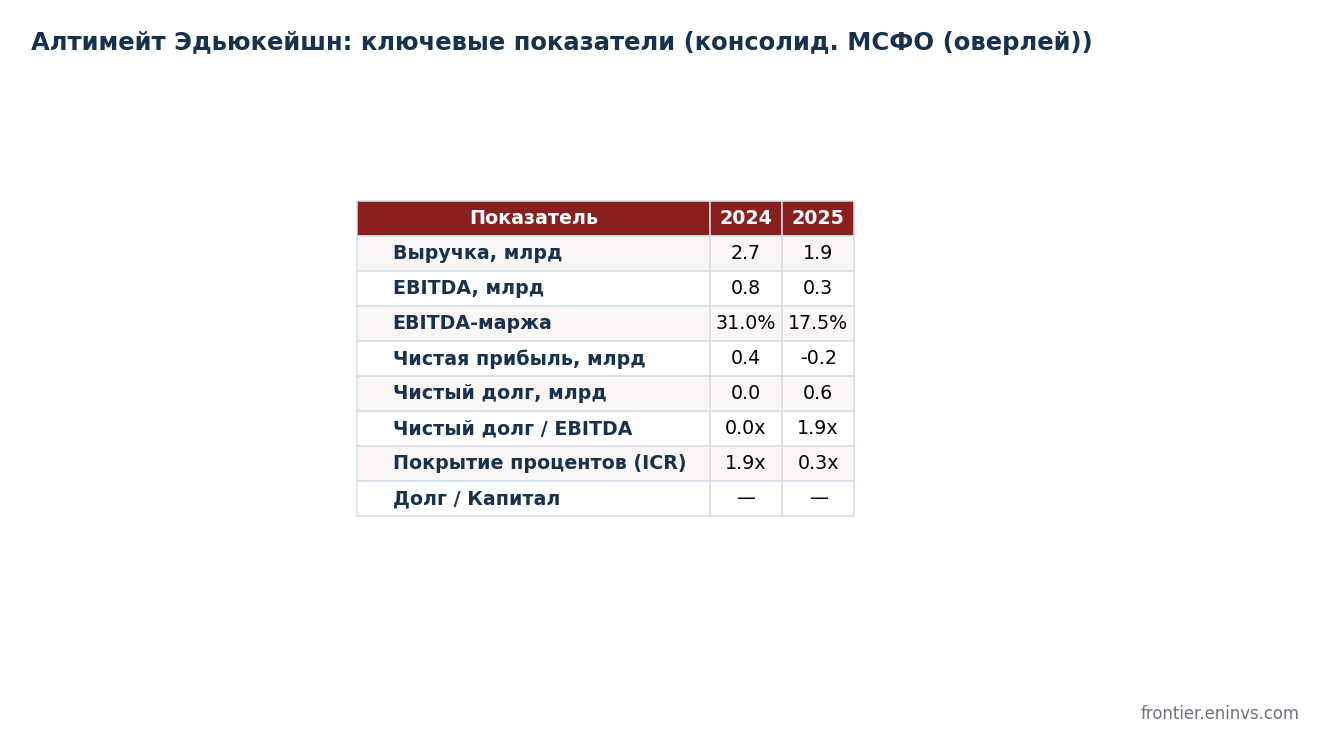
Fact (consolidated IFRS, 2025). Revenue was RUB 1.87bn versus RUB 2.74bn in 2024, operating profit RUB 118mn versus RUB 671mn, EBITDA by the company's definition RUB 327mn versus RUB 851mn, and the net loss RUB 180mn versus a profit of RUB 366mn. Finance costs of RUB 336mn are almost three times operating profit. According to Vedomosti, in summer 2025 the holding cut staff amid falling demand for online education.
Fact (ACRA, 7 October 2025). The agency affirmed BBB(RU) but changed the outlook from positive to negative because of weaker debt-service metrics as debt rose in 2025 and results came in below expectations. The agency's forecast: debt to FFO rises from 0.6x to 2.6x, interest coverage falls from 7.2x to 3.0x, and free cash flow is negative in 2024-2025. For 2026 ACRA assumes revenue recovers to RUB 2.0-2.2bn and debt to FFO of 2.2-2.4x, with no new borrowings or acquisitions.
Debt arrived with the bonds: net debt from zero to RUB 600mn, 1.85x EBITDA on a falling base
Fact. At the end of 2024 the group's net debt was close to zero (borrowings of RUB 196mn against cash of RUB 187mn). In July 2025 the company placed RUB 600mn of bonds, and at the end of 2025 loans and borrowings were RUB 669mn (of which bonds RUB 592mn), cash RUB 72mn, and net debt RUB 600mn, or 1.85x EBITDA. Operating profit covers interest only 0.35x: operating profit of RUB 118mn does not cover finance costs of RUB 336mn, and the gap is closed by amortisation of intangible assets inside EBITDA and, in effect, by working capital.
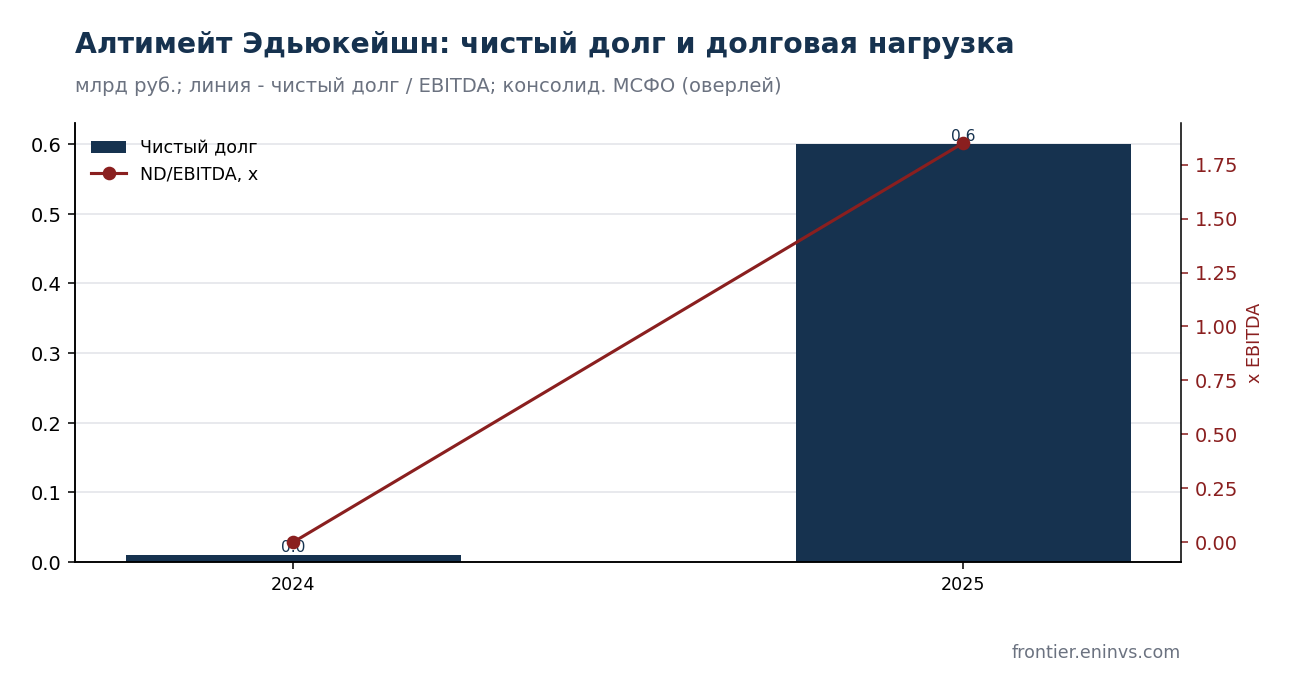
Authors' estimate. A leverage of 1.85x is moderate in itself; the danger is the trajectory. If 2026 repeats 2025, EBITDA falls to RUB 0.2-0.3bn and debt reaches 2-3x with no cash cushion. ACRA's forecast of a recovery to RUB 2.0-2.2bn of revenue is a forecast, not a fact; it should be checked against the parent company's half-year RAS statements, which are already queued for review on our portal.
What pays for it: RUB 10mn of coupons a month is easy, RUB 600mn on 14 July 2028 is the main and only question
Fact. The issue has no amortisation or put options: RUB 9.9mn of coupons monthly, RUB 117mn a year, and the whole par value on the redemption date, 14 July 2028. According to the parent company's RAS statements (the parent is a holding shell with revenue of RUB 32mn), cash at the end of 2025 was RUB 24mn and operating cash flow was minus RUB 72mn. Annual payment coverage in our screening is 0.2x, but that is a parent-company metric, while the coupons are paid by the group.
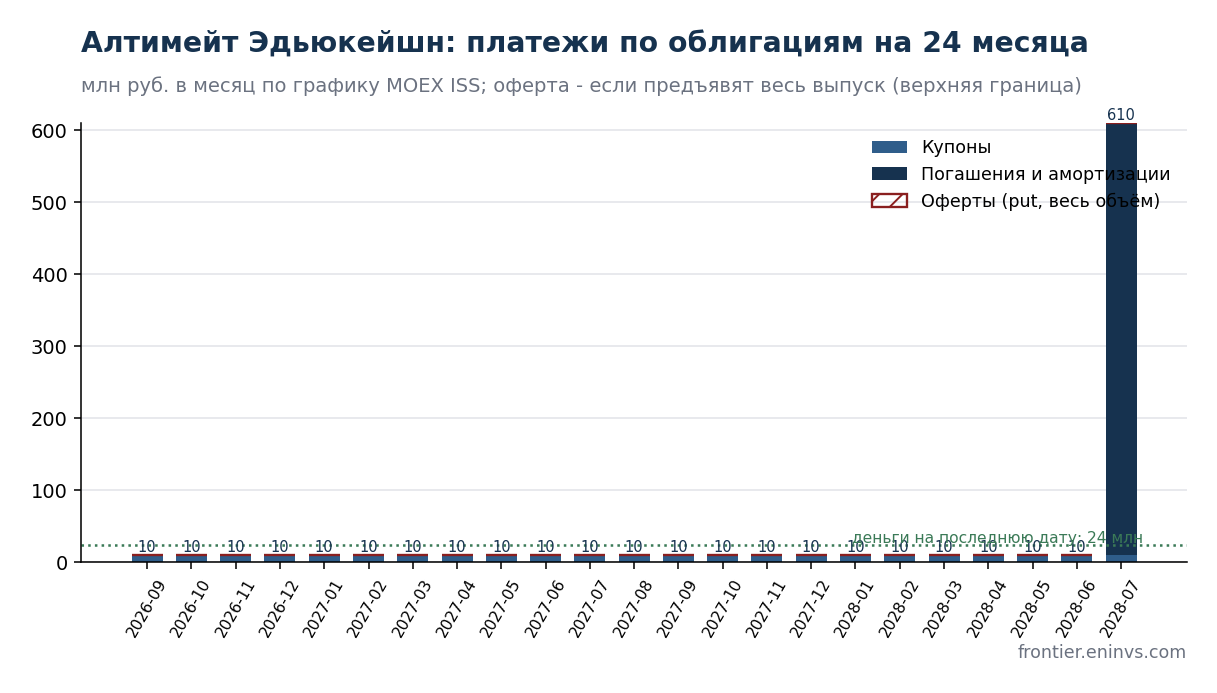
Authors' estimate. Even with EBITDA of RUB 330mn, the RUB 117mn of coupons is covered almost three times, and under ACRA's FFO forecast with 3x coverage, comfortably. The problem is the redemption budget: accumulating RUB 600mn in two years with negative free cash flow is impossible, and refinancing at a 42% secondary-market yield makes no economic sense. So by July 2028 the company must either bring EBITDA back to its 2024 level (RUB 0.85bn), or raise shareholder money or a bank loan, or go to a put offer with a restructuring.
Market: a 42% yield and a 2,700 bp spread mean the market is discounting the principal, not the coupon
Fact. The bond trades at 78.7-80% of par with a yield to maturity of 41.8-41.9% and a spread to OFZ of about 2,700 bp. Within a year of placement at 100 the quote lost a fifth. According to the Moscow Exchange index, the issuer has two unremedied disclosure violations (a board meeting in August 2025 and payments to holders in December 2025).
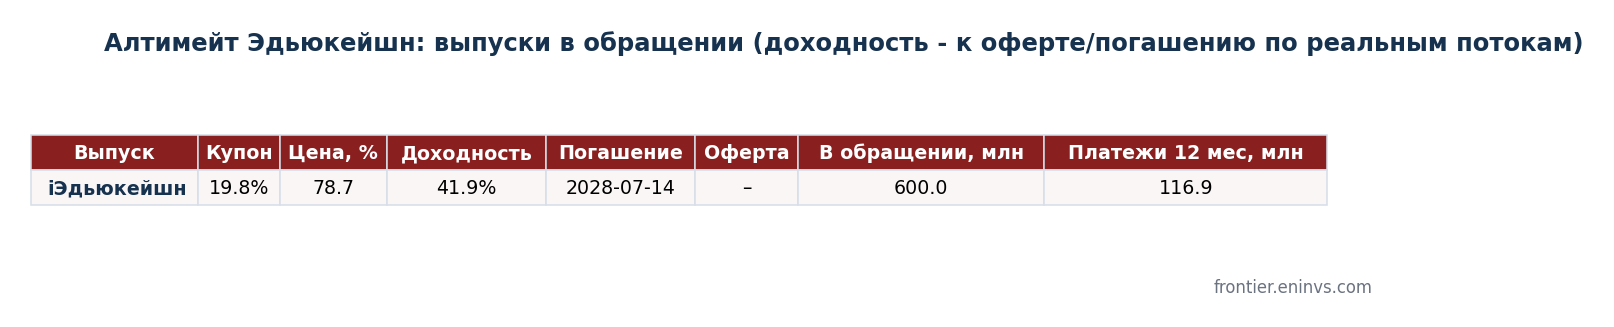
Authors' estimate. At a price of 79, the holder receives 25% of par in coupons until redemption plus 21% of discount. If the redemption goes through, the yield is 42% per year; if the company offers a restructuring that extends maturity by 2-3 years at the same coupon, the yield still stays in double digits. A total loss of the investment, given group assets that are 88% goodwill and RUB 1.5bn of intangibles (school brands, courses), is a scenario whose probability we assess as noticeable but not the base case: the business is operationally profitable.
Risks: demand, intangible assets and a single source of refinancing
- Demand for online education. Revenue fell by a third in a year amid a high key rate and tighter consumer lending; recovery depends on the central bank rate and on instalment plans for schools.
- Asset quality. RUB 0.78bn of intangibles and RUB 0.73bn of goodwill against equity of RUB 0.80bn; in a stress these assets cannot be sold at book value.
- ACRA's negative outlook. A downgrade to BBB- would take the bond outside the limits of some funds, which would add pressure on the price.
- Disclosure. Two unremedied violations and the status of a holding with no interim consolidated IFRS: half-year reporting is visible only through the parent company's RAS.
Conclusion: a speculative bet on recovery, not a bond for a coupon portfolio
By our methodology the group's 2025 credit quality is weak: interest coverage is 0.35x with moderate leverage of 1.85x, and leverage is rising only because the denominator is falling. Coupons are being serviced through 2028; the redemption question is open and depends entirely on whether demand returns. It makes sense to hold only as a small speculative position, with the understanding that exiting at 42% to maturity at a price of 79 is an estimate of the probability of restructuring, not a gift from the market. The first checkpoint is the 2026 reporting and the update of ACRA's rating in autumn 2026.
Update of 19 September 2026: after the issuer's half-year reporting the price fell to 71%, and the review was rebuilt on fresh data: [Ultimate Education at 71%](https://telegra.ph/Ultimate-Education-Bond-Review-Update-Sep-2026-09-19). That version corrects the group's intangible assets and equity (previously stated in error as 5.6 and 8.7bn).
Sources and caveats
- Consolidated IFRS of Ultimate Education LLC for 2025 (audited, e-disclosure), RAS of the parent company from the Federal Tax Service's GIR BO.
- ACRA, press release of 7 October 2025 (BBB(RU), outlook "negative").
- Coupon schedule: MOEX ISS; quotes: MOEX close on 3 September 2026; the Moscow Exchange disclosure-violation index.
- Vedomosti publications on staff cuts at the holding (July 2025), as context for demand.
Other issuer reviews and weekly analysis are on the Telegram channel Enhanced Investments @eninv; extended cards for all issuers are on the portal.
See also: market overview · valuation map · stock screeners