Bank VTB: Q2 2026 profit fell by a third even as net interest income doubled
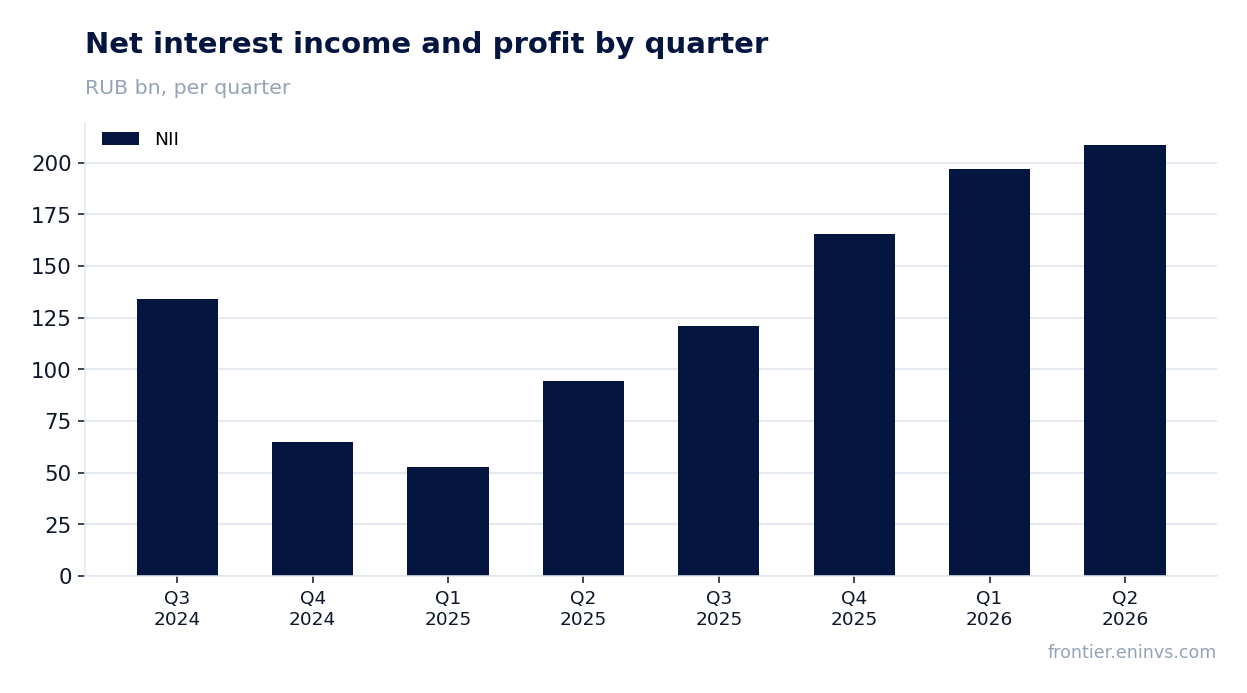
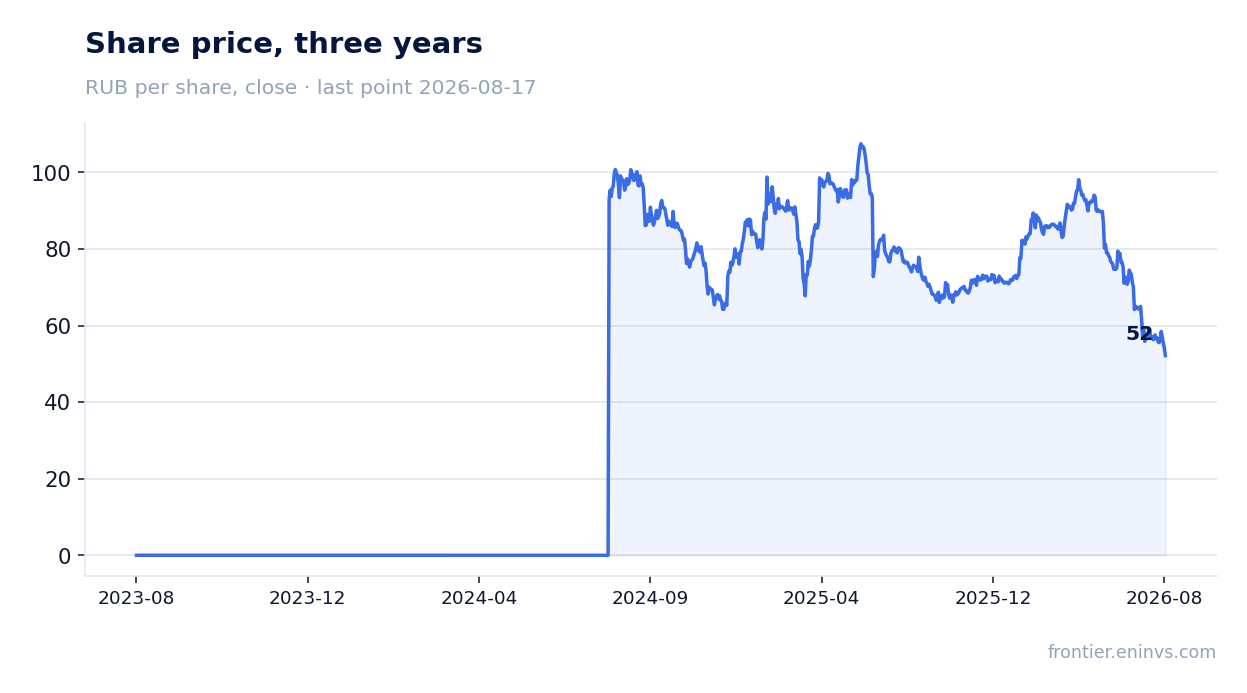
On 28 September Bank VTB reported results for the second quarter of 2026. Net interest income reached RUB 208.8 bn, up 121.7% year on year, but net profit fell by 33.6% to RUB 92.9 bn. Top-line growth decelerated from 274.1% in the first quarter. At the current price the share looks attractive for dividend-oriented holders: the forward dividend yield exceeds the key rate, and trailing twelve-month earnings put the P/E at 2.66.
Key takeaways
— Net interest income grew 121.7% year on year but decelerated from the first quarter
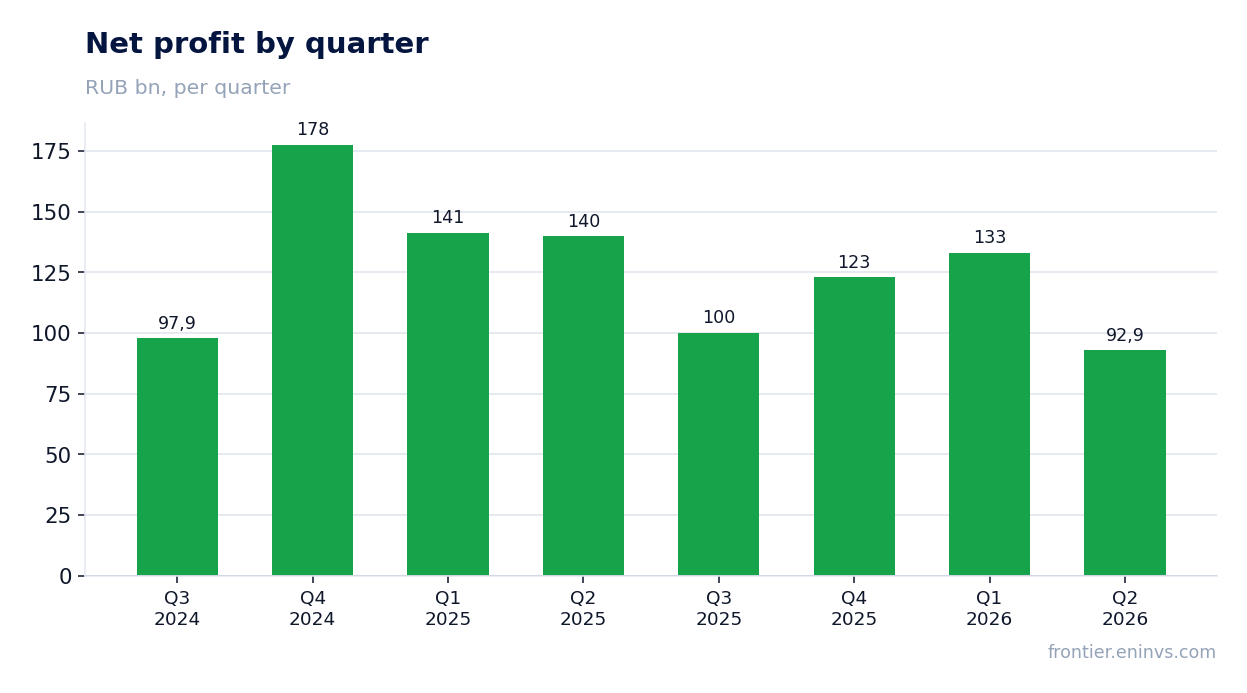
— Net profit fell 33.6% year on year, and its share of net interest income dropped to 44.5%
— Fee and commission income rose to RUB 95.7 bn, partially offsetting the pressure on profit
— Dividends paid over the last 12 months amounted to RUB 9.71 per share, a yield of 18.7%
— The current dividend yield exceeds the key rate of 14.0% but falls short of our fair yield estimate of 29.1%
— A P/E of 2.66 and ROE of 15.5% point to undervaluation, and the portal's model implies 65% upside
Attractiveness
Key figures, RUB bn
| Metric | Q2 2025 | Q2 2026 | Change |
|---|---|---|---|
| Net interest income | 94.2 | 209 | +121.7% |
| Net profit | 140 | 92.9 | -33.6% |
| Net margin | 148.5% | 44.5% | -104.0 pp |
Net interest income grew 121.7% year on year but decelerated from the first quarter
In the second quarter of 2026, Bank VTB's net interest income reached RUB 208.8 bn, up 121.7% year on year. This continues the recovery from a weak first half of 2025, when quarterly figures fell by 65.8% and 30.0%.
However, growth decelerated: in the first quarter of 2026 net interest income was up 274.1% year on year, while in the second it added 121.7%. The slowdown is explained by a higher comparison base in the second quarter of 2025 than in the first. The absolute level still hit a two-year high.
Fee and commission income also grew, to RUB 95.7 bn from RUB 72.9 bn a year earlier. This is the second most important revenue source after interest, and its contribution to total revenue increased.
Net profit fell 33.6% year on year, and its share of net interest income dropped to 44.5%
Net profit in the second quarter of 2026 was RUB 92.9 bn, down 33.6% from the same period last year. For comparison, a year earlier profit was RUB 139.9 bn.
The ratio of net profit to net interest income fell to 44.5% from 148.5% a year earlier. This is not a margin or profitability measure, but simply the relationship between two absolute figures. The decline reflects faster growth in expenses or one-off factors not disclosed in the provided data.
Despite the quarterly decline, profit over the last 12 months remains high at RUB 448.8 bn, giving a P/E of 2.66. This indicates that the market values the bank well below its current earnings power.
Fee and commission income rose to RUB 95.7 bn, partially offsetting the pressure on profit
Fee and commission income in the second quarter of 2026 reached RUB 95.7 bn, up 31.2% from RUB 72.9 bn a year earlier. This is the highest quarterly level in two years.
Growth in fee and commission income helps diversify revenue and reduces dependence on net interest income, which can be volatile. In the first quarter of 2026 fee and commission income was RUB 80.1 bn, meaning it grew 19.5% quarter on quarter in the second quarter.
The share of fee and commission income in total income (interest plus fees) was about 31.4% versus 43.6% a year earlier, as interest income grew faster. Nevertheless, the absolute contribution of fees increased.
Dividends paid over the last 12 months amounted to RUB 9.71 per share, a yield of 18.7%
Over the last 12 months Bank VTB paid dividends of RUB 9.71 per share, which at the current price gives a yield of 18.7%. This is significantly above the key rate of 14.0%.
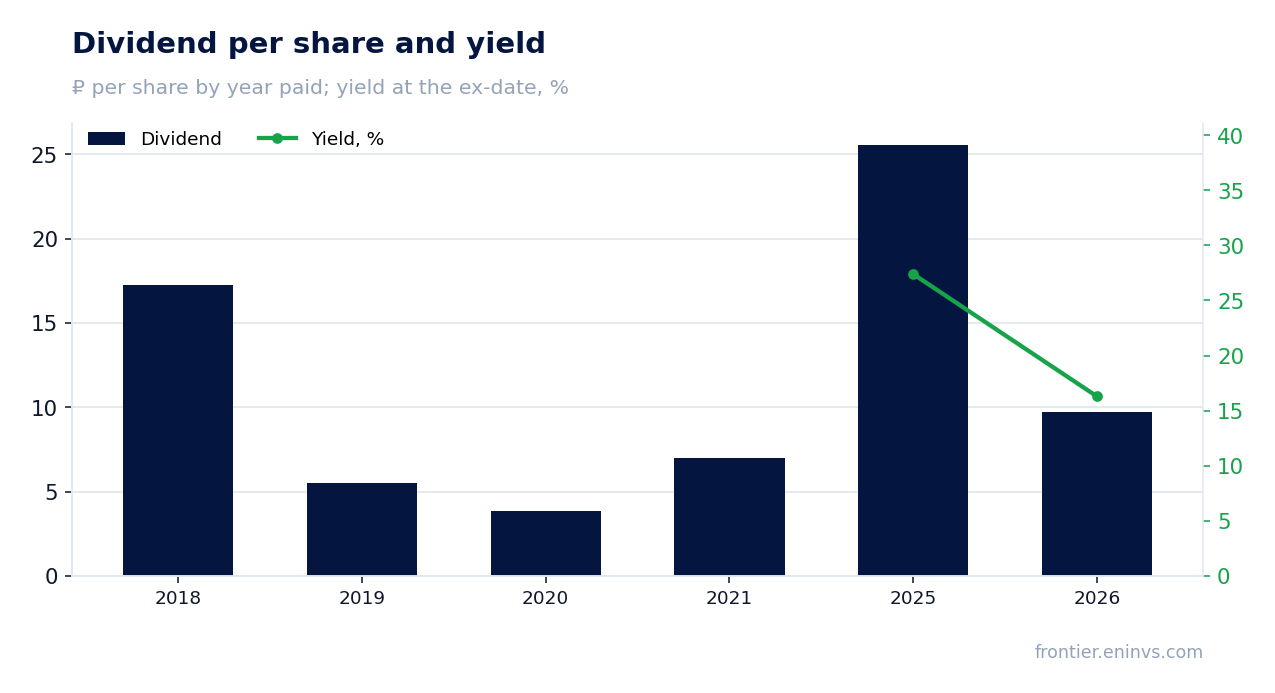
In 2026, RUB 9.71 per share has already been paid, and no further payouts are planned for this calendar year. In 2025, dividends were RUB 25.58 per share, giving a 27.4% yield at the ex-date. The reduction in 2026 payouts is explained by lower profit.
Our estimate of the fair dividend yield for this name is 29.1%. The current yield is below this level, which may indicate that the market expects a recovery in payouts or underestimates the risk of further cuts.
The current dividend yield exceeds the key rate of 14.0% but falls short of our fair yield estimate of 29.1%
The dividend yield of 18.7% exceeds the key rate of 14.0%, making the share attractive for conservative income-seeking investors. However, it is below our fair yield estimate of 29.1%.
Historical yields at the ex-date: 27.4% in 2025 and 16.3% in 2026. The decline in 2026 is due to both lower payouts and a higher share price before the ex-date. The current yield of 18.7% lies between these values.
The payout ratio is 0.16 of profit, which is a low level. This may mean that the bank has room to increase payouts if profit recovers, but also that current profit is insufficient to sustain high dividends.
A P/E of 2.66 and ROE of 15.5% point to undervaluation, and the portal's model implies 65% upside
The trailing twelve-month price-to-earnings ratio (P/E LTM) is 2.66. This is a very low level, suggesting that the market values the bank well below its current earnings. For comparison, the three-year average P/E is not provided, but the current value is clearly below typical levels for the banking sector.
Return on equity (ROE) over the last 12 months is 15.5%. This is a healthy figure, indicating efficient use of capital. With such an ROE and a P/E of 2.66, the share looks undervalued.
According to the portal's model, the upside to fair value is estimated at +65%. This is our own estimate based on comparing ROE and P/B. It is not a market consensus or a target price.
Valuation on the latest reported figures
| Metric | Value |
|---|---|
| Market cap | 1 193 bn ₽ |
| P/E (LTM) | 2.7 |
| P/B | 0.52 |
| ROE | 15.5% |
| Dividend yield (12m) | 18.7% |
Dividend per share, ₽, and yield at the ex-date
| Year paid | Dividend | Yield |
|---|---|---|
| 2018 | 17.27 | — |
| 2019 | 5.50 | — |
| 2020 | 3.87 | — |
| 2021 | 7.00 | — |
| 2025 | 25.58 | 27.4% |
| 2026 | 9.71 | 16.3% |
Bottom line
Bottom line: in the second quarter of 2026 Bank VTB showed strong growth in net interest and fee income, but net profit fell by a third due to faster growth in expenses or one-off factors. The dividend yield of 18.7% exceeds the key rate but is below our fair estimate of 29.1%. The share trades at a P/E of 2.66 and ROE of 15.5%, and the portal's model implies 65% upside. For dividend-oriented holders the share looks attractive, but the key question is whether the bank can restore profit and return dividends to previous levels.
Open the company's financial profile VTBR →
See also: market overview · valuation map · stock screeners