VTB 3Q 2026: net income RUB 182 bn, but more than half came from one-off income, and the RUB 87 share issue is still ahead
VTB is Russia's second-largest bank, with assets of RUB 39.1 trn and the state as controlling shareholder. On 30 October 2026 the bank published IFRS results for 3Q and 9M 2026. The share trades at RUB 57.64 (Moscow Exchange, 30.10.2026, 13:52 Moscow time), market capitalisation is RUB 745 bn on 12.93 bn shares. The share count nearly doubled this spring: the state converted its preferred shares into ordinary ones.
Verdict: neutral. Quarterly net income rose 1.8 times to RUB 182.3 bn, return on equity was 24.8%. But RUB 122.5 bn of the RUB 231.9 bn pre-tax profit came from securities revaluation, FX operations and the sale of subsidiaries. The share trades at 0.29x book value, and the 2025 dividend (RUB 9.71) gave 16.8% at the current price. But the 2026 dividend is limited by capital (a 0.5 pp buffer over the minimum), and a RUB 300-400 bn share issue will dilute shareholders by about a quarter. Our weighted estimate of the total return to end-2027 including dividends is +20%, about the return to require with the key rate at 14%.
- 2026 dividend: RUB 9.2 per share (16% of the price) with a 25% payout and a RUB 300 bn share issue; RUB 18.3 with the 50% payout of the dividend policy (authors' calculation).
- Net income RUB 182.3 bn (+82%), but the core – net interest and fee income less expenses and provisions – delivered RUB 109.4 bn before tax (authors' calculation).
- Net interest income +81.5% to RUB 219.8 bn: the margin rose from 1.5% to 2.7% as funding costs fell.
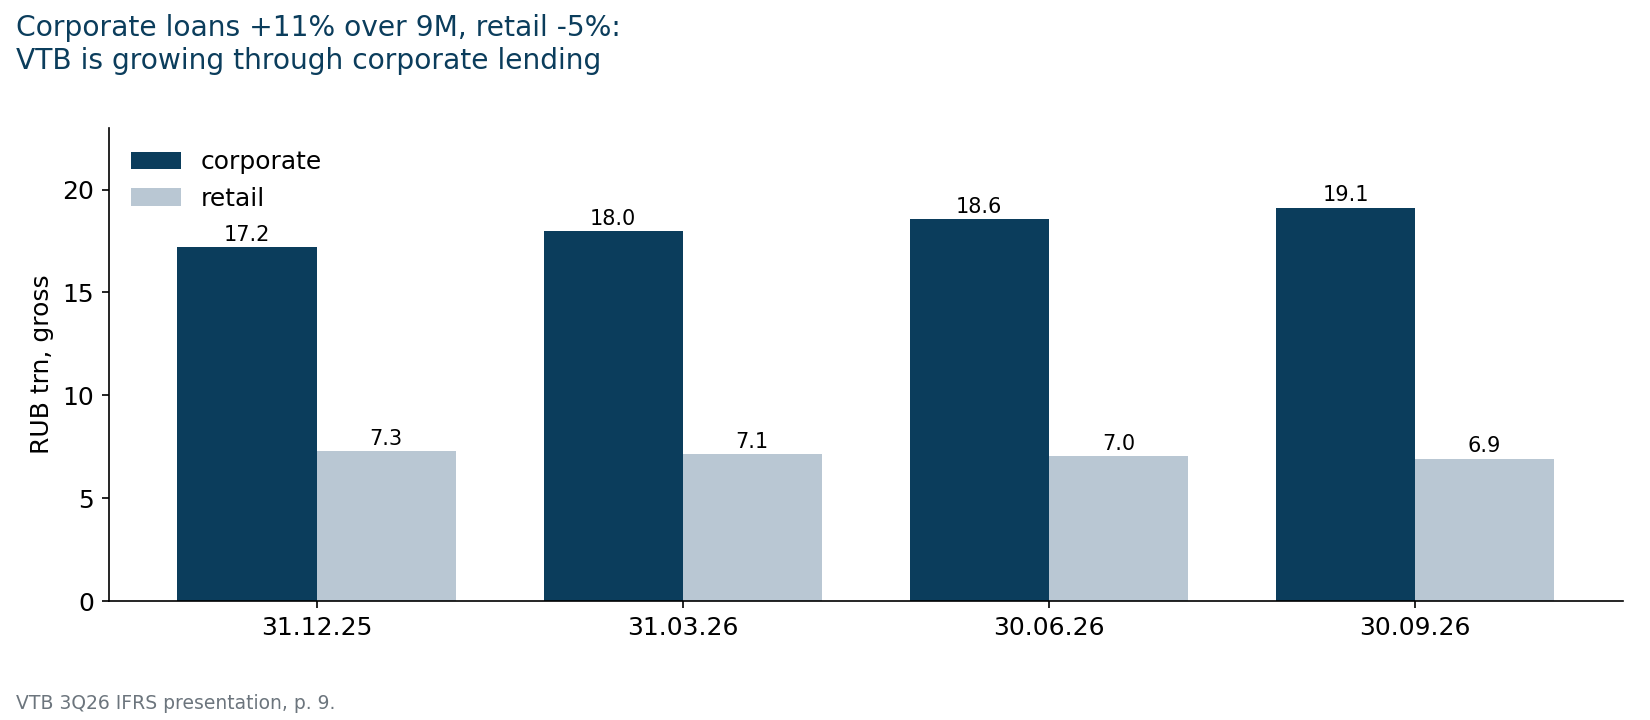
- Corporate loans +11% over 9M, retail -5%; cost of risk 1.0%, 90+ day NPLs 3.6%.
- The N20.0 ratio is 10.5% against a 10.0% minimum with buffers: a 25% payout costs 0.6 pp, a RUB 300 bn share issue would add about 1.2 pp.
- The RUB 600 bn full-year guidance is confirmed; it requires RUB 192.5 bn in 4Q, more than in 3Q with its one-off income.
Net income RUB 182 bn: the core delivered RUB 109 bn before tax, the rest came from securities, FX and disposals
| Metric, RUB bn | 3Q 2026 | 3Q 2025 | Change | 9M 2026 | Change |
|---|---|---|---|---|---|
| Net interest income | 219.8 | 121.1 | +81.5% | 625.4 | +133.4% |
| Net fee and commission income | 102.4 | 80.6 | +27.0% | 278.2 | +23.0% |
| Other operating income | 122.5 | 29.3 | +318% | 230.8 | -29.2% |
| Provisions for impairment | -65.2 | -11.4 | 5.7 times | -188.5 | +55.5% |
| Staff and administrative expenses | -147.6 | -134.1 | +10.1% | -433.5 | +13.7% |
| Profit before tax | 231.9 | 85.5 | +171% | 512.4 | +61.3% |
| Net income | 182.3 | 100.0 | +82.3% | 407.5 | +7.0% |
| Earnings per share, RUB | 13.4 | 16.3 | -17.8% | 36.5 | -42.8% |
| Return on equity (ROE) | 24.8% | 14.5% | +10.3 pp | 19.1% | +0.5 pp |
A bank has no "revenue" or "EBITDA". We define core profit as net interest and fee income less operating expenses and provisions. In 3Q that is 219.8 + 102.4 - 147.6 - 65.2 = RUB 109.4 bn before tax (authors' calculation). The core has grown for three quarters in a row: RUB 77.8 bn in 1Q, RUB 94.4 bn in 2Q.
The remaining RUB 122.5 bn of pre-tax profit is other income. The income statement shows what it consists of:
- RUB 68.2 bn – gains on securities and derivatives at fair value (RUB 13.3 bn a year ago);
- RUB 36.3 bn – FX and precious metals operations (RUB 17.3 bn a year ago);
- RUB 24.6 bn – gains on the disposal of subsidiaries and associates (RUB 4.8 bn a year ago). The bank does not disclose which companies were sold.
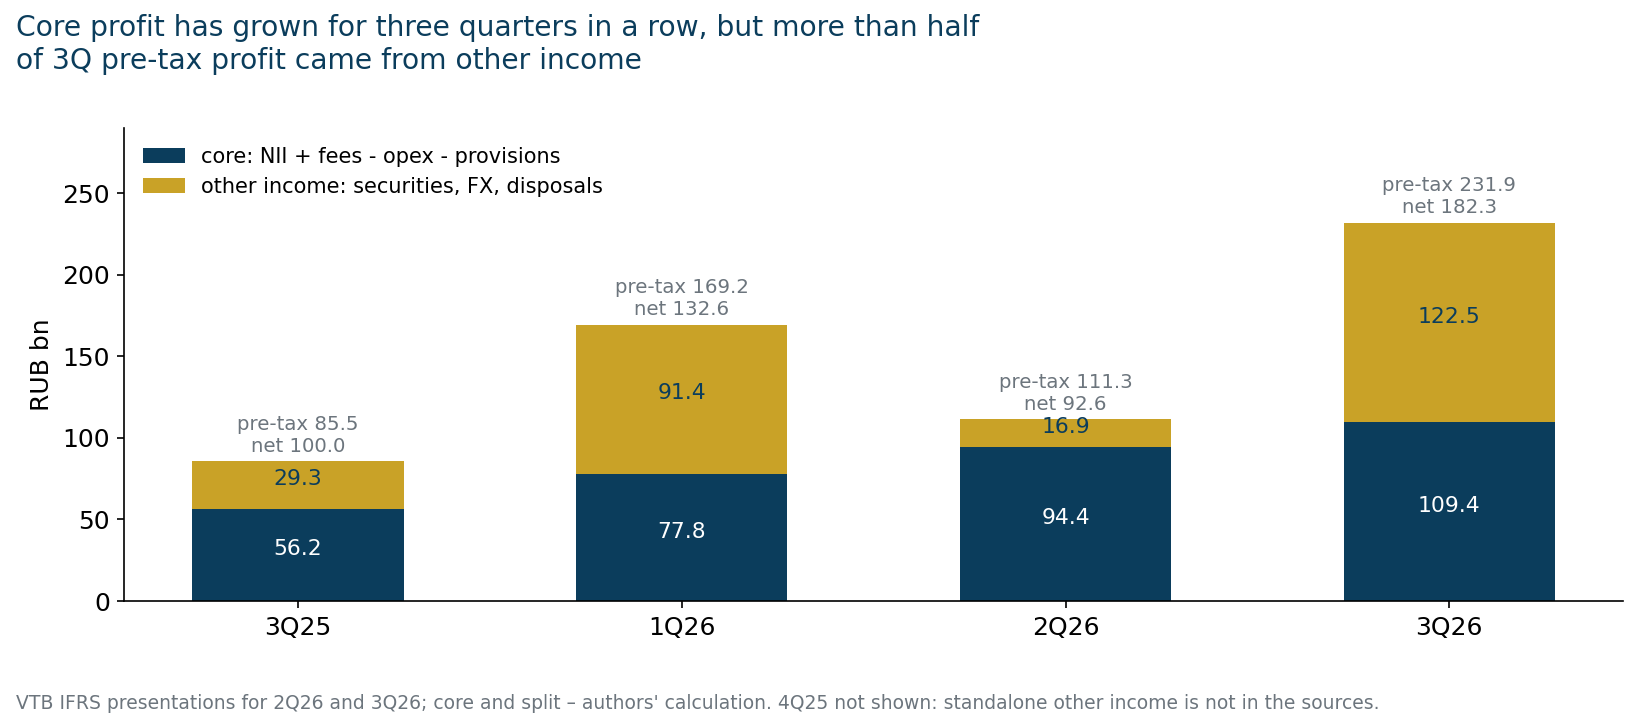
VTB's other income swings from quarter to quarter: RUB 91.4 bn in 1Q, RUB 16.9 bn in 2Q and RUB 122.5 bn in 3Q. So the 24.8% quarterly ROE should not be extrapolated to the full year: for 9M it is 19.1%.
Quarterly earnings per share fell 17.8% to RUB 13.4 even though net income rose 82%. This spring the state converted its preferred shares into 6.3 bn ordinary shares, and the number of shares outstanding rose from 5.4 bn to 12.8 bn. Previously part of the profit went to the preferred shares through their dividends. Now all profit is shared by ordinary shares, but there are twice as many of them.
The net interest margin nearly doubled in a year, but falls short of the 3% guidance
Net interest income rose 81.5% to RUB 219.8 bn. The reason is lower rates. Interest expense fell 20.1% year on year to RUB 892.1 bn: the cost of liabilities dropped from 14.4% to 10.6%. Interest income fell less, by 10.1%: the yield on assets declined from 15.3% to 13.5%. The net interest margin (the gap between asset yields and funding costs, relative to assets) rose from 1.5% to 2.7%.
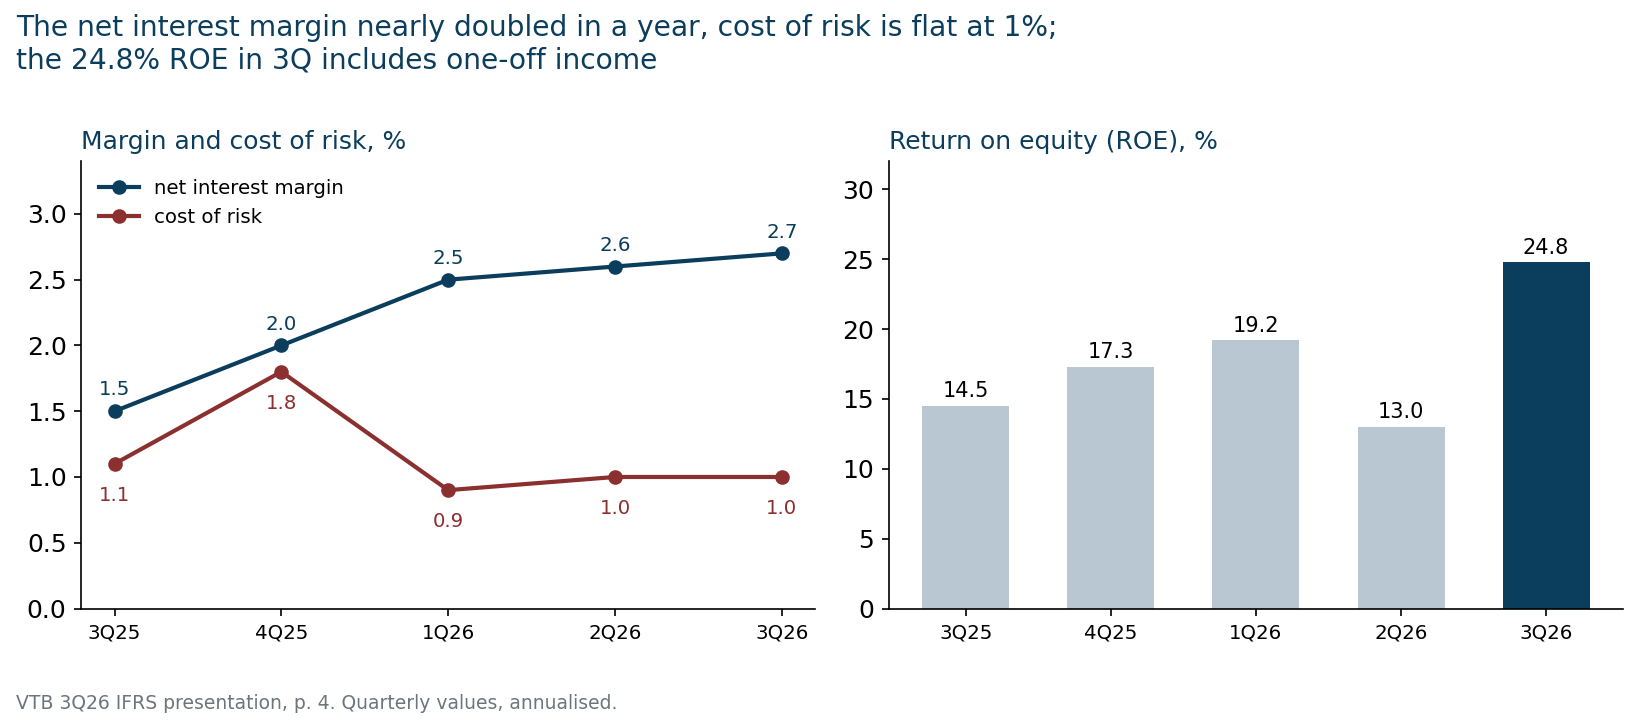
The bank guides to a 2026 margin of about 3%. For 9M it is 2.6%, in 3Q 2.7%. To reach 3% for the year, the 4Q margin would need to be about 4% (authors' calculation). The bank did not change this guidance in July. We expect 2.7% for the year.
Fee and commission income rose 27% to RUB 102.4 bn. Over 9M growth was 23% against guidance of about 20%. Settlement and cash operations account for almost three quarters of fees.
Loans: corporates +11%, retail -5%, cost of risk 1%
The gross loan book grew 6.3% over 9M to RUB 26.0 trn. Corporates drove the growth: the corporate book rose 11.2% to RUB 19.1 trn. Loans to construction (+17%), oil and gas (+15%) and metals (+12%) grew the most. The retail book shrank 5% to RUB 6.9 trn: consumer loans and credit cards -10%, mortgages -3%.
Cost of risk in 3Q was 1.0% of loans, the same as in 2Q: 0.6% for corporates and 2.0% for retail. The share of loans more than 90 days overdue rose from 3.5% to 3.6%. Over 9M non-performing corporate loans grew 12%, retail 2%. Provisions cover non-performing loans 1.51 times. The full-year guidance (about 1.1%) is on track so far.
Customer funds grew 1.7% over 9M to RUB 28.4 trn: corporates +4.3%, individuals -0.8%. Loans are growing faster than deposits. In March and June VTB sold previously issued bonds backed by its own loans (securitisation): their value was RUB 259.6 bn at 30 September. According to the bank, this added 0.3 pp to the capital adequacy ratio.
Capital: a 0.5 pp buffer over the minimum, and this is the main limit on dividends
The group's N20.0 capital adequacy ratio was 10.5% on 1 October. The minimum with buffers is 10.0%, and the bank's year-end guidance is at least 10.5%. Over 9M the ratio rose from 9.8% by 1.5 pp from profit, and the 2025 dividend took off 0.5 pp. The N1.1 core capital ratio is 5.8% against a 4.5% minimum. At 5.125% the write-down clause on subordinated bonds is triggered, 0.7 pp away.
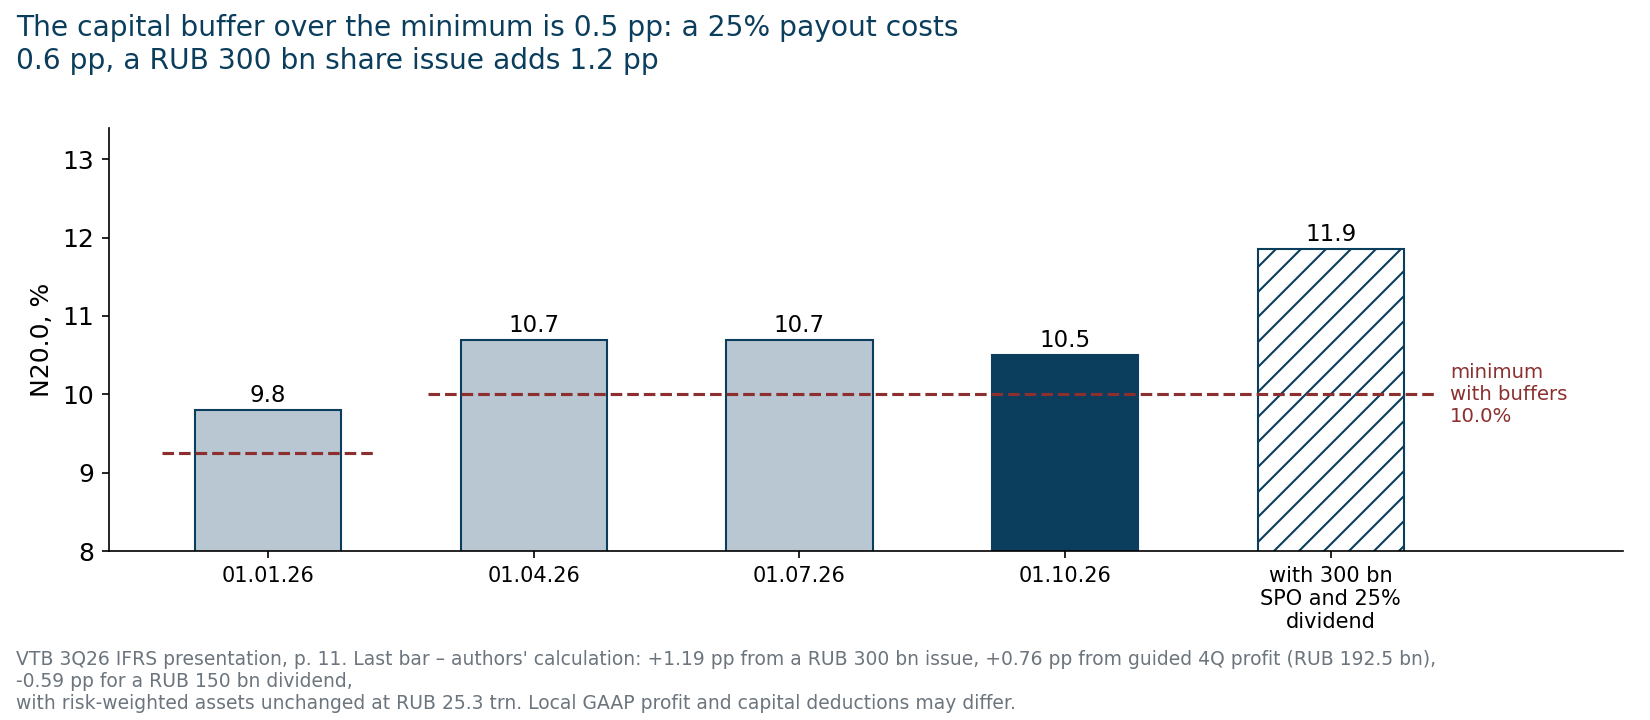
Risk-weighted assets are RUB 25.3 trn, so 0.1 pp of the ratio corresponds to RUB 25 bn of capital (authors' calculation). A 25% payout on 2026 profit (RUB 150 bn) costs about 0.6 pp, a 50% payout 1.2 pp. Guided 4Q profit will add about 0.75 pp, a RUB 300 bn share issue about 1.2 pp. Without the share issue, a 50% payout would take the ratio almost to the minimum. So the 2026 dividend depends on whether the share issue goes ahead.
The RUB 600 bn guidance requires RUB 192.5 bn in 4Q
| VTB 2026 guidance (July, confirmed in October) | Guidance | 9M 2026 |
|---|---|---|
| Net income | about RUB 600 bn | RUB 407.5 bn |
| Return on equity | about 20% | 19.1% |
| Loan growth | 5% (corporates +10%, retail decline of more than 5%) | +6.3% (+11.2% and -5.0%) |
| Net interest margin | about 3% | 2.6% |
| Cost of risk | about 1.1% | 1.0% |
| Fee income growth | about 20% | +23% |
| Cost/income | below 40% | 38.2% |
| N20.0 at year-end | at least 10.5% | 10.5% |
According to VTB first deputy chairman Dmitry Pyanov (Interfax, 30.10.2026), the RUB 600 bn guidance is confirmed, and 2027 profit will be no lower. For RUB 600 bn, 4Q has to deliver 600 - 407.5 = RUB 192.5 bn. That is more than RUB 182.3 bn in 3Q, when RUB 122.5 bn of pre-tax profit came from other income. If the core stays at the 3Q level (RUB 109.4 bn) in 4Q and tax is 21%, other income would need to be about RUB 134 bn (authors' calculation). Bonds gain value when rates fall, so this is possible. But the guidance relies on market income the bank does not control.
Dividend: RUB 9.71 for 2025, RUB 8.6 to 23 for 2026
Under its dividend policy VTB pays 50% of IFRS net income. For 2025 the bank paid out 25%: RUB 9.71 per share, RUB 125.5 bn in total. That is 16.8% of the current price, above the 14% key rate. There is no decision on the 2026 dividend yet; payment will come in summer 2027.
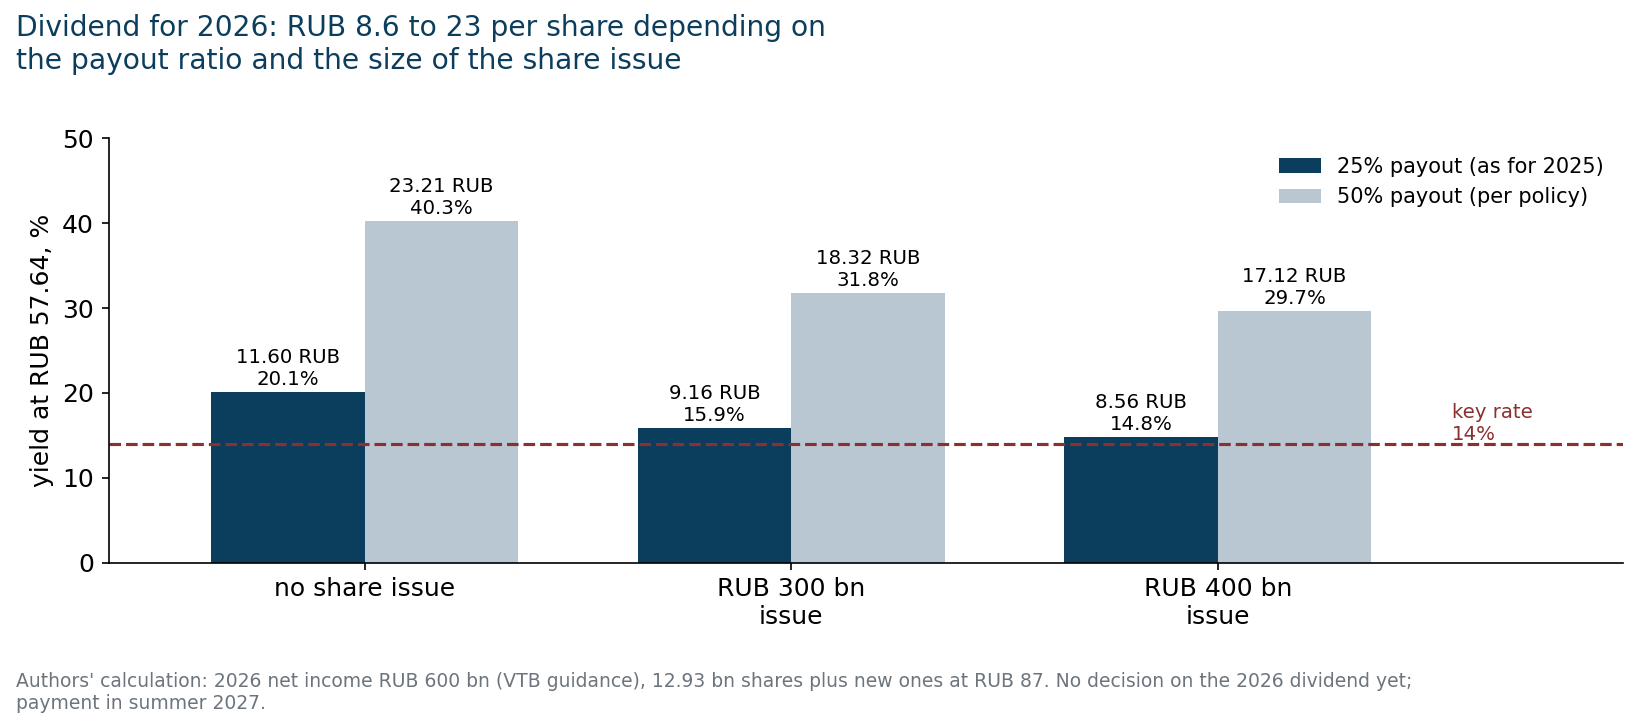
We base the 2026 dividend on guided net income of RUB 600 bn. With a 25% payout, as for 2025, and a RUB 300 bn share issue, that is RUB 9.2 per share, or 15.9% of the price. With a RUB 400 bn issue it is RUB 8.6 (14.8%). A 50% payout per the policy would give RUB 17.1-18.3 with the share issue and RUB 23.2 without it. But without the issue there is not enough capital for 50%. Our base case is a 25% payout and a RUB 300 bn issue, i.e. RUB 9.2 (authors' assumption).
Share issue at RUB 87: 51% above the market, but 2.3 times below book value
On 30 June shareholders approved an issue of up to 6.3 bn shares (about 49% of the current count) at RUB 87. The money is for a deal with RWB, the owner of Wildberries: VTB is buying 5% of WB Bank with an option to increase its stake. The placement was postponed from August to September and then to October. On 30 October Pyanov said the agreement was being "actively finalised", the size would be RUB 300-400 bn, closer to the lower end, and the state's stake would stay above 50% (PRIME, 30.10.2026). The bank does not disclose who will buy shares at 51% above the market price.
For existing shareholders the effect cuts both ways. The placement price is above the market, so the new money comes in at more than the share is worth today. But it is 2.3 times below book value per share (RUB 201 at 30 September, authors' calculation). A RUB 300 bn issue means 3.45 bn new shares (+27%). Book value per share will fall to RUB 177 (-12%), and 2026 earnings per share from RUB 42.7 to RUB 33.7 (authors' calculation, before any return on the new money).
Valuation: 0.29x book and 1.35x annual earnings – cheap, but the discount has reasons
Shareholders' equity at 30 September was RUB 2,960.7 bn. Excluding perpetual bonds (RUB 377.0 bn), ordinary shares account for RUB 2,583.7 bn, or RUB 201 per share. At RUB 57.64 the share trades at 0.29x book value. 2026 net income attributable to ordinary shares under the RUB 600 bn guidance will be RUB 549 bn after minority interests and perpetual bond coupons, or RUB 42.7 per share: P/E of 1.35x (authors' calculation).
A bank earning an 18% return on equity, with a 22% required return and 5% annual growth, would be worth (18 - 5) / (22 - 5) = 0.76x book (authors' calculation). The market pays a third of that for three reasons: share issues below book value (the second in two years: in 2025 the bank placed shares at RUB 67), a 25% payout instead of the 50% in the policy, and capital at the minimum. Until these reasons go away, a VTB shareholder receives mainly the dividend rather than growth in book value per share.
Year to date the share is down 20.2%, the Moscow Exchange index 9.4%. Since the 2Q report (28 July) VTB has gained 1.7%, the index 14.4%. In 2026 the share has traded between RUB 50.08 (17 September) and RUB 98.10 (20 April).
Scenarios to end-2027, including the 2026 dividend (authors' assumptions):
- Pessimistic (30%): RUB 400 bn share issue, 2027 net income to ordinary shares RUB 450 bn, 25% payout, P/B 0.22x. Return -9%.
- Base (50%): RUB 300 bn issue, net income RUB 550 bn, 25% payout, P/B 0.29x as now. Price RUB 61.6 plus a RUB 9.2 dividend, return +23%.
- Optimistic (20%): RUB 300 bn issue, net income RUB 600 bn, 50% payout, P/B 0.35x. Return +57%.
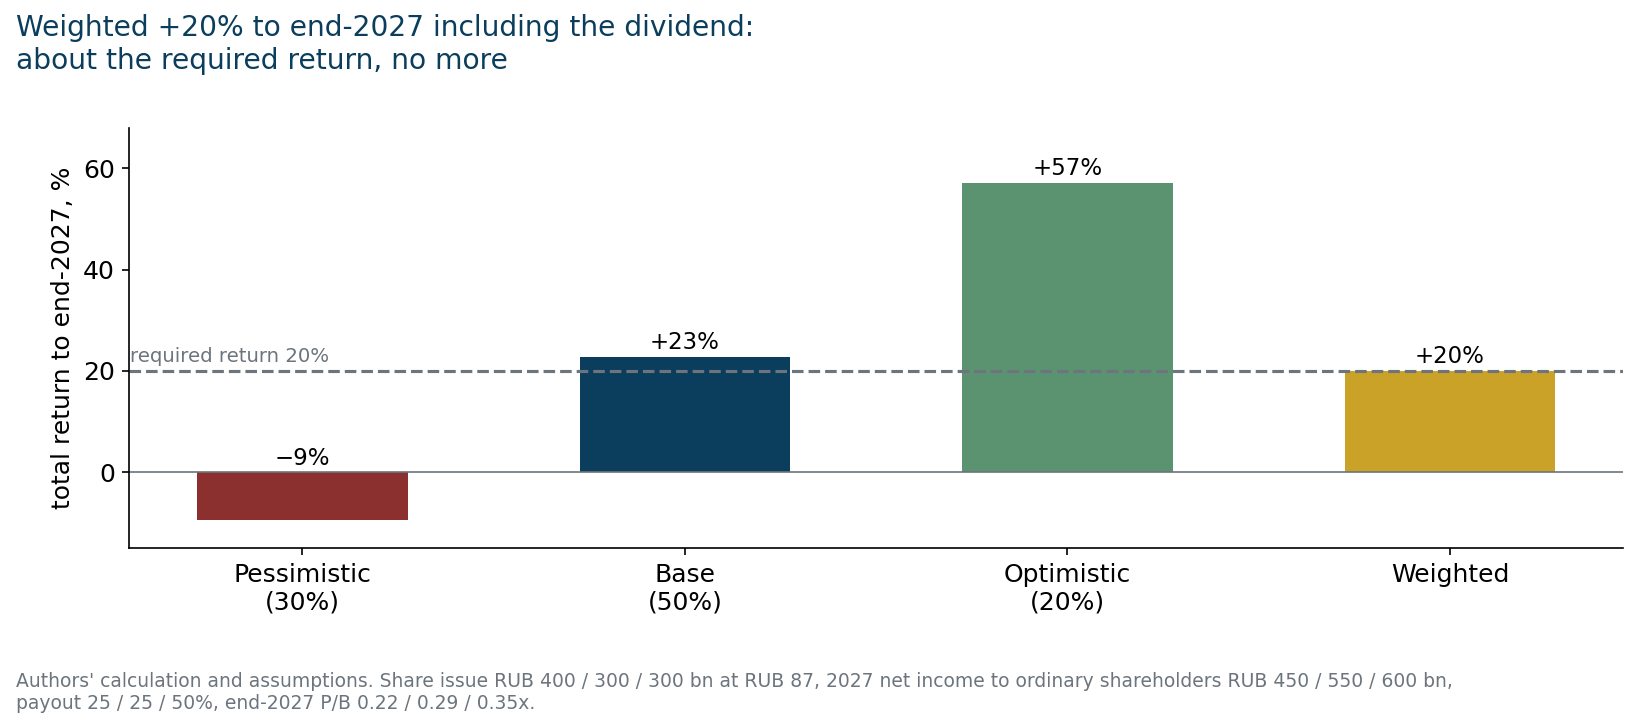
The weighted return is +20% over 14 months. With the key rate at 14%, it is reasonable to require 20% a year or more from a state bank share with dilution risk (authors' assumption). There is a margin of safety only in the optimistic scenario, in which the bank returns to a 50% payout.
Risks: one-off income, capital, dilution, loan quality
- Quality of earnings. The RUB 600 bn guidance relies on about RUB 134 bn of other income in 4Q. If bonds do not gain in value, the year may end below guidance.
- Capital. A 0.5 pp buffer over the minimum. Any growth in risk-weighted assets or new capital deductions hits the dividend.
- Dilution. An issue of up to 6.3 bn shares is approved. A size above RUB 400 bn, or another issue below book value, would lower per-share returns.
- Loan quality. Non-performing corporate loans +12% over 9M, the retail book is shrinking, retail cost of risk is 2.0%.
- Rates. The margin rose on lower funding costs. If rates go up again, the margin and bond revaluation will reverse.
Bottom line
Operationally VTB has recovered: the net interest margin nearly doubled in a year, core profit is growing, costs are under control and cost of risk is stable. But 3Q looks stronger than it is: more than half of pre-tax profit came from market and one-off income. For shareholders, the share issue and the payout ratio matter more than the bank's profit. A valuation of 0.29x book and a 16% dividend yield already price in a 25% payout and dilution. So we rate the share neutral. Three events would improve the view: a share issue of no more than RUB 300 bn, N20.0 above 11% at the start of 2027, and a decision to pay out more than 25% of profit. The next check comes with the 2026 results in February 2027, when the bank will also give its 2027 guidance.
Sources
- VTB, presentation "VTB Group financial results, 3Q and 9M 2026", 30.10.2026 (vtb.ru).
- VTB, condensed interim consolidated IFRS financial statements as of 30 September 2026 (vtb.ru).
- VTB, 2Q 2026 results presentation, 28.07.2026.
- Interfax, "VTB confirmed its 2026 net income forecast of RUB 600 bn", 30.10.2026.
- PRIME, "VTB and RWB are finalising the WB Bank deal", 30.10.2026.
- Kommersant, VTB AGM decisions on the 2025 dividend and the share issue, June 2026.
- Share and index prices – Moscow Exchange.
Open the company's financial profile VTBR →
See also: market overview · valuation map · stock screeners