Kazakhstan after the half-year: who is growing profit, who pays dividends and who is cheap
Kazakh companies have finished reporting for the first half of 2026. The last to report, on 29 September, was the gold miner AltynGold, with a record half-year. Below we go through the country's 14 listed companies: how profit grew, who pays what in dividends, and who is cheap. We also cover the backdrop: the tenge, the base rate and economic growth. Prices are as of 30 September.
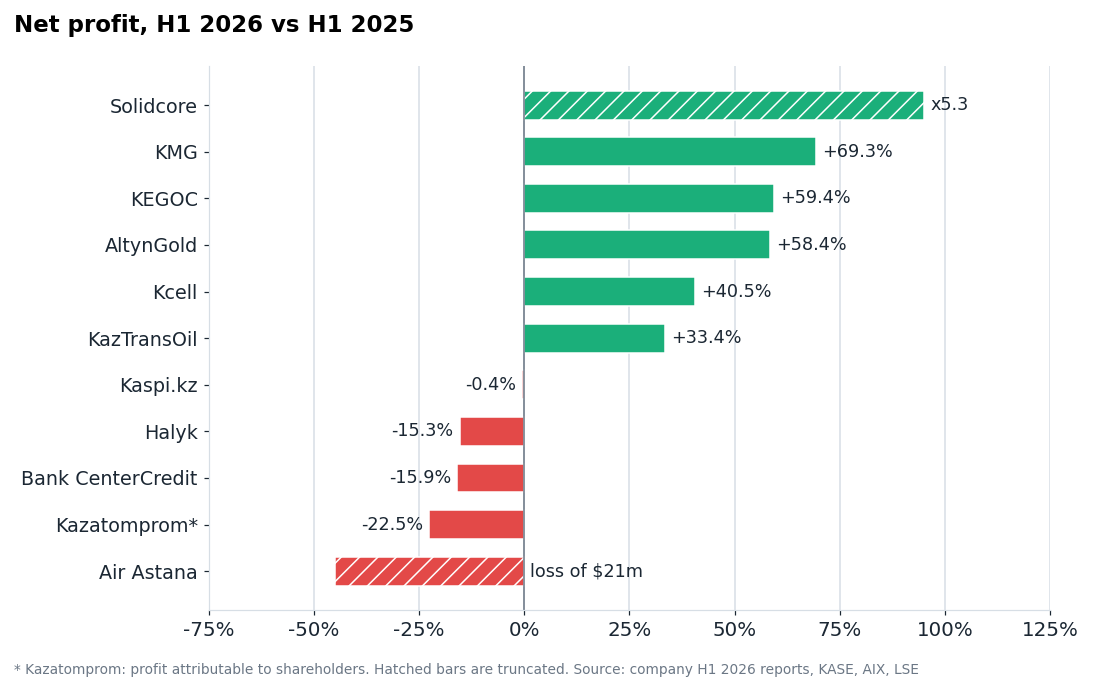
Profit is growing fastest in gold, oil and infrastructure. Solidcore's grew 5.3 times, KazMunayGas's 69%, KEGOC's 59% and AltynGold's 58%. The banks and Kazatomprom earned less than a year ago.
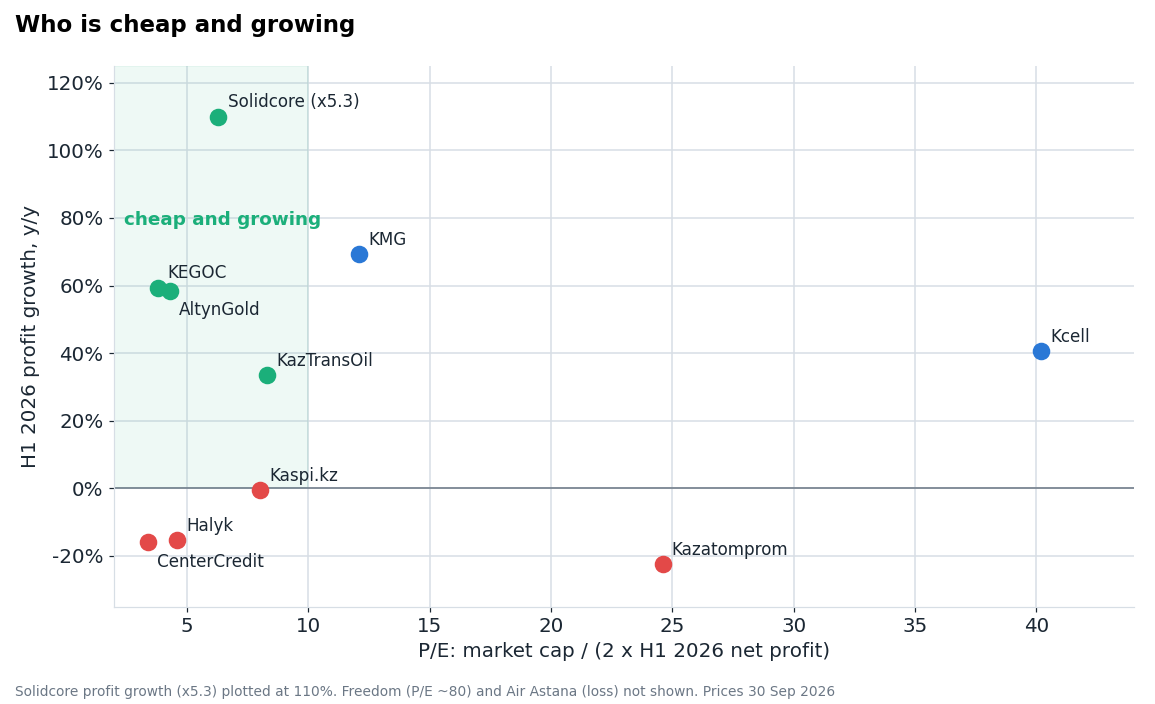
The cheapest names with growing profit are KEGOC, AltynGold, Solidcore and KazTransOil. The first three trade at a P/E of about 4-6 on annualised half-year profit. Halyk has the highest dividend yield, 15.4% over the last 12 months. Nobody beats the 16.25% base rate.
The tenge has strengthened by almost a quarter over the year, rates are being cut cautiously, and the economy is growing 4% even as oil output falls. For a dollar investor the strong tenge added 14.7% to the return on tenge stocks this year. For exporters with tenge costs it is a negative.
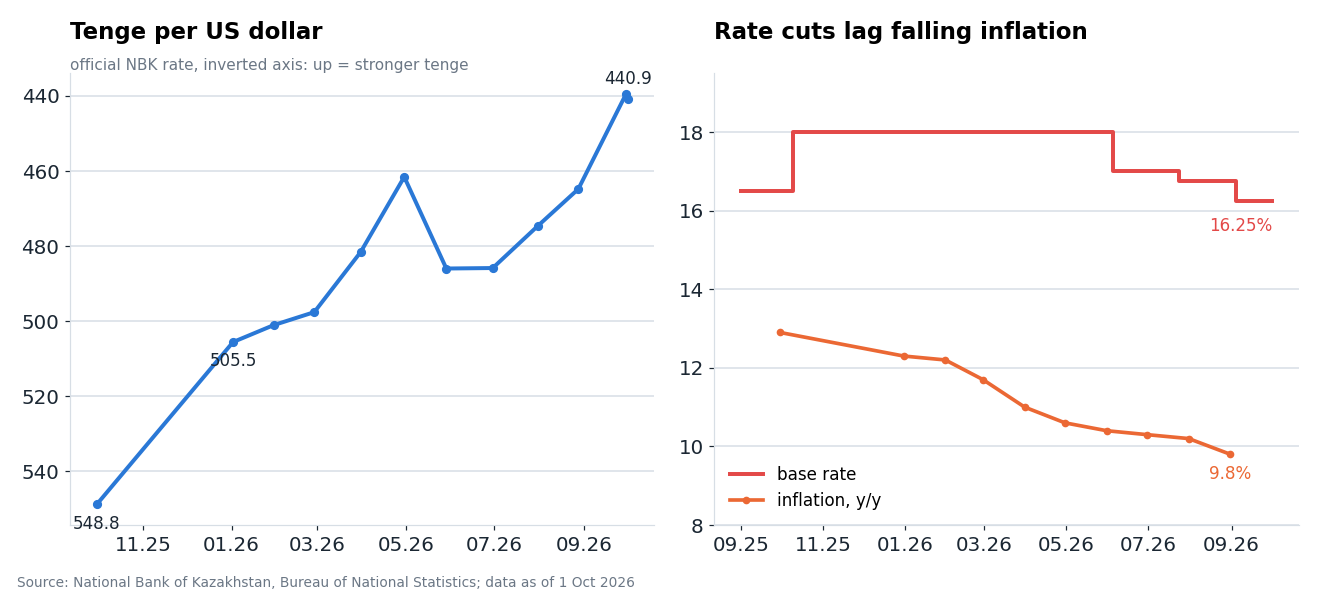
The tenge is up 14.7% this year; the dollar costs 441 tenge
The National Bank's official rate on 1 October was KZT 440.86 per dollar. At the start of the year it was 505.53, a year ago 548.79. The dollar is down 12.8% since the start of the year and 19.7% over the year. In the third quarter alone the tenge gained about 10%.
The rate is supported by expensive oil and FX sales. Brent at the end of September was about $97-103 a barrel, almost one and a half times a year ago. The National Fund sells $200-300m a month on the exchange, and since September the National Bank has added FX sales that mirror its gold operations. The real rate is also high: a 16.25% base rate against 9.8% inflation.
Rates are being cut slowly. After a hike to 18% in October 2025 the National Bank held it until June, then cut three times: to 17% on 5 June, to 16.75% on 24 July and to 16.25% on 4 September. In its September release the regulator warned that room for further cuts is limited and raised its 2027 inflation forecast to 6.5-8.5%. The 2026 forecast is 9-11%. The next decision is on 23 October. EDB analysts expect 16% by year-end.
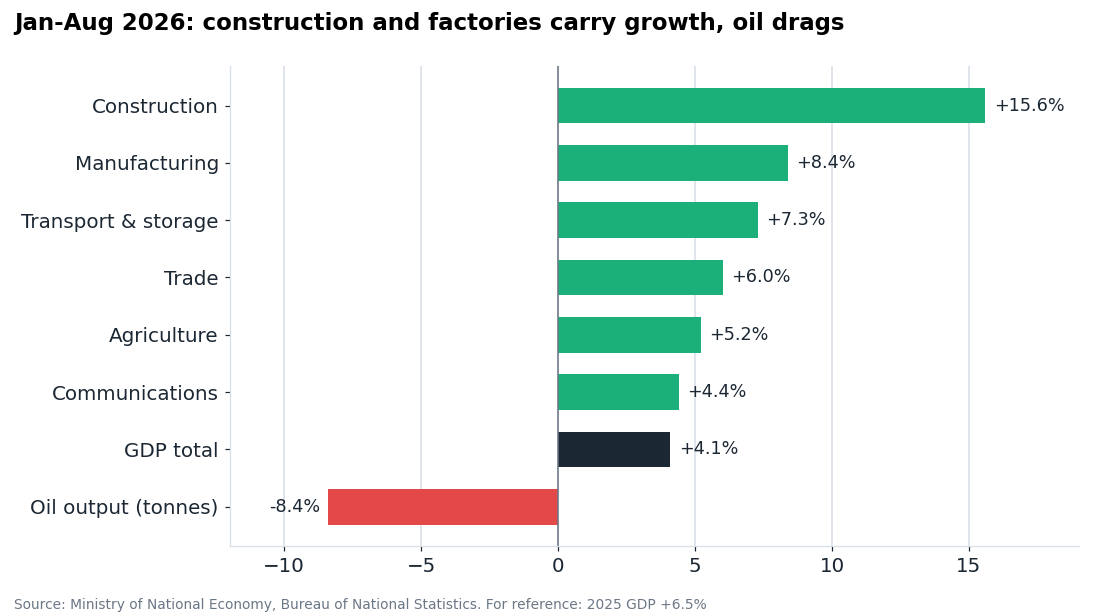
The economy is growing 4.1%, driven by construction and manufacturing, while oil holds it back
GDP grew 4.1% in January-August, the same as in the half-year and in seven months. That is noticeably slower than 2025, when growth was 6.5%. The National Bank expects 4.5-5.5% for the year, the IMF and the World Bank 4.6%, the ADB 4.8%.
The slowdown is almost entirely due to oil. Output fell 8.4% in eight months, to 61.7 million tonnes. Drone strikes on Caspian Pipeline Consortium infrastructure and a fire at Tengiz were the cause, and the annual plan was cut from 100.5 to 96 million tonnes. The non-oil economy is growing 5.4%: construction +15.6%, manufacturing +8.4%, transport +7.3%, trade +6%. According to press reports, planned maintenance at Tengiz and Kashagan has been pushed to 2027, so output may also dip next year.
Profit grew in commodities and infrastructure; banks and uranium earned less
All 14 companies have disclosed half-year results. Freedom's financial year starts in April, so its April-June quarter is used.
- Solidcore (formerly Polymetal): revenue $972m vs $325m, net profit $453m vs $85m. Output rose 71% to 210k oz, mainly thanks to Kyzyl. Net cash is $648m. Full-year guidance is 540k oz.
- KazMunayGas: net profit KZT 904bn vs 534bn, EBITDA +45%. Average Brent was $92 vs $72, and the company received KZT 441bn of dividends from Tengizchevroil. Output fell 4.6%, and net debt rose from KZT 375bn to 983bn.
- KEGOC: revenue +31%, net profit KZT 54.6bn (+59%). Cost of sales grew half as fast as revenue, 16%. Debt rose by a third in the half-year to KZT 215bn, borrowed from DBK and the ADB for construction.
- Kcell: profit KZT 7.9bn (+40.5%). But operating cash flow fell 65%, free cash flow was KZT -37.6bn, and cash fell to KZT 2.1bn from 32bn in December. The report now carries a going-concern section: current liabilities exceed current assets by KZT 43bn.
- KazTransOil: profit KZT 29.4bn (+33%). Operating profit rose only 6.7%; the rest came from interest on deposits and repo at 15-18%.
- Kaspi.kz: half-year revenue +23%, profit KZT 511bn, flat year on year. Expensive deposits and spending on Turkey's Hepsiburada weigh on it. The share of problem loans rose to 7%. The company kept its full-year guidance.
- Halyk: profit KZT 447.6bn (-15%), ROE fell from 33.6% to 24.8%. The bank names the reasons itself: higher mandatory reserves, tighter retail-lending rules, more expensive deposits. Loan-loss provisions rose 69%.
- Bank CenterCredit: profit KZT 123bn (-16%). Interest income rose 25%, but fees fell 32%, and the profit tax for banks was raised to 25% from 2026.
- Kazatomprom: revenue +9%, but profit to shareholders KZT 157bn vs 202bn (-23%). Cost per pound rose 37%; the revenue guidance was cut and the capex guidance raised.
- Air Astana: revenue +16%, but a $21m loss vs an $11m profit. Fuel at foreign airports almost doubled in price, and some aircraft are grounded because of Pratt & Whitney engines.
- Freedom Holding: quarterly revenue +40%, profit $31.7m (-15%).
- Kazakhtelecom: profit from continuing operations KZT 6.5bn. A year ago the accounts included a one-off gain from the sale of the mobile operator, hence the drop from KZT 110bn.
AltynGold reported on 29 September: profit +58%, but the shares are down 19% this year
AltynGold mines gold in East Kazakhstan; its shares trade in London. The half-year report was released on the exchange on 29 September, on the last permitted day. It is not yet on the company's website.
- Revenue $115.2m (+65%), adjusted EBITDA $68.5m (+55%), net profit $42.7m (+58%).
- 24.6k oz sold (+9%) at an average $4,615/oz vs $3,071 a year earlier.
- All-in sustaining cost rose to $1,995/oz from $1,530 for 2025. The company attributes this to taxes and the exchange rate. Its costs are in tenge and its revenue in dollars, so a strong tenge hits the margin.
- Debt fell from $41.2m to $31.4m; net debt is $19.3m, 0.15x annual EBITDA.
- Full-year guidance confirmed at 52-55k oz. The subsoil-use contract for Teren-Sai has been extended, and the mining licence there is expected in the fourth quarter.
- No dividend, and no payout policy yet. In the annual report the board promised to revisit the question.
At a market cap of about $370m, annualised half-year profit gives a P/E of about 4.3 and EV/EBITDA of about 2.8. That is the lowest valuation among the 14 companies. Yet the market does not like the stock. It is down 19% this year in pounds, although in February it cost 1.6 times what it does now. The reasons include a thin market in London, rising costs and the absence of dividends.
Recalculated at today's prices, the picture is more modest. Gold is about $4,160 an ounce, 2% below the 12-month average. The tenge is at 441 per dollar vs an average of 509 over the same period, 15% stronger. The company does not disclose the currency split of its costs. If about 80% are in tenge, they will rise about 17% in dollar terms. Annual EBITDA at the current gold price and exchange rate then comes to about $105m vs $126m over the last 12 months, and EV/EBITDA is closer to 3.7. Our platform model, which also assumes a possible reversion of gold to its three-year average, shows upside of about -8% after the report. Before the report it was +32%: the calculation then used last year's costs and ignored the exchange rate.
Cheap and growing: KEGOC, AltynGold, Solidcore, KazTransOil
The P/E on the chart is rough: market cap over twice half-year profit. For seasonal businesses it is an approximation, but good enough for comparing companies.
- KEGOC: P/E about 3.8 with profit up 59%. The downsides are that the state sets the tariff and that the company is taking on more and more debt for construction.
- AltynGold: P/E about 4.3, growth +58%, almost no debt. But the strong tenge is already eating the margin; at the current gold price and exchange rate EV/EBITDA is about 3.7. The risks are the gold price, the tenge and the liquidity of the stock.
- Solidcore: P/E about 6.3, profit up 5.3 times, $648m of net cash. The shares have doubled this year and have partly priced in the growth. It pays no dividend; the cash goes into the Ertis POX autoclave. All of its mines are in Kazakhstan, so a strong tenge squeezes its costs just as it does AltynGold's.
- KazTransOil: P/E about 8, but the profit growth rests on deposit interest. When rates fall, that income will shrink.
Cheap, but bank profit is falling. Halyk trades at 4.6x earnings, CenterCredit at 3.4x. Both slipped because of regulation and the tax, while lending is growing. Kaspi.kz trades at about 8 annual earnings with zero growth. The expensive names: Kazatomprom (about 25x), KazMunayGas (12x after a 65% rally this year), Kcell (about 40x), Kazakhtelecom (about 37x) and Freedom (about 80x on the annualised last quarter). Kazatomprom's and KazMunayGas's revenue is tied to the dollar while they report in tenge. At 441 against an average of 509 over the year, tenge revenue at current uranium and oil prices is lower, and after the exchange-rate adjustment the platform model sees no upside for them: about -13% and 0%.
Dividends: Halyk is closest to the rate; KEGOC and KazTransOil yield about 10-11%
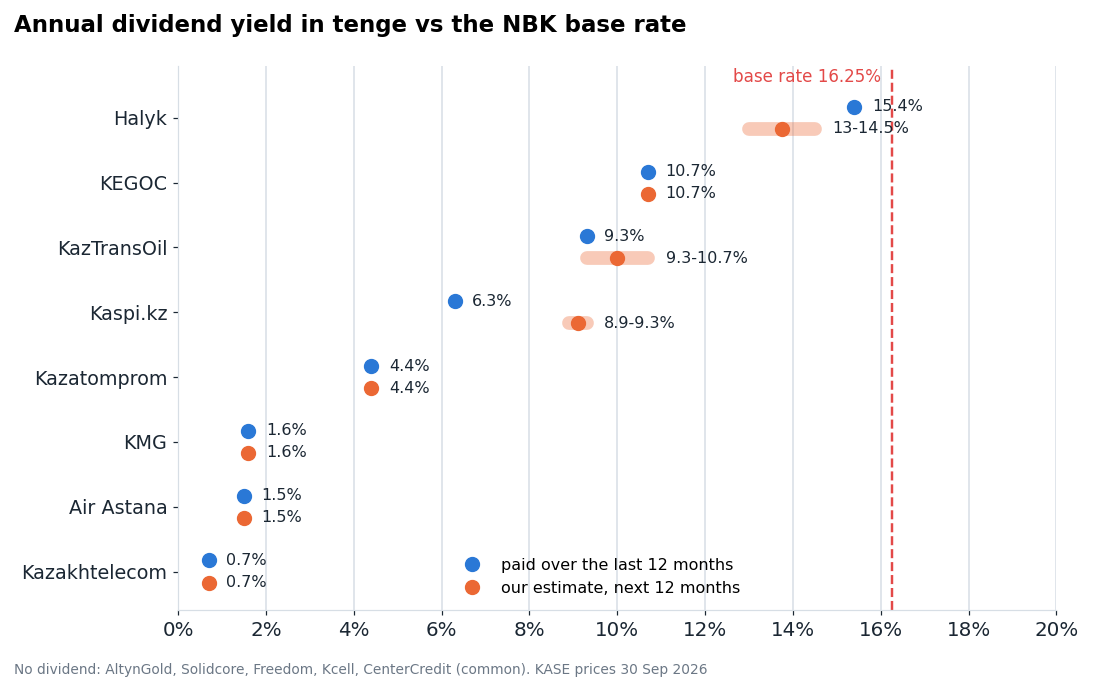
Only an annual yield is comparable with the base rate. So for each stock we show two measures: what was paid over the last 12 months and our estimate of payments over the next 12 months.
- Halyk pays twice for one year. For 2025 it paid KZT 30.10 in May and another 28.09 in September out of retained earnings. That is 58.19 in total, or 15.4% of the price. If the bank keeps a 55-60% payout on annual profit of about KZT 0.9-1 trillion, the next 12 months come to 13-14.5%.
- KEGOC pays twice a year. The board proposed KZT 81.25 for the first half of 2026; the meeting is on 8 October and the record date is 14 October. Annualised that is about KZT 162, or 10.7%. This is 41% of profit, so the company has room to raise payouts.
- KazTransOil paid KZT 118 for 2025 (9.3%), which is 80% of profit. At the same payout and with profit at the half-year pace, 2026 would bring about KZT 135, or 10.7%.
- Kaspi.kz has paid quarterly again since 2026: KZT 850 for 2025, 850 for the first quarter and 1,000 for the second. Over 12 months that is 6.3%. At KZT 1,000 a quarter, the next 12 months come to about 9%.
- Kazatomprom paid KZT 1,292 for 2025, or 4.4%. KazMunayGas, Air Astana and Kazakhtelecom yield no more than 1.6%.
AltynGold, Solidcore, Freedom and Kcell pay no dividends; CenterCredit pays only on preferred shares.
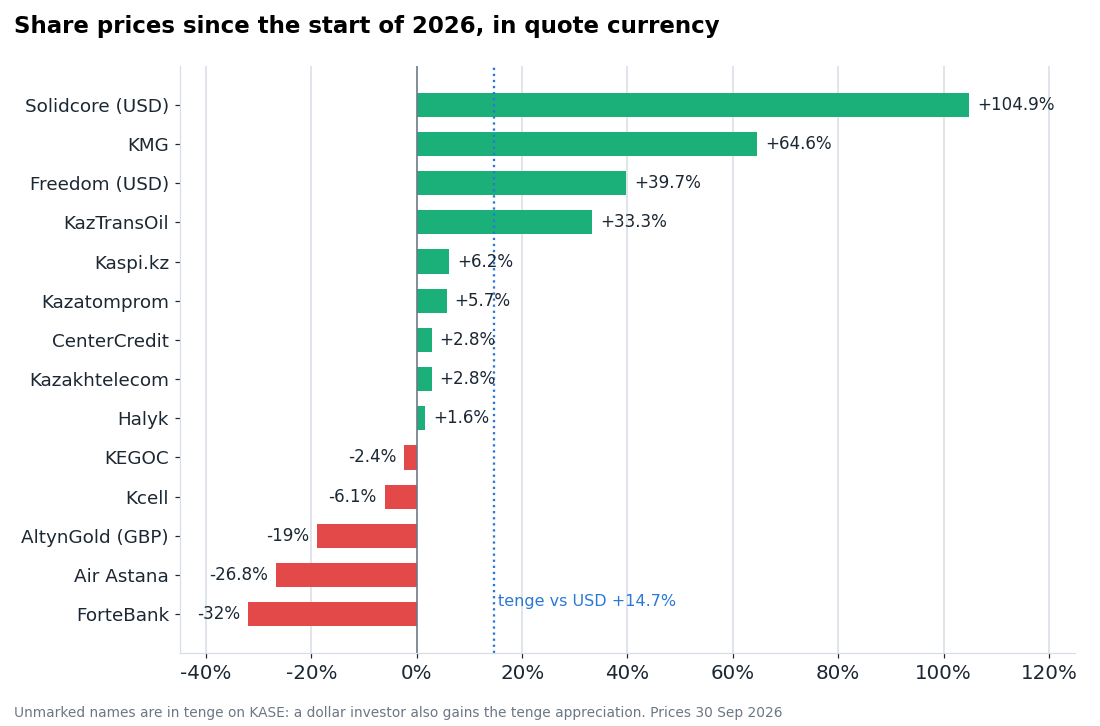
Year to date, Solidcore and KazMunayGas did best, ForteBank and Air Astana worst
Solidcore's shares in dollars rose 2.05 times, following gold and output. KazMunayGas added 65% on expensive oil, KazTransOil 33%. The banks barely moved. ForteBank lost 32%, Air Astana 27%, AltynGold 19%.
For an investor who counts in dollars, 14.7% of tenge strengthening should be added to tenge quotes. Halyk is up 1.6% in tenge and almost 17% in dollars. The same effect can work in reverse if oil gets cheaper or the National Bank cuts its FX sales.
What looks attractive
On price versus growth, KEGOC, AltynGold and Solidcore stand out. KEGOC adds a dividend of about 11% in tenge. AltynGold is the cheapest on reported earnings, but it pays no dividend, has a thin market, and the strong tenge is already eating part of its margin. Solidcore has already risen a lot.
For dividends, Halyk is interesting at 13-15% a year and a P/E of about 4.6. The bank's half-year profit fell 15%. Monthly National Bank data show a 24% decline in July and only 3% in August (KZT 76bn vs 79bn); the stage-3 problem-loan share edged down from 8.3% to 8.1%. Over eight months the bank earned 6% less than a year ago. KazTransOil yields about 10%, but part of its profit rests on high deposit rates.
KazMunayGas and Kazatomprom look expensive after their rally, with dividend yields of 1.6% and 4.4%, and the strong tenge cuts their tenge revenue. Kcell's debt is rising and its cash is running out.
Company cards with financials, multiples and dividend history are on the Enhanced Investments Frontier platform.
See also: market overview · valuation map · stock screeners